


Has Kureha (TSE:4023) Run Too Far Ahead Of Its Fundamentals?
Kureha (TSE:4023) just closed at ¥4,195, capping a month in which the share price gained about 4%, while the past 3 months show a decline of roughly 2%.
Short term momentum around Kureha has picked up, with a 1 day share price return of 4.48% and a 7 day move of 8.12%. However, the 90 day share price return is down 2.21%, while the 1 year total shareholder return sits at 19.64%, suggesting that recent optimism follows a longer stretch of more measured gains.
Scan how Kureha's recent momentum compares with other potential breakouts by reviewing our hand-picked list of 16 high quality undervalued stocks in similar market conditions.
Kureha has just sprinted higher, yet the share price still sits above the average analyst target while screens flag a steep intrinsic discount. So where does fair value actually land within that spread?
Price-to-Sales of 1x: Is it justified?
Kureha looks expensive on its preferred measure, with a P/S of 1x at a last close of ¥4,195, while the broader chemicals space and fair value models both point to lower levels.
The P/S ratio compares the market value of the equity with the revenue the business generates. For a group like Kureha that is currently loss making, this metric becomes a shorthand for how much investors are willing to pay for each ¥ of sales when earnings are not yet a clean guide.
Here that willingness runs high. Kureha trades on a P/S of 1x even though the estimated fair P/S is 0.8x. This is a level the market could move towards if sentiment cools. The stock also sits above the JP chemicals industry average P/S of 0.7x, which signals investors are paying a clear premium to both sector peers and a fair value model built around fundamentals.
Explore the SWS fair ratio for Kureha.
Result: Price-to-Sales of 1x (OVERVALUED)
Still, the recent net income loss of ¥8,465 and the fact that Kureha is trading above the average analyst target of ¥3,798 could both challenge the current bullish tone.
Find out about the key risks to this Kureha narrative.
Another view using the SWS DCF model
The SWS DCF model paints a different picture for Kureha. From this perspective, the fair value estimate sits at ¥2,562.85 per share, well below the current ¥4,195 level. That points to an overvalued stock on cash flow terms and raises a simple question for investors: Which signal do you trust more, sales or cash flows?
Look into how the SWS DCF model arrives at its fair value.
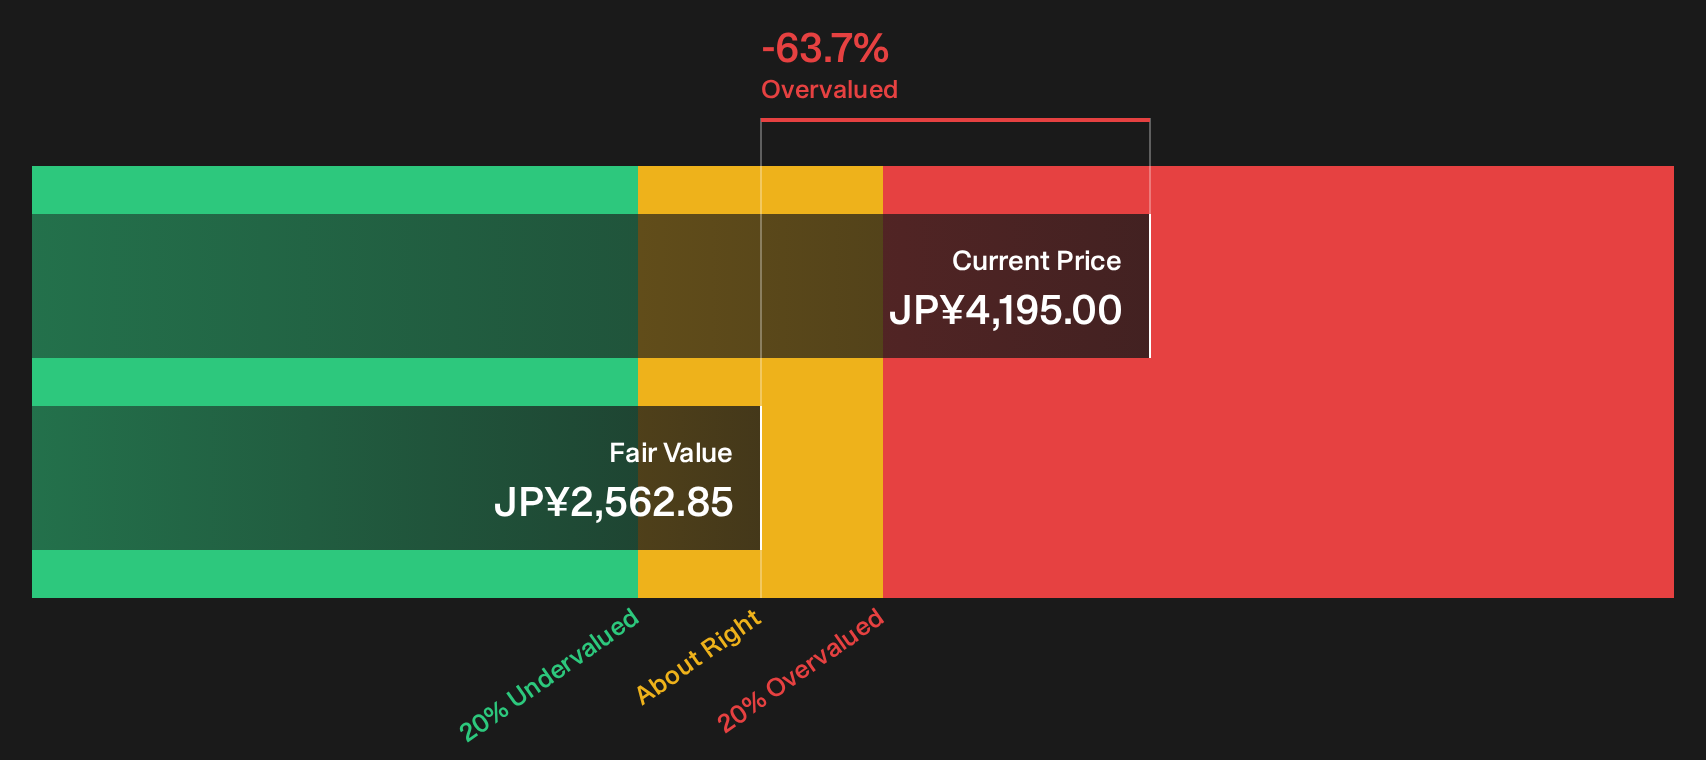
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kureha for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Kureha is clearly split. This is exactly why you should run the numbers yourself, weigh the trade offs, and study the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Kureha?
If Kureha has your attention, do not stop there. Use the Simply Wall Street Screener to quickly surface fresh opportunities that match your style and risk comfort.
- Target reliable income streams by reviewing 28 dividend fortresses that focus on delivering meaningful yields supported by underlying fundamentals.
- Hunt for resilient performers through a curated 23 resilient stocks with low risk scores that aims to keep drawdowns in check while still offering equity market exposure.
- Spot potential future favorites early by scanning a focused 69 high quality undiscovered gems packed with companies that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com