


Pilgrim's Pride (PPC) Jumped, But What Is Driving Attention Now?
Pilgrim's Pride (PPC) just posted third quarter and year to date results that showed lower sales and sharply reduced net income compared with a year earlier, putting earnings quality under closer investor review.
The earnings release landed alongside a sharp 4.02% 1 day share price gain to US$28.72, capping a 4.44% 30 day share price return but still leaving the year to date share price down 27.97% and the 1 year total shareholder return lower by 24.62%. However, the 3 year and 5 year total shareholder returns of 29.55% and 20.91% respectively show that long term holders of Pilgrim's Pride have seen a very different experience from the recent pullback.
Spot opportunities across the wider protein and food space by reviewing our hand-picked 19 high quality undiscovered gems that may not yet be fully on the market’s radar.Pilgrim's Pride now trades higher on the day yet sits well below where it started the year, so does that recent bounce still leave enough upside to justify the earnings hit when you run the numbers?
Most Popular Narrative: 14% Undervalued
Pilgrim's Pride most followed narrative points to a fair value of $33.29 versus the last close at $28.72, which frames the recent bounce as only a partial catch up to that estimate.
The heavy capex cycle focused on case-ready conversions, deboning and portioning upgrades, a new prepared foods plant and European network optimization is aimed at improving yields and labor efficiency. This can support structurally higher operating margins and cash generation once larger projects move from the build phase to full production.
See why 18 investors see Pilgrim's Pride as 14% undervalued.
Result: Fair Value of $33.29 (UNDERVALUED)
Still, the Pilgrim's Pride story can break if chicken supply keeps pricing under pressure or if Mexico's weaker margins persist longer than analysts currently factor in.
Find out about the key risks to this Pilgrim's Pride narrative.
Another View: Pilgrim's Pride Through A Cash Flow Lens
The first narrative around Pilgrim's Pride leans on earnings forecasts and price targets, yet the Simply Wall St DCF model points to a fair value of about $25.85, below the current $28.72 level. That implies the stock screens as overvalued on projected cash flows, which raises a simple question. Which set of assumptions do you trust more: the earnings story or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
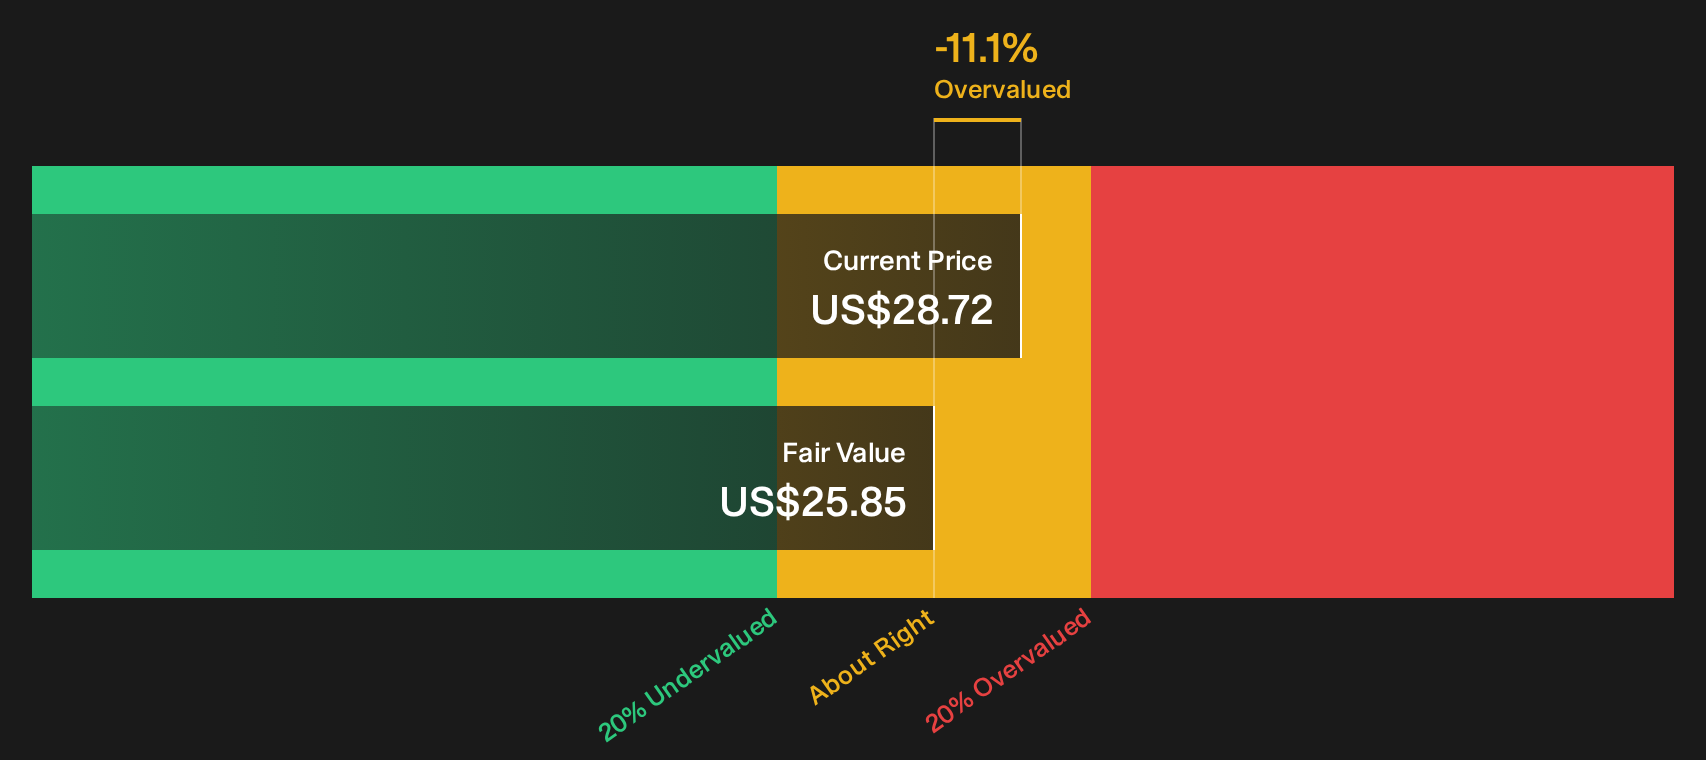
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pilgrim's Pride for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Pilgrim's Pride so far, right? If the blend of pressure and potential has you on the fence, move quickly to review the data for yourself and then weigh up the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Pilgrim's Pride?
If Pilgrim's Pride has you thinking harder about where risk and reward really meet, widen your search and let the data surface fresh opportunities for you.
- Target resilient candidates first by scanning a 29 resilient stocks with low risk scores that already filters for sturdier balance sheets and calmer risk profiles.
- Hunt for pricing missteps using a focused list of 33 high quality undervalued stocks that combine stronger fundamentals with more modest expectations baked into current prices.
- Zero in on financial strength with a curated list of solid balance sheet and fundamentals (24 results) and quickly spot businesses that back their story with cleaner debt and asset positions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com