


eBay (EBAY) Could Be 24% Undervalued After Q3 Earnings Beat
Fresh off a better than expected third quarter update, eBay (EBAY) is back on investors radar as the marketplace story is supported by a stronger set of headline numbers.
Over the past month, eBay shares have climbed, with a 30 day share price return of 14.32% helping lift the year to date share price gain to 39.72%. The 1 year total shareholder return of 51.51% and very large 3 year total shareholder return of about 22x suggest momentum has been building around the business as recent earnings surprises, product launches such as eBay Live and the Most Wanted Collection, and ongoing recommerce initiatives reshape how investors view its growth potential and risk profile.
Capitalize on eBay’s earnings momentum by scanning a curated set of digital commerce and platform plays through 33 high quality undervalued stocks that may offer similar operational traction with more attractive pricing.The strong move in eBay now forces a tougher read. Are investors finally paying up for underlying execution in Q3 and newer products, or has sentiment simply sprinted ahead of what the fundamentals justify on valuation?
Most Popular Narrative: 16% Overvalued
On the latest numbers, the most followed valuation narrative pegs eBay’s fair value at $104.94, which sits below the recent $121.64 close and signals a market price that runs ahead of that framework.
This is not a standalone acquisition. It is the second to last step in a multi year, traceable architecture: PSA partnership (May 2024), Turner board seat (November 2024), PowerPacks JV (March 2025), Power Packs trademark (July 2025), Cohen 100 billion performance award (January 2026), eBay bid (May 2026), then (implied) Collectors acquisition, then (implied) tZERO integration. The eBay filings only show one move on a much larger board.
See why 4 investors see eBay as 16% overvalued.
Result: Fair Value of $104.94 (OVERVALUED)
Still, the GameStop bid narrative leans heavily on unconfirmed Gulf financing and ambitious cost cut assumptions. Either of these factors, if weakened, could quickly blunt eBay enthusiasm.
Find out about the key risks to this eBay narrative.
Another View on eBay’s Valuation
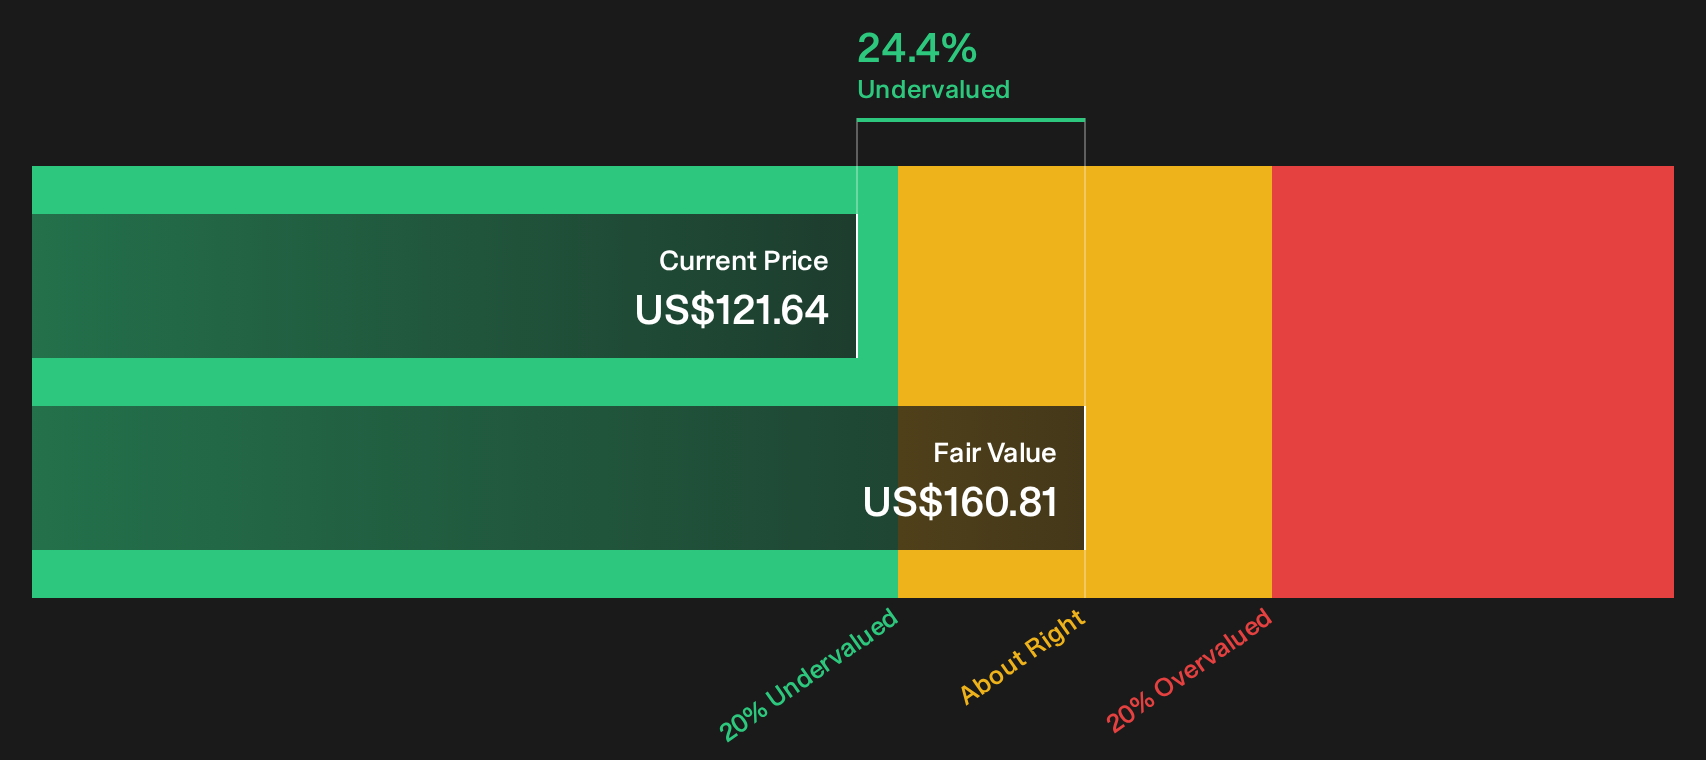
The first narrative framed eBay as 16% overvalued at $121.64 versus a $104.94 fair value. A different lens tells a very different story. Our DCF model points to a future cash flow value of $160.81, which implies eBay trades at a 24.4% discount instead of a premium.
Those two frameworks cannot both be right at the same time, so the real question for investors is which set of assumptions about cash generation and risk feels more realistic for eBay over the long haul.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out eBay for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around eBay can be useful if you move quickly and stress test the numbers yourself before momentum cools. For a sharper view on where the balance of concern and optimism really sits, take a look at the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond eBay?
Do not stop with eBay. Broaden your opportunity set by using targeted screeners that surface stocks with traits you care about before the crowd does.
- Target resilient payers that keep cash coming in by reviewing a focused set of income ideas through the 5 dividend fortresses.
- Zero in on sturdier balance sheets by filtering for companies with healthier finances through the list of solid balance sheet and fundamentals (24 results).
- Hunt for future standouts that are not widely followed yet by scanning the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com