


Sonoco (SON) Stock May Be Below Fair Value Following Q3 Loss News
Sonoco Products has risen 28.5% over the past year, which puts fresh attention on a simple question for anyone looking at the packaging group today. Is the current share price around US$49.96 well supported by the revenue the business is generating, especially after a large reported loss tied to goodwill?
- The 28.5% 1 year gain means anyone buying now is paying a meaningfully higher tag for Sonoco Products than a year ago, so the link between that move and its sales starts to matter more.
- The reported net loss of about US$732m, driven mainly by an US$829m non cash goodwill impairment, can reshape how investors think about the durability of past deals and the sales base tied to those segments.
- Your read on Sonoco Products is one view; the desks covering it have another. See what analysts think Sonoco Products's shares could be worth.
The issue now is whether Sonoco Products' current share price can be explained by its sales when set against a Fair Ratio yardstick.
If you are weighing whether Sonoco Products' 1 year gain and goodwill hit line up with its sales, it can help to compare that trade off against 33 high quality undervalued stocks.
Is Sonoco Products Still Cheap on Sales?
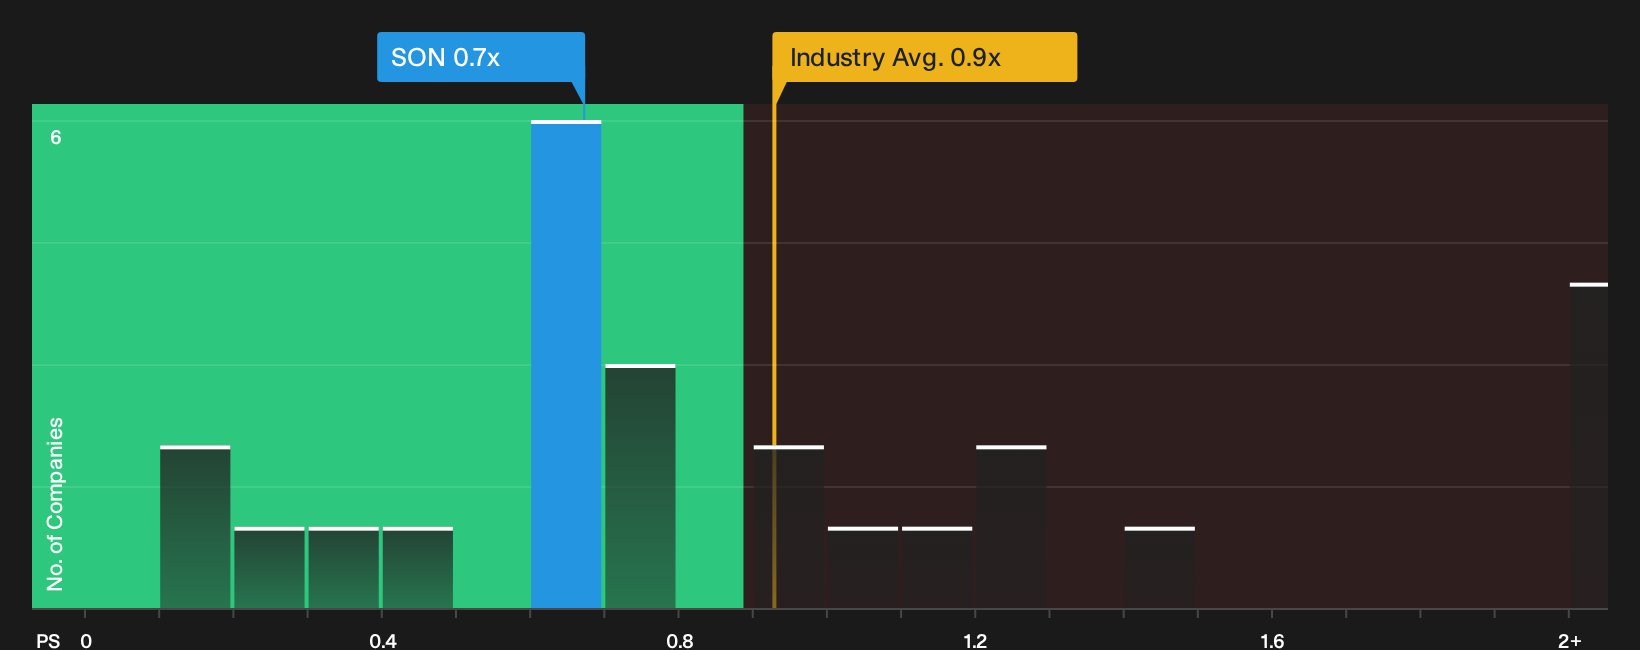
For Sonoco Products, the P/S ratio is a useful gauge because recent earnings are distorted by the goodwill charge, while revenue still reflects the scale of the business. The stock trades on a P/S of 0.7x, which is slightly below the Packaging industry average of about 0.7x and also below the peer group average of 0.9x. Compared with a Fair Ratio that reflects Sonoco Products' mix of segments, margin profile, size and perceived risk, the current multiple appears on the cheaper side rather than expensive.
Because the recent US$732m loss stems mainly from an US$829m goodwill impairment instead of a collapse in sales, the lower P/S multiple suggests the share price is not giving full credit to the existing revenue base. Despite that impairment and softer Consumer Packaging volumes, the stock still trades at a discount to what the Fair Ratio model indicates for this level of revenue. Explore the numbers behind Sonoco Products's P/S valuation.
The Sonoco Products Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Sonoco Products pick up where this valuation puzzle leaves off by spelling out which combinations of future growth, margins and earnings would need to play out for the shares to look meaningfully higher or lower than today. Rather than a single ratio or model headline, each narrative lays out the assumptions that sit behind its view of fair value so you can track how those expectations compare with Sonoco Products' actual results over time on the Community page.
One of the top community narratives on Sonoco Products: 21% undervalued
"The multi year Profitability Performance Plan has already reached US$34 million of year to date savings and US$51 million on an annualized basis…"
Discover why this Narrative puts Sonoco Products at 21% undervalued.
One more piece of the Sonoco Products story to check first
Before you lean too heavily on where Sonoco Products trades on sales, it is worth knowing that Simply Wall St’s broader checks have raised specific concerns that could change how you frame the risk. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com