


Brinker International (EAT) After Earnings Beat And Outlook Lift Faces A Fair Value Debate
Why Brinker International Stock Is Back in Focus
Brinker International (EAT) moved back onto investor watchlists after first quarter fiscal 2027 results topped expectations and the company raised its full year revenue and earnings outlook.
Short term traders just saw a sharp pullback, with a 1 day share price return of down 3.5% to US$212.18 after a strong run that left the 7 day share price return at 16.1% and year to date share price return at 40.0%. Longer term holders have experienced a 1 year total shareholder return of 95.3% and a 3 year total shareholder return above 5x, suggesting momentum around Brinker International has been building as earnings beats and the raised fiscal 2027 outlook reset expectations on both growth potential and perceived risk.
Capture the same earnings-fueled momentum that recently brought Brinker International back into focus by scanning a curated 33 high quality undervalued stocks featuring companies with solid cash flows and stronger balance sheets.The business story around Brinker International looks strong after the outlook lift and sharp share price move. The open question now is whether that momentum already fully shows up in the current valuation.
Most Popular Narrative: 19% Undervalued
Brinker International's most followed narrative pegs fair value at about $262.59, compared with the last close at $212.18. This view puts a lot of weight on Chili's current unit economics and growth plans staying on track under an 8.89% discount rate.
Brinker International is extending its menu work at Chili's, including upgrades in core items and beverages, on top of a higher earning restaurant model where AUVs have reached about $5 million and restaurant operating margin has widened by 660 basis points. This can support further revenue and earnings growth if traffic and mix benefits continue to scale.
See why 31 investors see Brinker International as 19% undervalued.
Result: Fair Value of $262.59 (UNDERVALUED)
Still, the bullish Brinker International narrative assumes that Chili's digital and to-go push hits its targets, while labor and commodity cost inflation does not squeeze margins harder than expected.
Find out about the key risks to this Brinker International narrative.
Another View: Brinker International Through A Cash Flow Lens
The popular Brinker International story leans on earnings based fair value of $262.59, yet the SWS DCF model paints a different picture. On projected future cash flows, the stock screens as overvalued versus an estimate of $184.62 per share, which raises a simple question: Are you paying for more than the cash flows justify today?
For anyone weighing that gap between earnings based upside and the cash flow signal, it is worth seeing how the underlying assumptions stack up in practice, starting with the Look into how the SWS DCF model arrives at its fair value.
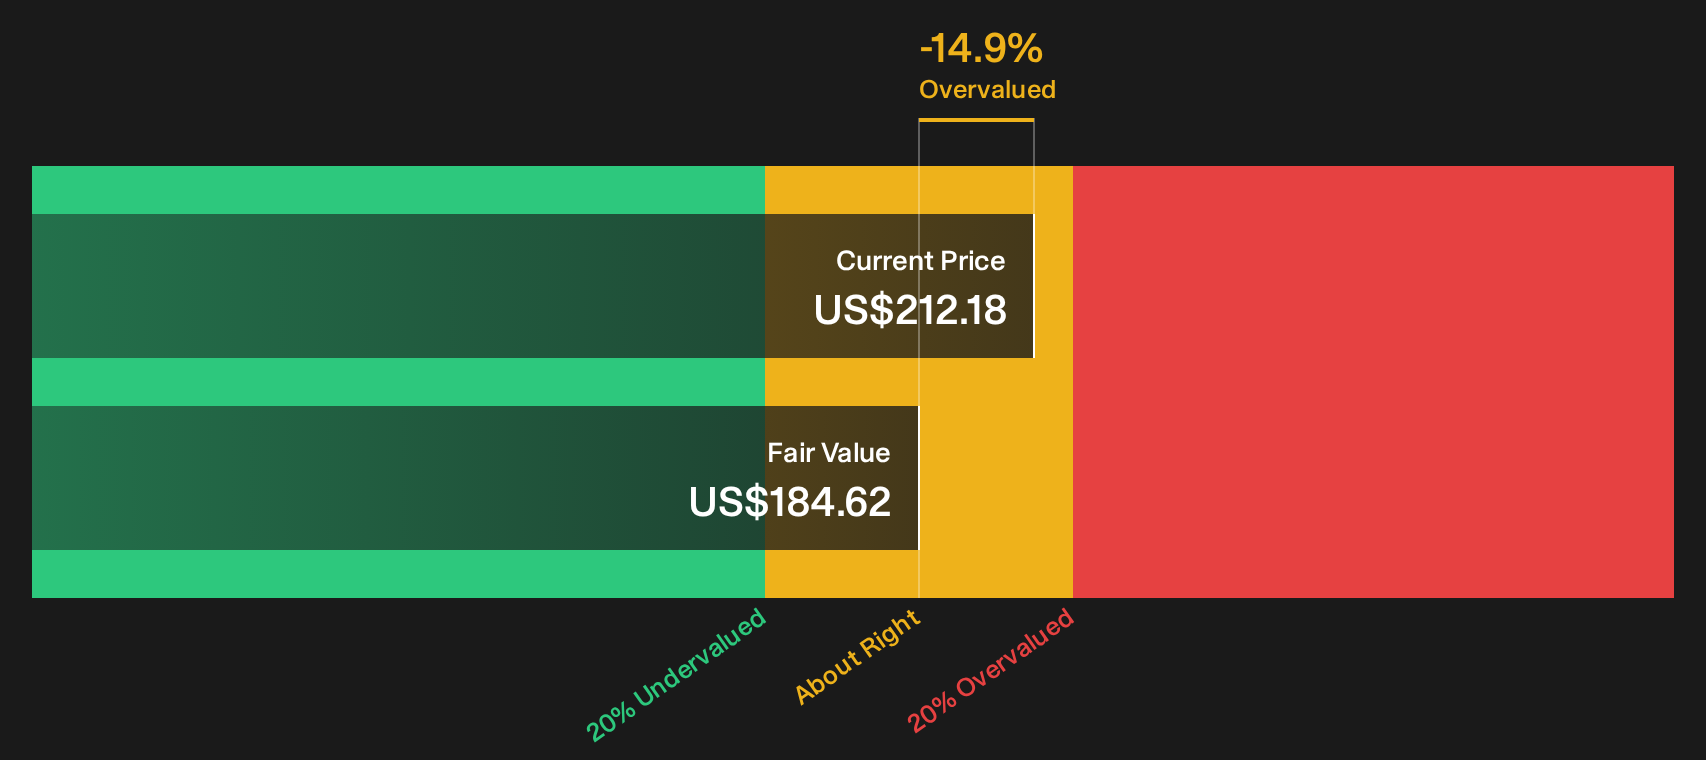
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Brinker International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Brinker International feels familiar, do not wait on others to frame the story for you. Weigh the upside against the potential drawbacks by reviewing the 5 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Brinker International?
Do not stop your research at Brinker International. Broaden your opportunity set with a few focused stock lists that highlight different ways to balance return potential and risk.
- Target dependable cash generators by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you avoid fragile balance sheets when conditions get tougher.
- Hunt for overlooked opportunities through a 19 high quality undiscovered gems that surfaces quality businesses the crowd has not fully focused on yet.
- Dial back downside risk with a 29 resilient stocks with low risk scores so you are not caught holding the most fragile stocks when sentiment cools.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com