


Should Transition Year Guidance Require Action From Pluxee Stock Investors?
- Pluxee reported full year 2026 sales of €1,302 million and net income of €170 million, with earnings per share at €1.21.
- The group exceeded its own recurring EBITDA and revenue objectives yet flagged regulatory reforms as a headwind that could pressure 2027 profitability.
- We will now look at how Pluxee's investment narrative is shaped by stronger than targeted 2026 EBITDA, together with a 2027 transition.
Pluxee Investment Narrative Recap
To own Pluxee, you need to be comfortable with a story that mixes operational progress with regulatory friction. The investment case leans on Employee Benefits expansion, tight cost control and execution on acquisitions and partnerships. The latest results show revenue at €1,302 million and net income at €170 million, which keeps the focus firmly on profitability resilience.
The short term catalyst is whether recurring EBITDA can absorb the impact of regulatory reform while management pushes efficiencies and scales AI. The biggest near term risk sits in those same rule changes, particularly in Brazil, which could pressure margins if cost savings and product mix shifts do not come through quickly enough.
The most relevant update is Pluxee flagging fiscal 2027 as a transition year, with regulatory reforms expected to reduce recurring EBITDA despite stronger than targeted 2026 performance. That framing matters because it tells you management sees a near term dip in profitability even as the operational engine in Employee Benefits is still gaining traction.
For you as a shareholder, the question is whether priorities for 2027, such as growing Employee Benefits volumes, driving efficiency and scaling AI, can offset the PAT reform impact over time. Execution against that plan, together with how quickly Pluxee reshapes its Brazilian operations and cost base, will likely influence how the stock responds to future earnings updates.
What The Pluxee Forecasts Assume About Growth
Pluxee's narrative projects €1.4b revenue and €215.0 million earnings by 2029. This reflects an assumption of 2.3% yearly revenue growth and a €10.0 million earnings increase from €205.0 million today.
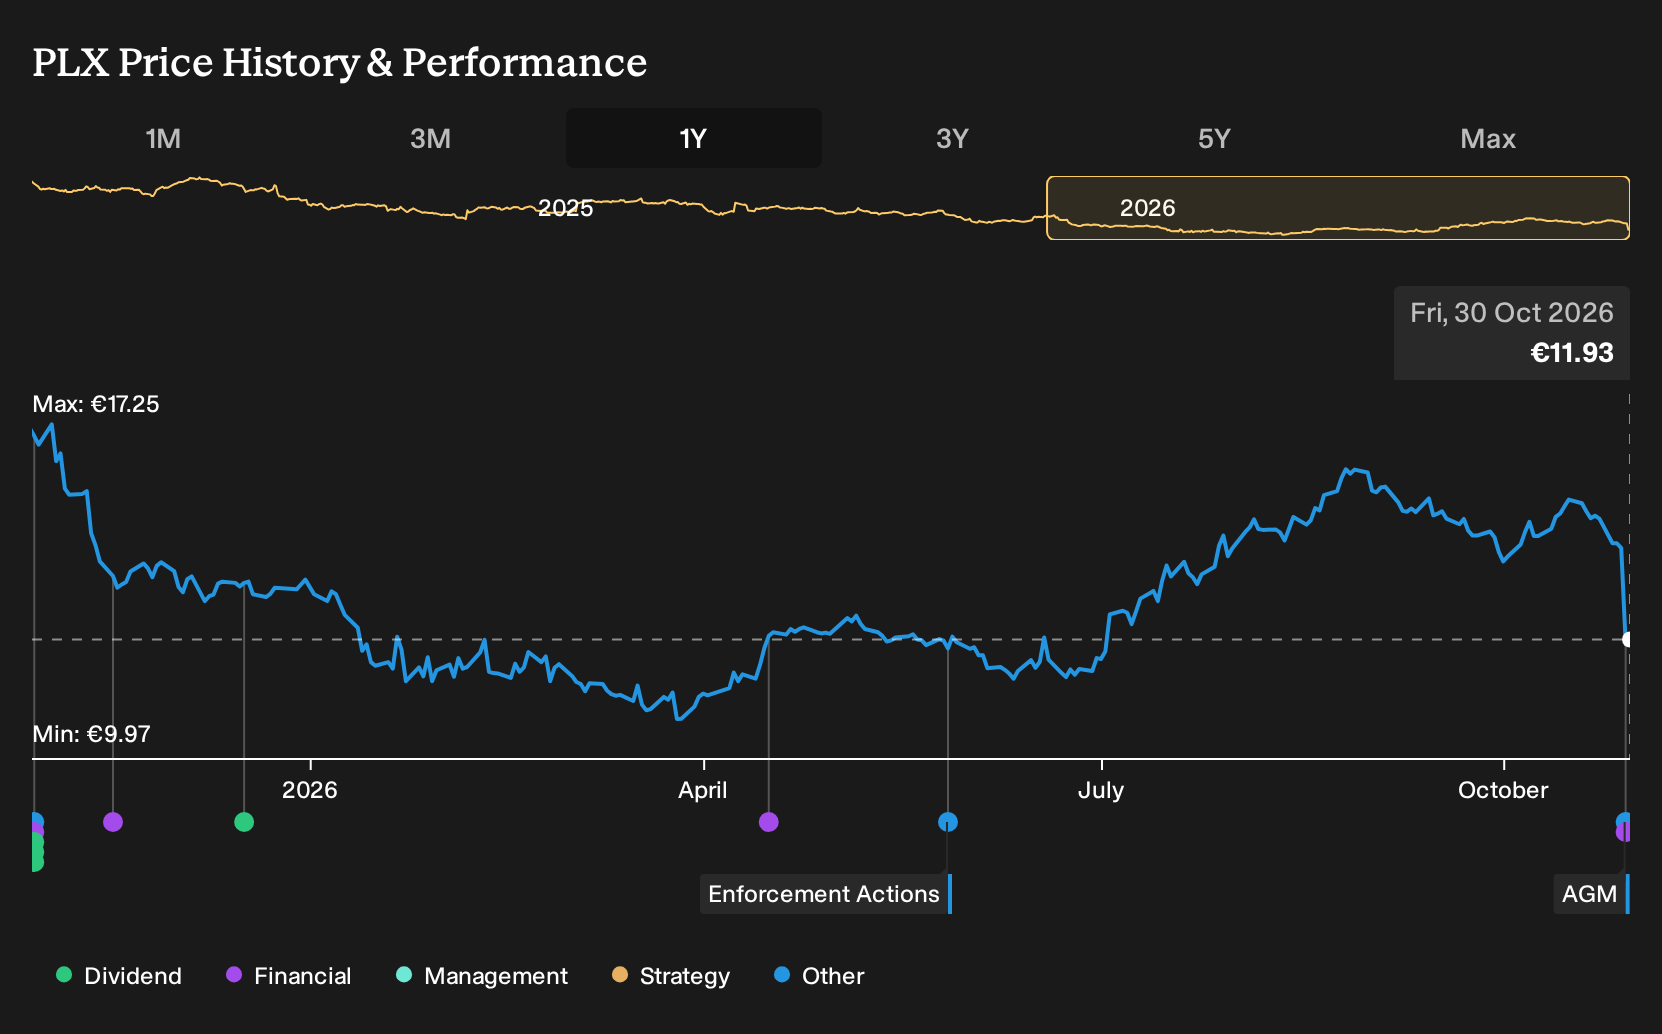
Uncover how Pluxee's fair value indicates a 33% potential upside to its current price that could narrow quickly if sentiment shifts toward Pluxee.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Pluxee’s cash pile and buyback capacity as a potential accelerator. Before these earnings, they were working off assumptions of roughly €1.4b revenue and about €205.4 million in earnings by 2029. You now have fresh 2026 figures, so treat those earlier projections as moving pieces and explore several angles before deciding what feels reasonable.
Explore 4 other Pluxee fair value estimates, including one that suggests as much as 158% potential upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pluxee research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Pluxee. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pluxee's overall financial health at a glance.
Looking for more investment ideas beyond Pluxee?
Once you have formed a view on Pluxee, it can help to compare that thesis with other companies that share similar qualities, whether you care most about value, balance sheet strength or income visibility. The Simply Wall St Screener lets you filter for those traits directly so you can build a shortlist that actually fits your plan rather than scrolling through tickers at random.
- If you want potential mispricing with quality fundamentals, start by scanning a curated set of 204 high quality undervalued stocks that pair earnings power with balance sheet discipline.
- If capital preservation and financial resilience matter most, focus on companies that show up in the list of solid balance sheet and fundamentals (199 results) to frame your watchlist around stronger financial footing.
- If you are hunting for opportunities that the market may not be paying close attention to yet, filter through a hand picked pool of 614 high quality undiscovered gems that combine under-the-radar profiles with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com