


AECOM (ACM) Stock May Be Undervalued Despite The Rail Leadership Appointment
AECOM has seen its share price fall sharply in recent years, yet the latest bounce raises a fresh question about whether today’s valuation still lines up with the earnings the business is generating. With the stock trying to find its footing after a steep slide, the key issue for you is how much of AECOM’s profit power is already reflected in the current price.
- Over the past year the share price has declined 52.1%, which puts the focus squarely on whether the earnings multiple now attached to AECOM is sending a different signal from the one embedded in that drawdown.
- The appointment of Andrea Green to lead the UK and Europe rail business may support expectations for future project activity and earnings quality in AECOM’s rail segment, especially as the company positions itself around long term infrastructure programs in that region.
- Your read on AECOM is one view; the desks covering it have another. See what analysts think AECOM's shares could be worth.
The issue now is whether AECOM’s current share price is adequately justified by its earnings profile when set against the Fair Ratio benchmark.
If you want to test the same earnings question you are asking of AECOM against a wider field of potential ideas, take a look at 33 high quality undervalued stocks
Does AECOM Look Undervalued on Earnings?
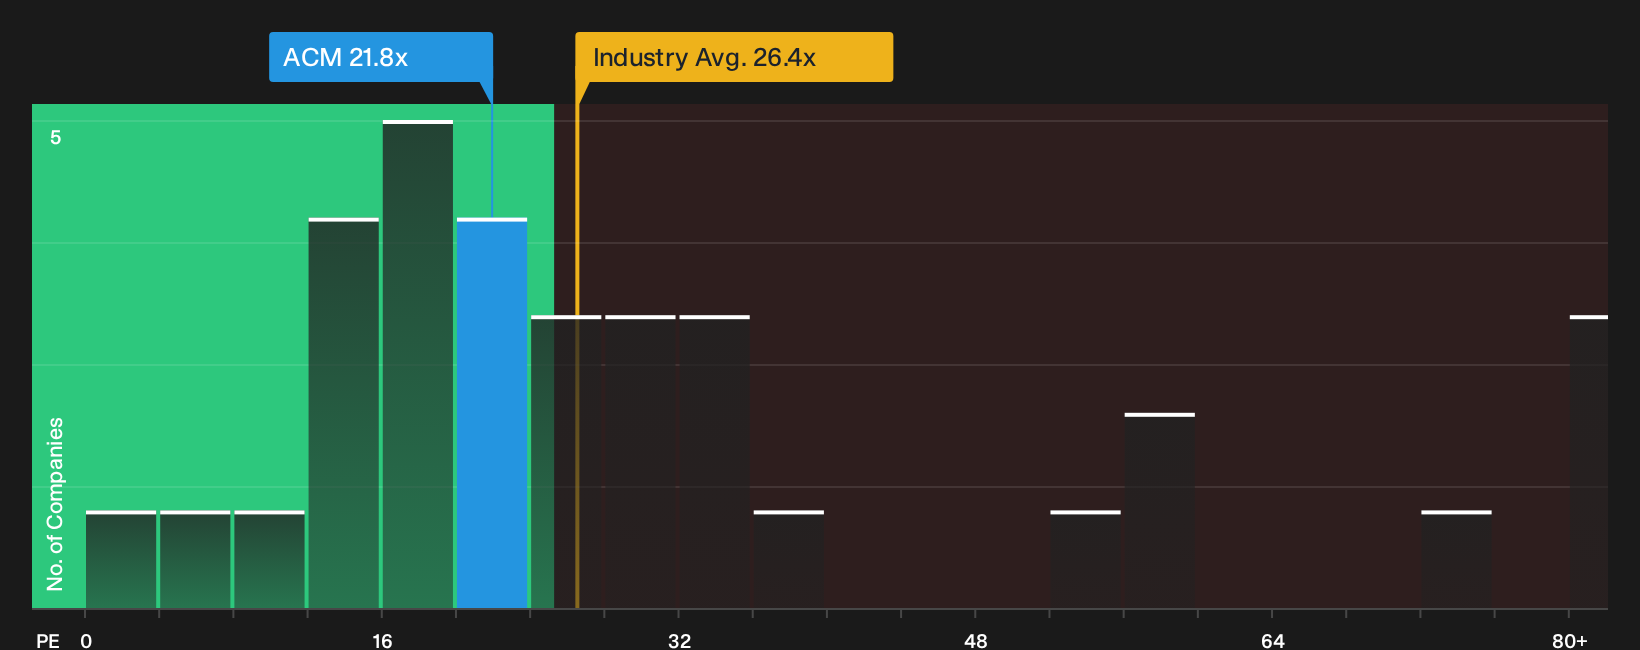
The P/E ratio is a useful lens for AECOM because earnings are a central driver for how investors typically assess established infrastructure and engineering groups. AECOM trades on a P/E of 21.8x, which is below the Construction industry average of 26.4x but above the peer group average of 18.7x, so the stock is priced between broader sector optimism and closer listed rivals.
The Fair Ratio, which reflects what investors might usually pay for AECOM given its risk profile, profitability and size, sits above the current 21.8x level, so the shares screen as undervalued on this framework. Because Andrea Green’s appointment targets rail opportunities in the UK and Europe, the multiple suggests the market is not fully pricing in the earnings that such long term project work could support if it progresses as planned. For anyone tracking how far sentiment has swung after the past year’s price decline, this P/E gap provides a structured way to judge whether today’s valuation still leaves room for a rerating relative to AECOM’s earnings power. Explore the numbers behind AECOM's P/E valuation.
The AECOM Narrative: What Would Justify Today's Price?
AECOM’s Simply Wall St Narratives pick up where the P/E puzzle leaves off and explain which specific paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price. Instead of a single ratio or model output, Narratives describe the future assumptions behind those numbers so you can follow whether that story is actually unfolding on AECOM's Community page.
One of the top community narratives on AECOM: 30% undervalued
"AECOM's Q3 tells a story of two businesses at once, a headline quarter hit by a $337 million project charge..."
Discover why this Narrative puts AECOM at 30% undervalued.
AECOM’s valuation still leaves one key piece off the table
You have a view on what AECOM looks like today, yet professional analysts have already mapped out where they expect this business to be a few years from now. Explore where analysts expect AECOM to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com