


What Valneva Doubters Saw Before The Drop
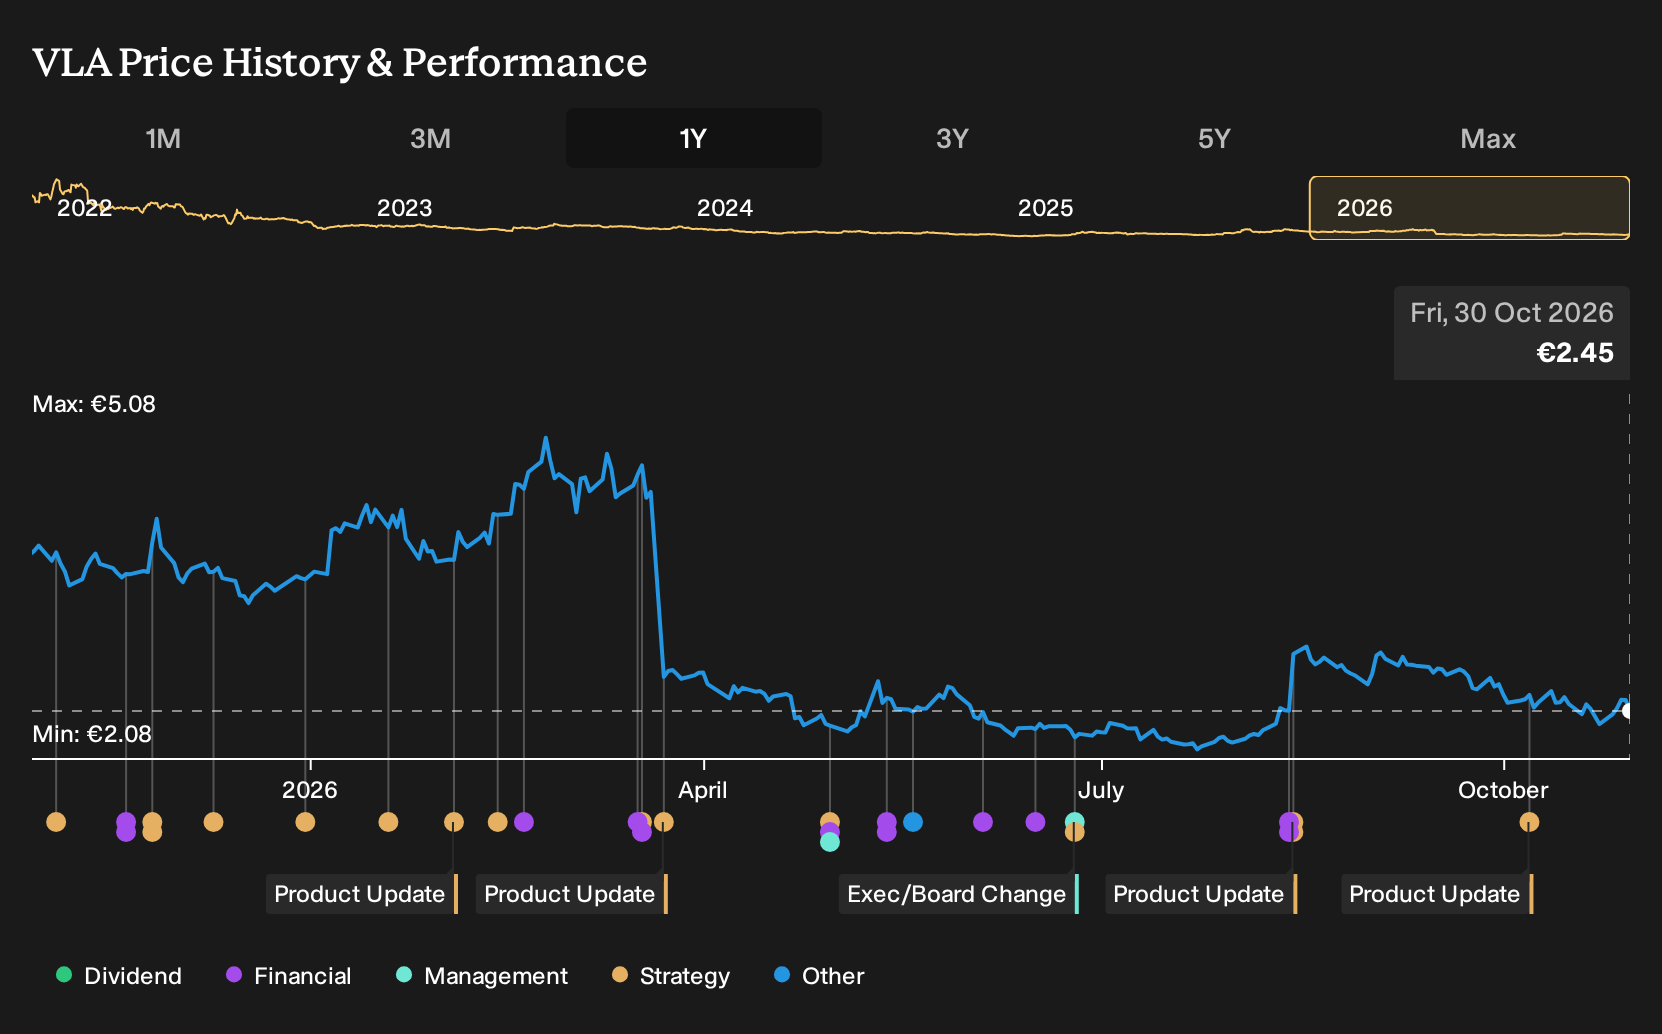
Valneva’s latest quarterly report landed in August 2026 with a harsh mix of lower revenue and a much weaker net margin, and it forced shareholders to confront what the past year had really delivered. Holding Valneva over the past year would have meant a 39.3% loss, including dividends. If you had put money in on 30 October 2025, how should this gap between earlier optimism and today’s profitability setback shape expectations for the next phase of its vaccine pipeline?
If the move has made Valneva harder to judge, start where the gap is still open and scan 204 high quality undervalued stocks.
The Two Valneva Stories Investors Had To Weigh
The shares cost €3.99 at the start of the period, and anyone looking at Valneva then had to choose which story felt more convincing.
On the optimistic side, the bull Narrative pointed to a Fair Value of €6.51, a notional future price if its assumptions played out, built on revenue growth of 22.3% a year and profit margins eventually reaching 29.3%.
The bear Narrative anchored to a Fair Value of €3.75 and assumed a more cautious path, with revenue increasing 9.2% annually and profitability only converging toward a 7.9% margin while relying on a narrow vaccine portfolio.
What The Results Changed For Valneva
The clearest new fact for Valneva was the earnings line. Net income excluding extra items moved from a loss of €11.586 million in Q2 2025 to a deeper loss of €31.203 million in Q2 2026, and the net margin weakened from 24.0% negative to 89.3% negative. That shift challenged the optimistic profitability path and pointed toward a more cautious case.
The takeaway is simple. When a thesis leans on future margin repair, track the direction of current net margin each quarter and compare it directly with the earlier claim, not with the share price.
What Valneva’s Drop Is Asking You To Believe
Valneva now trades at €2.45, well below where the past year started and below where the selected bullish Narrative places its Fair Value. That view leans heavily on what its vaccine programs and partnerships could deliver rather than what the latest income statement shows.
The argument turns on Lyme, travel and outbreak vaccines, and efficiency gains offsetting clinical, regulatory and demand risks. For the fall to look like an opportunity rather than a warning, a buyer today would need to believe the Lyme franchise and broader pipeline can eventually justify that more optimistic Narrative.
"Key Takeaways: Leading vaccine programs and strategic partnerships are set to expand market reach, supporting sustainable growth through innovative, in-demand preventative healthcare solutions. Operational efficiency gains and a robust development pipeline position the company for diversified long-term growth and improved profitability."
The price and this Narrative do not agree. → Uncover what this Narrative says Valneva is actually worth
Before The Next Story Makes Headlines
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 34% below our estimate - deepens its nutrition range while pushing new products through a vast retail network.
- Company 2 - 45% below our estimate - applies data and AI tools to tighten underwriting and claims costs in soft markets.
- Company 3 - 20% below our estimate - widens surgeon adoption of antibiotic-eluting bone grafts across infection driven orthopedic procedures.
Those are three of them. See the full list of 199 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com