


CVB Financial (CVBF) Could Be 13% Below Fair Value On Strong Q3 Earnings
CVB Financial (CVBF) just posted third quarter results that paired higher net interest income and net income with very low net charge offs, along with the completion of a US$22.58 million share repurchase.
Recent trading tells a mixed story for CVB Financial. The share price has climbed strongly year to date with a 20.94% share price return and a 27.79% total shareholder return over 1 year. However, short term momentum has faded slightly, with modest declines over the past week and quarter as investors digest the earnings jump, very low net charge offs and the completed buyback at a US$22.58 share price.
Scan how CVB Financial compares with other banks focused on earnings quality and balance sheet strength using the hand picked 29 resilient stocks with low risk scores.After a strong run and a US$22.58 share price, CVB Financial still trades below both internal value estimates and analyst targets. Is that discount a margin of safety, or a warning the market sees something you do not?
Most Popular Narrative: 13% Undervalued
CVB Financial is priced at $22.58 against a narrative fair value of $26, suggesting the market is not fully crediting its merger and income story.
Successful integration of Heritage Commerce, which lifted CVB Financial’s assets to about US$21.2b along with US$3.15b of loans and US$4.75b of deposits, creates a larger, statewide franchise that can support higher revenue and earnings from a broader California customer base.
Management’s plan for the Heritage merger to contribute at least 13% EPS accretion in 2027, with targeted returns of 1.50% on average assets and 17% on tangible common equity, points to potential uplift in earnings and capital efficiency if these goals are reached.
See why 11 investors see CVB Financial as 13% undervalued.
Result: Fair Value of $26 (UNDERVALUED)
Still, the CVB Financial story depends heavily on a clean Heritage integration and on the thinner tangible common equity ratio not constraining capital returns or growth options.
Find out about the key risks to this CVB Financial narrative.
Another View: CVB Financial Through The P/E Lens
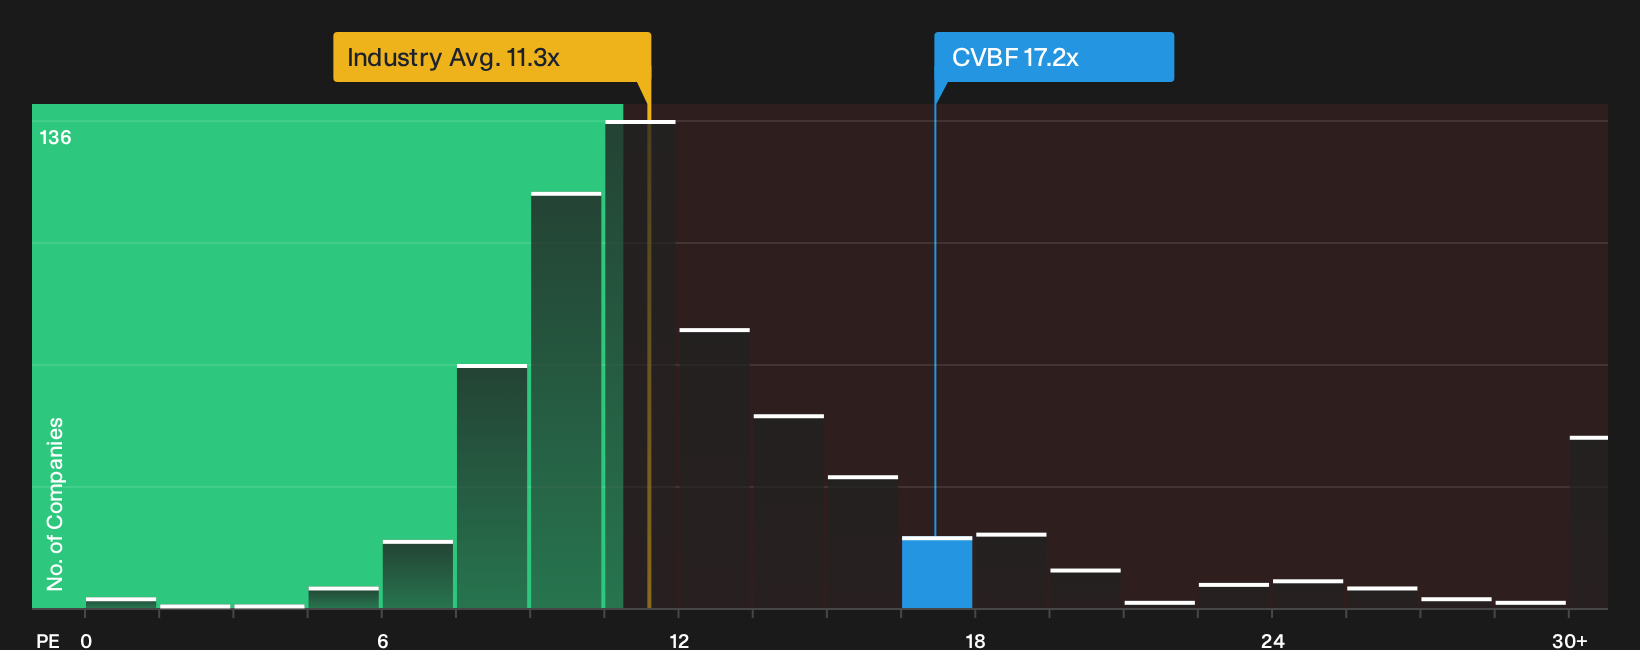
The DCF workup suggests CVB Financial trades at a discount to future cash flows, yet the P/E ratio tells a tougher story. At 17.2x earnings, the stock is priced well above the US Banks industry on 11.3x, above peer averages at 11.1x, and even above a fair ratio of 14.8x that the market could move towards over time. That gap points to valuation risk rather than a clear bargain. This raises the question of how much weight to put on earnings multiples compared with cash flow models.
For a closer look at how this earnings based view stacks up against other banks, and how the numbers line up with broader valuation work, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mix of optimism and caution around CVB Financial is clear. Consider reviewing the numbers yourself and pressure testing the narrative from both sides using 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CVB Financial?
You have already done the hard work by analyzing CVB Financial. Now widen your opportunity set with a few focused ideas that could refresh your watchlist.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive valuations using 33 high quality undervalued stocks.
- Strengthen your income playbook by reviewing businesses that offer higher yields and aim for staying power through 5 dividend fortresses.
- Prioritize resilience by filtering for companies with sturdy finances and cleaner balance sheets via list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com