


Learn Why The Bull Case For Selective Insurance Group Stock Could Change Following Earnings Beat
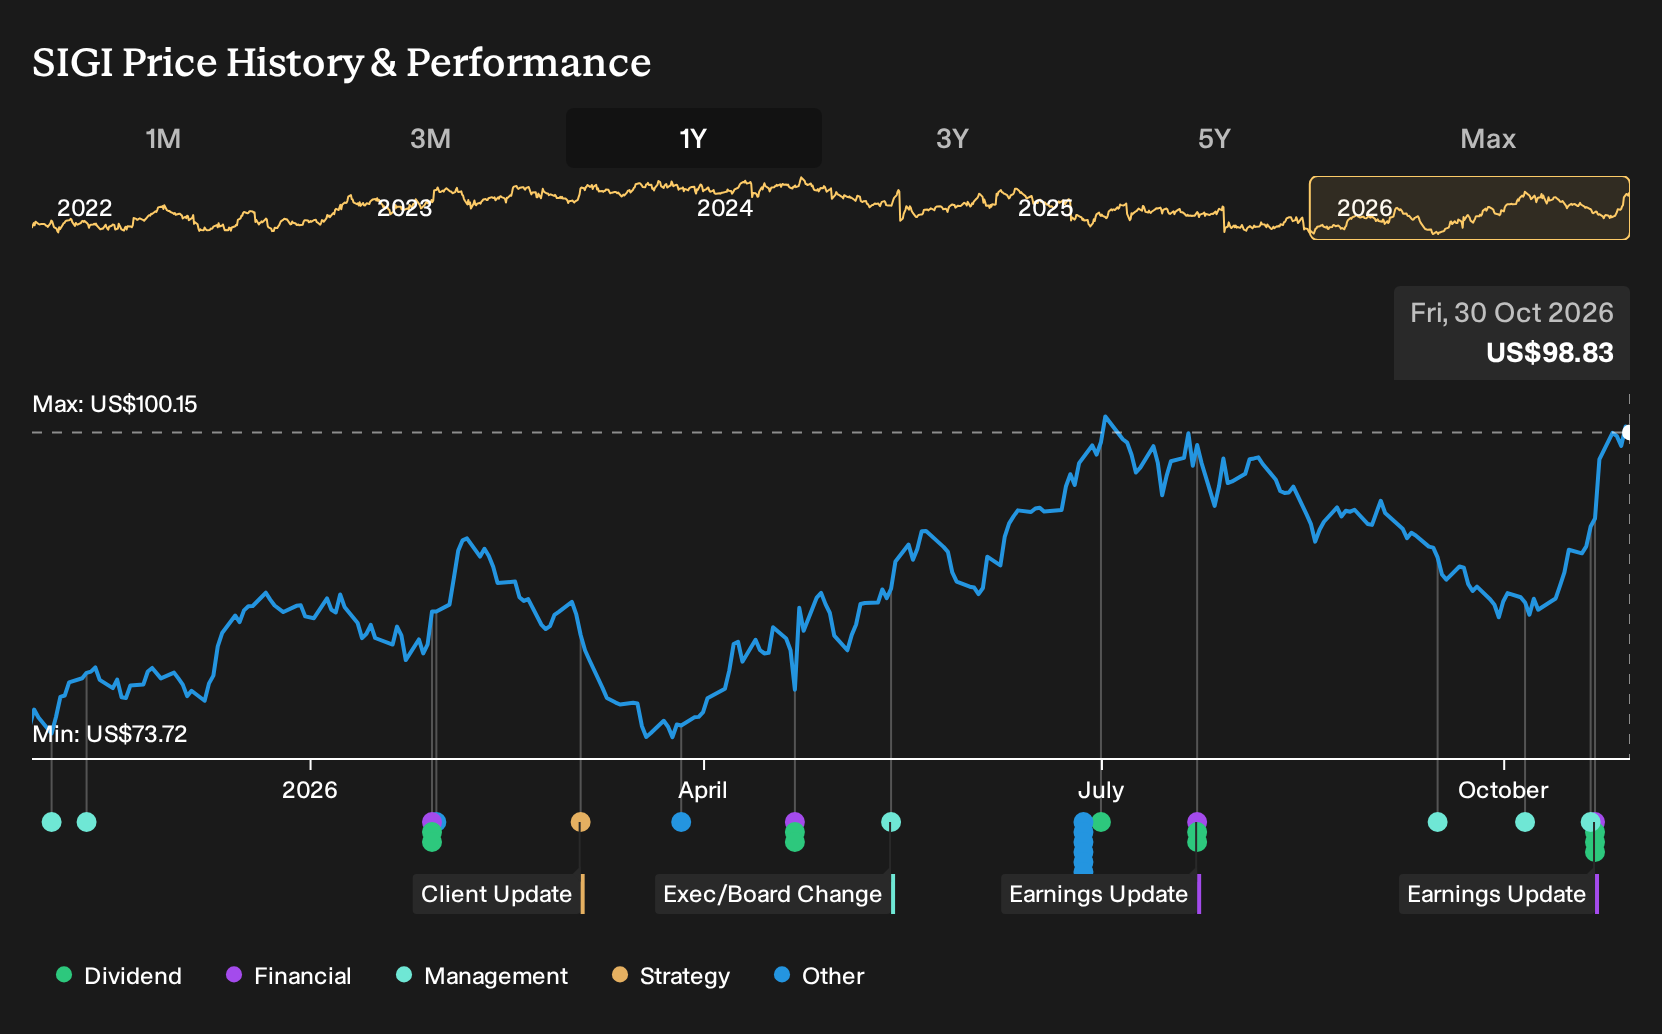
- Selective Insurance Group reported third quarter 2026 revenue of US$1,326.3 million with net income of US$128.7 million and diluted EPS from continuing operations of US$2.11, alongside a 12% lift in its common dividend and a new US$200 million share repurchase authorization.
- The mix of higher earnings per share, increased cash returns through a richer dividend, and a buyback program reflects management’s focus on capital efficiency and disciplined capital deployment while operating with relatively stable top line trends.
- We will look at how Selective Insurance Group's higher dividend reshapes the investment narrative and interacts with its existing profitability focus.
Scan how Selective Insurance Group's mix of higher earnings per share, richer dividends, and fresh buybacks compares with 5 dividend fortresses in similar businesses targeting reliable cash returns.
Selective Insurance Group Investment Narrative Recap
To stay invested in Selective Insurance Group, you need to believe the insurer can keep underwriting disciplined business while casualty claim severities and social inflation remain a pressure point. The latest quarter shows earnings per share from continuing operations of US$2.11, so profitability is still there even with relatively flat revenue. The near term catalyst remains execution on re underwriting weaker books without letting premiums stagnate.
The biggest risk stays the same. If higher loss trends in general liability and commercial auto keep feeding into adverse reserve development, earnings could stay volatile. Aggressive pricing and tighter underwriting have already been linked to lower Standard Commercial Lines premiums, so persistent volume pressure would raise questions about Selective Insurance Group’s ability to balance growth and margin protection.
The 12% increase in the common dividend to US$0.48 per share is the announcement that ties closest to the current story. It sits alongside net income of US$128.7 million for the quarter and nine month EPS from continuing operations of US$5.80, which gives the higher payout some earnings context. For an investor, the signal is about cash returns funded by an insurance operation that is still profitable.
That higher dividend also interacts directly with today’s catalysts. Cash distributions can be attractive when combined with ongoing investment in data analytics, digital claims tools, and a growing Excess and Surplus segment. The trade off is that meaningful capital return only works if Selective Insurance Group keeps managing social inflation risk, maintains combined ratios that support underwriting income, and does not let stricter underwriting erode the premium base more than expected.
What Analysts Are Building Into the Selective Insurance Group Story
Analysts sketch a fairly steady revenue path for Selective Insurance Group, with expectations that sales stay broadly flat over the next 3 years while profitability edges higher. That forecast pairs a current profit margin of 8.9% with a projected 10.4% margin in 3 years, so the focus shifts from chasing top line expansion to trying to squeeze more earnings out of roughly the same premium base. For you as an investor, the key question is whether that tighter underwriting and expense discipline can coexist with the casualty loss pressures that are already creating reserve noise.
The earnings bridge in the consensus numbers is straightforward. Analysts cite earnings today of about US$488.4 million and expect the figure to reach US$575.2 million by around 2029, which is a move of roughly US$86.8 million. That outlook implies earnings per share of US$9.40 and assumes the share count falls about 1.39% a year over the next 3 years, consistent with the newly authorized repurchase plan. The thesis being built is that a combination of margin improvement, share count reduction, and continued contribution from net investment income can support that higher earnings base even if revenue does not grow quickly.
The valuation framing around these estimates is clear on the numbers. Consensus calls for 2029 revenue of about US$5.5b and earnings of US$575.2 million. This in turn underpins a price target of US$101.86 using a P/E of 12.5x on those projected earnings. That multiple sits above the 10.4x P/E cited today for Selective Insurance Group and above the current 10.7x P/E mentioned for the wider US insurance group, so analysts are effectively assuming a modest premium to the sector on the back of higher margins. There is still a range of opinion, with the bullish target at US$115 and the low end at US$80, which gives you a sense of how much disagreement exists around casualty trends, reserve outcomes, and the durability of the margin plan.
Selective Insurance Group's narrative projects US$5.5b revenue and US$575.2 million earnings by 2029. This requires fairly flat yearly revenue trends and an earnings increase of about US$86.8 million from current earnings of US$488.4 million.
Uncover why Selective Insurance Group's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$101.86 and US$201.51, so one view sits only slightly above the current analyst target while another points to far richer upside. You see that spread before factoring in fresh catalysts such as higher dividends, buybacks, and leadership changes at Selective Insurance Group. Investor opinions can differ widely, so explore several of these community viewpoints before leaning on any single narrative.
Explore another Selective Insurance Group fair value estimate, including one that suggests potential upside of as much as 104% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Selective Insurance Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Selective Insurance Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Selective Insurance Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Selective Insurance Group?
If the Selective Insurance Group story has sharpened your thinking but you want a wider opportunity set, consider looking at other high quality businesses that match your preferred balance of income, resilience, and upside potential.
- For investors who care most about dependable income, start with a shortlist of income-focused companies through 5 dividend fortresses that put cash returns front and center.
- If capital preservation and steadier risk profiles matter more to you, narrow the field using 29 resilient stocks with low risk scores so you are concentrating on businesses with stronger resilience scores.
- When you are hunting for underfollowed ideas with solid fundamentals, widen your search with 19 high quality undiscovered gems that might not yet be on most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com