


Ultra Clean Holdings (UCTT) Returned To Profit, Is It A Bargain Or Fully Priced?
Why Ultra Clean Holdings Has Caught Investor Attention
Ultra Clean Holdings (UCTT) has drawn fresh interest after reporting third quarter results that showed revenue of US$759 million and net income of US$39.1 million, compared with a loss a year earlier.
Ultra Clean Holdings has seen sharp swings around these results, with the share price falling 9.1% in the last session and down 31.6% over 30 days. The stock is still showing an 82% year to date share price return and a 1 year total shareholder return of 81.4%, which indicates notable underlying momentum despite the recent volatility.
Scan other potential beneficiaries of the same semiconductor equipment cycle by reviewing our curated list of 54 AI infrastructure stocks alongside Ultra Clean Holdings.
Ultra Clean Holdings has swung from losses to profit while the share price has slipped hard from recent highs. With analysts’ fair value targets far above US$49.71, what might be considered a reasonable valuation range?
Most Popular Narrative: 63% Undervalued
Analysts following Ultra Clean Holdings see a large gap between their US$132.83 fair value estimate and the US$49.71 last close, and they tie that difference to a specific execution plan rather than a vague sentiment shift.
The main thing that has to go right is Ultra Clean Holdings successfully scaling its global manufacturing footprint and UCT 3.0 co-innovation model so that higher industry wafer fab equipment spending and new fab ramps translate into sustainable revenue and margin gains.
See why 22 investors see Ultra Clean Holdings as 63% undervalued.
Result: Fair Value of $132.83 (UNDERVALUED)
Still, if Ultra Clean Holdings fails to turn negative operating cash flow around, or its services expansion falls short of expectations, this upbeat narrative could quickly look stretched.
Find out about the key risks to this Ultra Clean Holdings narrative.
Another View: What Ultra Clean Holdings' P/E Is Saying
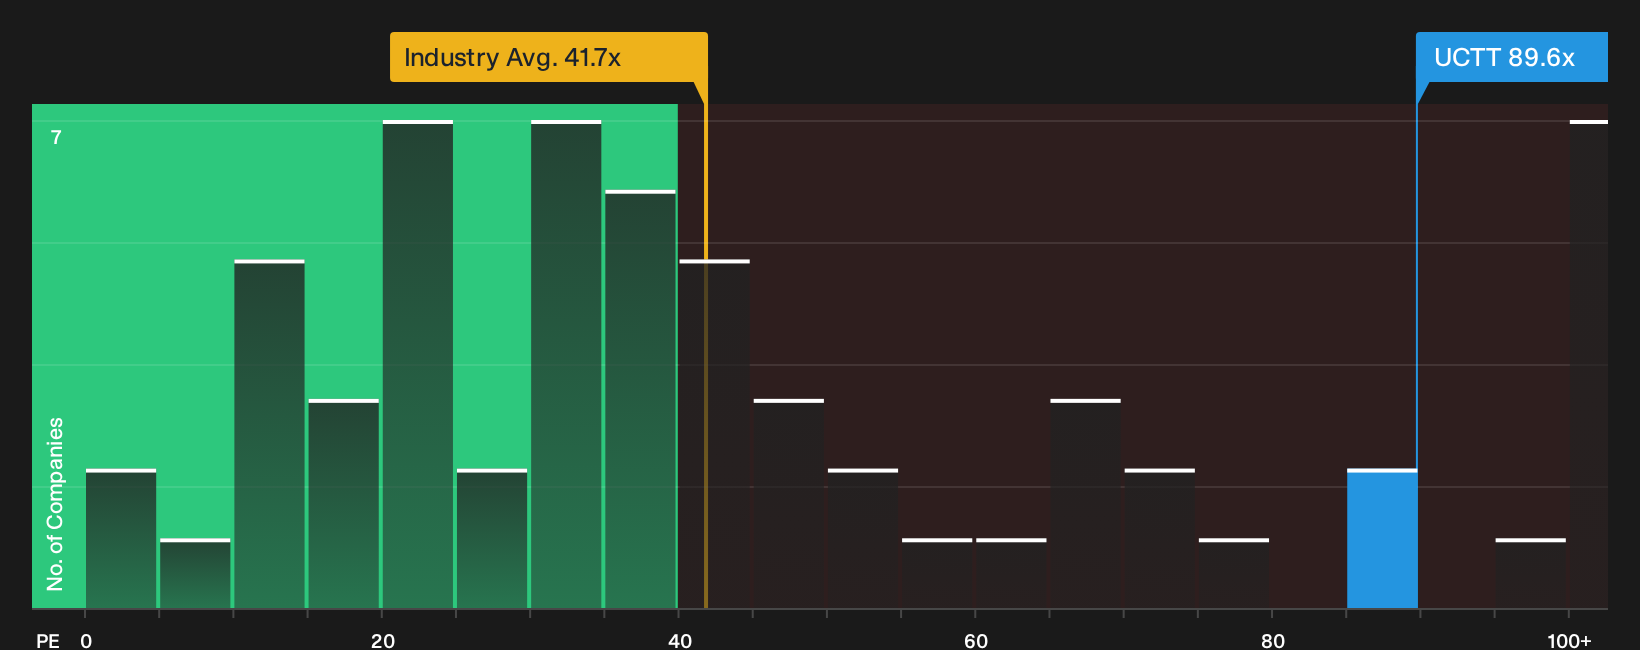
Ultra Clean Holdings screens very differently when you focus on the current P/E ratio of 89.6x. That is roughly double the US Semiconductor industry average of 41.7x and also above the stock’s fair ratio of 44.4x, which points to meaningful valuation risk if sentiment cools.
For readers who prefer to anchor on current trading multiples rather than long range narratives, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed views on Ultra Clean Holdings after these results and valuation gaps are clear. Move fast, review the key data, and weigh both the upside and the concerns with the help of 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Ultra Clean Holdings?
If Ultra Clean Holdings has sharpened your focus, do not stop there. Broader idea hunting with a disciplined stock screener can help you build your watchlist in a thoughtful way.
Use the Simply Wall St tools to look for opportunities that fit your approach before they become widely followed.
- Target potential mispricings by scanning a curated set of 33 high quality undervalued stocks that combine quality metrics with discounted valuations.
- Strengthen capital preservation by reviewing a list of solid balance sheet and fundamentals (24 results) so you are not relying on hope when conditions get tougher.
- Explore a focused pool of 19 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com