


How Strong Q3 Earnings At Sanoma Oyj Stock Have Changed Its Investment Story
- Sanoma Oyj reported third quarter 2026 sales of €518.9 million and net income of €126 million, with basic EPS from continuing operations at €0.78, and narrowed its 2026 net sales guidance range to €1.30 billion to €1.32 billion.
- The earnings release showed materially higher net income and earnings per share than a year earlier, and Sanoma Oyj continues to build out its curriculum driven K12 learning operations through acquisitions in Spain and Poland.
- We will now look at how Sanoma Oyj's tighter 2026 sales guidance could reshape the investment narrative built around its K12 expansion.
Scan how Sanoma Oyj's tighter guidance and K12 focus compare with peers by reviewing our hand picked list of list of solid balance sheet and fundamentals (199 results).
Sanoma Oyj Investment Narrative Recap
For Sanoma Oyj, the core belief as a shareholder is simple. You need to think the curriculum driven K12 learning arm can keep doing the heavy lifting while Media Finland remains resilient enough despite a soft ad market. The latest quarter showed strong earnings, and the tighter €1.30b to €1.32b sales range does not radically change that near term story.
The short term swing factor still sits in execution on K12 acquisitions in Spain and Poland, and in keeping Learning margins healthy while debt remains elevated. The biggest risk remains pressure on Finnish advertising and any slip in deleveraging progress, which could limit flexibility if trading conditions turn tougher.
The most relevant fresh data point is the third quarter 2026 report itself. Sanoma Oyj booked €518.9 million of sales with €126 million of net income and basic EPS from continuing operations of €0.78. Over the first nine months, revenue was €1,074.7 million and net income €134.7 million, so a large part of this year’s profit came through in the latest quarter.
That pattern matters for your catalyst map. A strong earnings print alongside only slightly adjusted full year net sales guidance suggests management is keeping expectations anchored while focusing on K12 expansion and deleveraging. The operational question for investors is whether this level of profitability proves repeatable while the ad market in Finland stays soft and integration of new learning assets continues.
Sanoma Oyj's current analyst narrative points to revenues of €1.4b and earnings of €141.5 million by 2029, based on forecast annual top line growth of 2.8% and a projected rise in earnings of about €124 million from €17.2 million today.
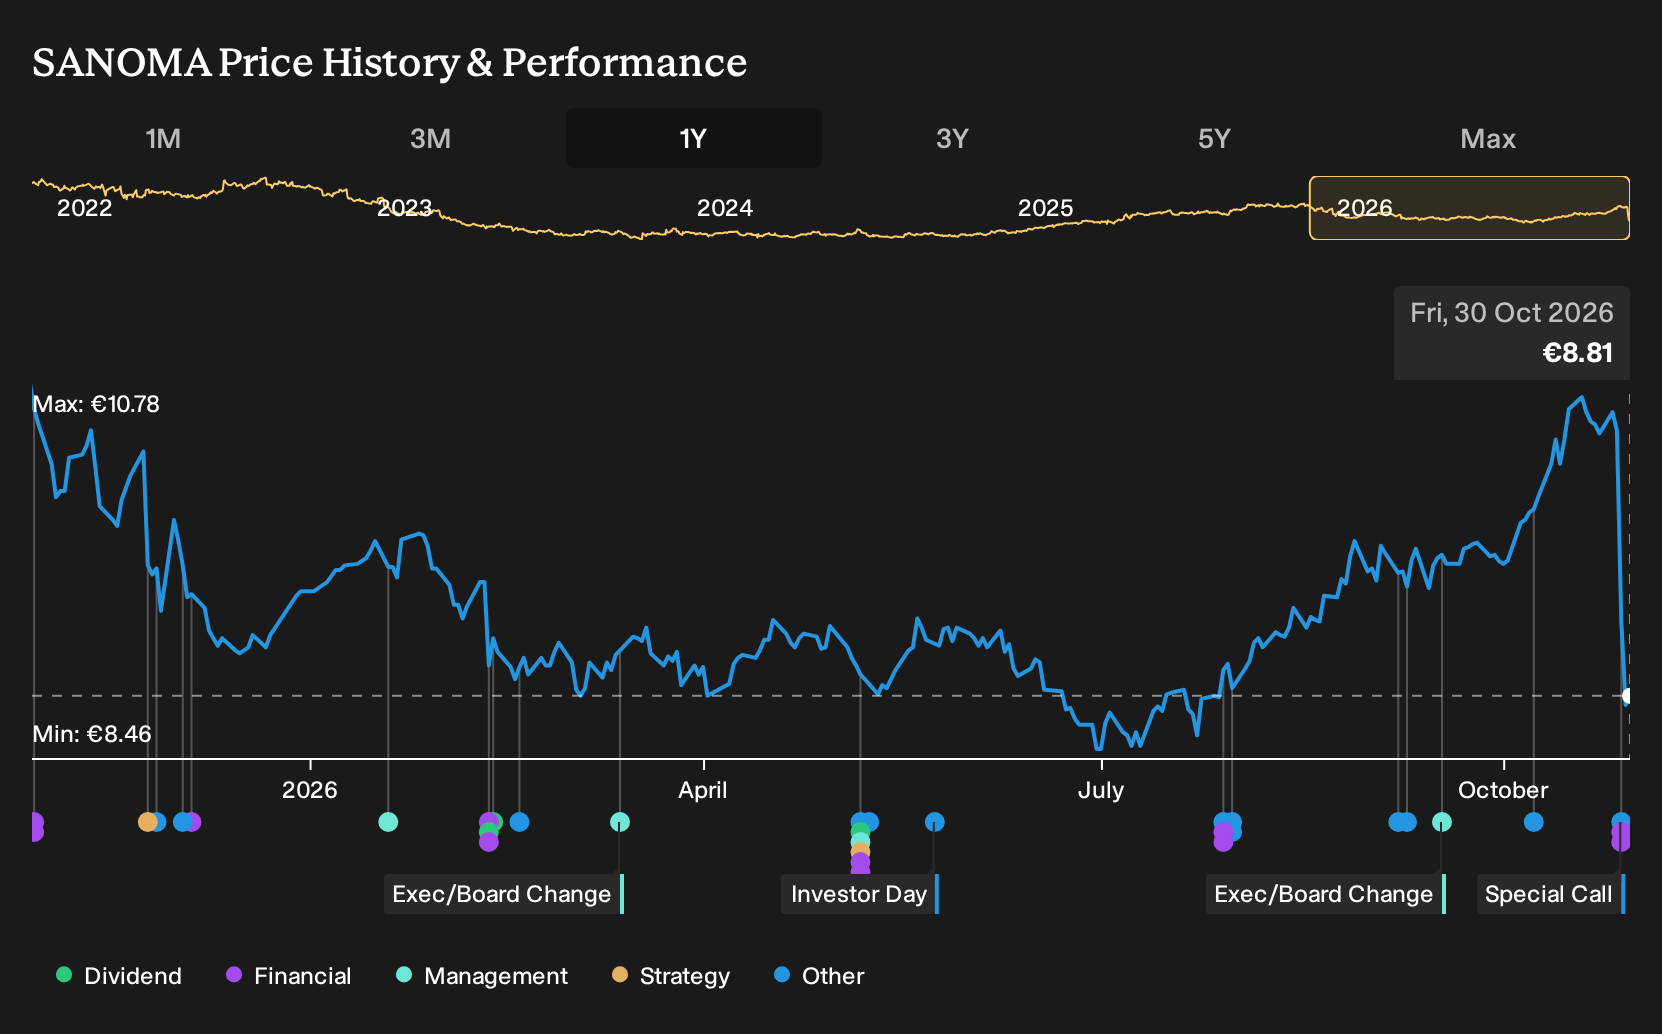
Uncover why Sanoma Oyj's fair value indicates a 40% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster tightly between €12.34 and about €12.57, so private investors currently see Sanoma Oyj in a very narrow price band. Those views were set before the latest earnings jump and the tighter sales guidance, so reassess them against the risks around advertising softness and the catalysts in K12 learning before deciding which camp you lean toward.
Explore another Sanoma Oyj fair value estimate, including one that suggests as much as 43% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sanoma Oyj research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sanoma Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sanoma Oyj's overall financial health at a glance.
Looking for more investment ideas beyond Sanoma Oyj?
If you want to pressure test your view on Sanoma Oyj against a wider watchlist, broaden your research universe with a few targeted stock shortlists built around quality, value and resilience.
- Focus on resilient balance sheets and robust fundamentals by scanning our list of solid balance sheet and fundamentals (199 results), which can help you stress test ideas against stronger financial structures.
- If value is your priority, compare Sanoma Oyj with 204 high quality undervalued stocks, which blends quality metrics with pricing that currently screens as attractive on several checks.
- For those who care most about stability and capital preservation, widen your radar to 218 resilient stocks with low risk scores, which scores well on our risk filters and may complement higher volatility positions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com