


Floor & Decor Holdings (FND) After Q3 Results Is The Softer Outlook Already Priced In
Q3 2026 earnings put Floor & Decor in focus
Floor & Decor Holdings (FND) just reported third quarter 2026 results that paired higher sales and net income with cautious commentary on demand and a slower store expansion plan for 2027.
Sales for the quarter were US$1,214.56 million, with net income of US$64.82 million and diluted earnings per share from continuing operations of US$0.61, based on management’s latest filing.
Floor & Decor’s share price reaction has been rough, with the stock dropping 5.46% on the day of the results and sitting around US$47.59. This leaves the 90 day share price return down 16.63% and the 5 year total shareholder return down 64.30% as investors reassess both growth potential and housing related risk.
Scan how other flooring and home-improvement retailers are priced and growing by comparing Floor & Decor against a curated set of 33 high quality undervalued stocks.
Floor & Decor appears to be a solid operator on the surface, with rising earnings and steady store openings. However, a 5-year share price decline of 64.30% tells a different story. Is the current valuation really giving you fair odds?
Most Popular Narrative: 16% Undervalued
Floor & Decor is trading at $47.59 against a widely followed fair value estimate of about $56.45, which frames the current pullback as a discount that only looks reasonable if you doubt the long term store economics and cash generation that analysts are modelling in.
The evolution toward a more capital efficient footprint, with average new store costs declining from roughly US$11.7 million in 2023 to about US$10.2 million for the 2025 class and an expected US$7.5 to $8.0 million in 2026, together with infill locations in denser markets, creates room for higher returns on invested capital and more free cash flow that can support earnings growth.
See why 13 investors see Floor & Decor Holdings as 16% undervalued.
Result: Fair Value of $56.45 (UNDERVALUED)
Still, the Floor & Decor narrative can crack if weak comps persist while new stores keep opening, or if prolonged vinyl and laminate pressure reduces gross margin.
Find out about the key risks to this Floor & Decor Holdings narrative.
Another View: What Floor & Decor’s P/E Is Telling You
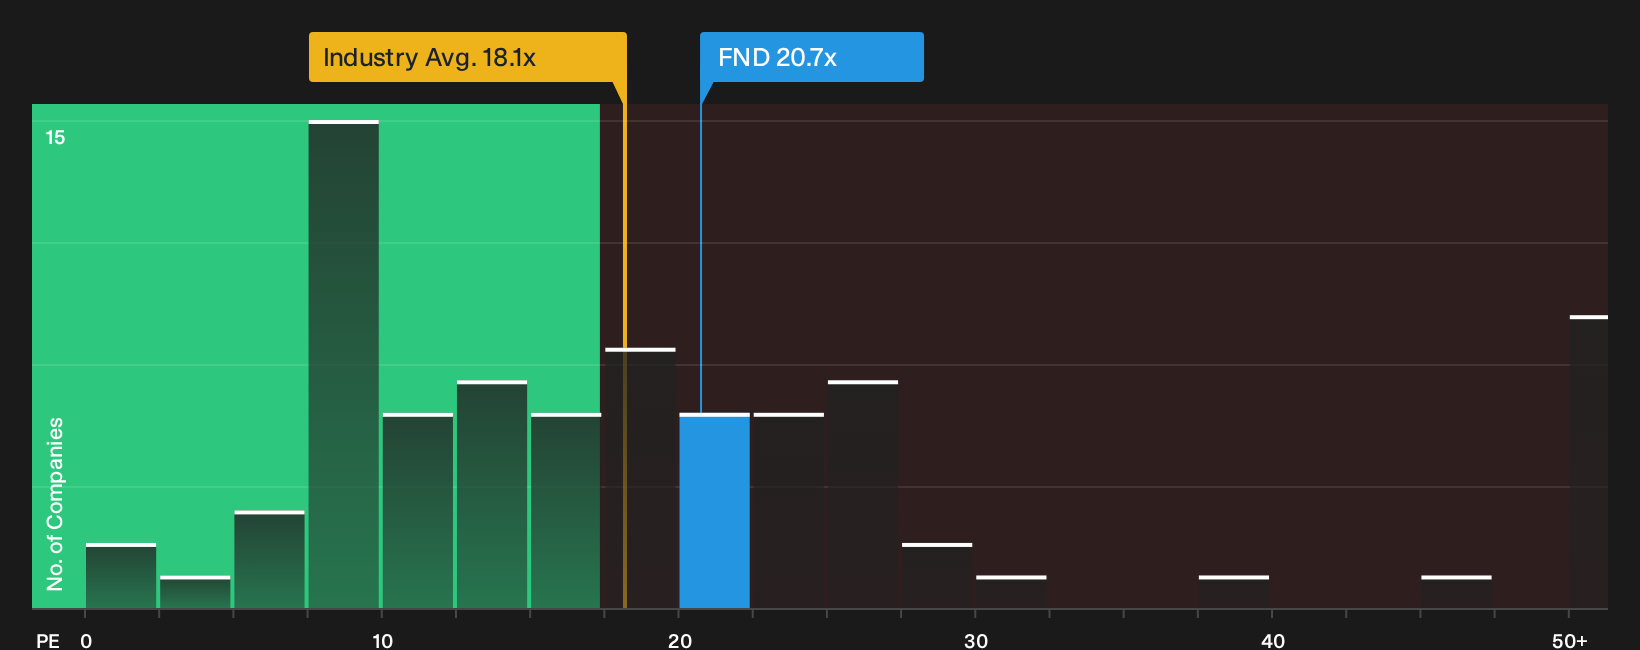
The fair value narrative around Floor & Decor leans on future cash generation, yet today’s price tells a different story. The stock trades on a P/E of 20.7x, while the fair ratio is 12.3x, the US Specialty Retail average is 18.1x, and close peers sit near 11.9x. That premium narrows the safety margin if earnings or sentiment wobble. How comfortable are you with paying a higher multiple for this thesis to play out?
See what the numbers say about this price in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about the Floor & Decor story after these numbers. Review the full picture yourself, then weigh both sides of the ledger with 1 key reward and 1 important warning sign
Looking for more investment ideas beyond Floor & Decor?
If Floor & Decor has you rethinking your portfolio mix, consider broadening your approach with a few focused stock lists to help you evaluate different risk and reward tradeoffs.
- Target stronger downside protection by reviewing a group of companies screened as 29 resilient stocks with low risk scores that may help steady overall portfolio volatility.
- Explore income potential and assess which payouts appear more consistent over time with a curated set of 5 dividend fortresses tailored for yield focused investors.
- Search for quality at a discount by scanning a hand picked pool of 19 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com