


3 AI Infrastructure Stocks Riding Data Center Cooling And Power Demand
AI enthusiasm is colliding with doubts about whether mega-cap giants like Google and Meta are spending too much for too little payoff, and that shift is quietly redirecting attention toward the under-the-radar infrastructure behind the servers and chips. When the spotlight moves, pricing and expectations can reset fast, which can create both opportunity and risk for investors watching AI-linked buildouts. This article examines that tension and profiles 3 stocks that appear particularly exposed to this news-driven setup.
The three stocks below are just a starting sample, as the full screen surfaced 63 more companies with equally compelling stories around AI buildouts that are not covered in this article.
If you want to identify potential AI infrastructure enablers and analyze them side by side on fundamentals, valuation, and risk, head straight into the AI Infrastructure Enablers Outside Mega-Cap Hyperscalers screener.
Modine Manufacturing (MOD)
Modine Manufacturing plugs into the AI infrastructure story through the plumbing of it all, supplying thermal and cooling hardware that keeps dense compute racks running and power equipment protected. This is why its push into data center solutions has drawn fresh investor attention.
Modine Manufacturing designs, engineers, tests, manufactures, and sells thermal management systems for data centers, buildings, vehicles, and industrial equipment, with Performance Technologies generating about US$1.1b of the roughly US$2.3b Segment Adjustment revenue, and the group valued at about US$6.9b by market cap.
"The accelerating build out of data centers and the need for next generation cooling solutions are driving demand for Modine Manufacturing’s products, with management targeting data center revenue of about US$2b by fiscal 2028 after delivering US$1.1b in fiscal 2026 and guiding to 60% to 80% Data Center sales growth in fiscal 2027, which points to a significant revenue growth engine and potential operating leverage as new capacity fills."
How that growth translates into long run earnings power will largely hinge on one unseen pressure that could shift margins more than many expect.
That margin pressure is the crux of the story, and the full narrative for Modine Manufacturing shows how Modine Manufacturing could balance cooling demand, pricing power, and execution risk.

Shenzhen KSTAR Science and Technology (SZSE:002518)
Shenzhen KSTAR Science and Technology supplies uninterruptible power systems, data center cooling, modular server rooms, and PV plus storage solutions that keep AI data centers and other critical facilities online. The business is valued at about CN¥14.9b by market cap.
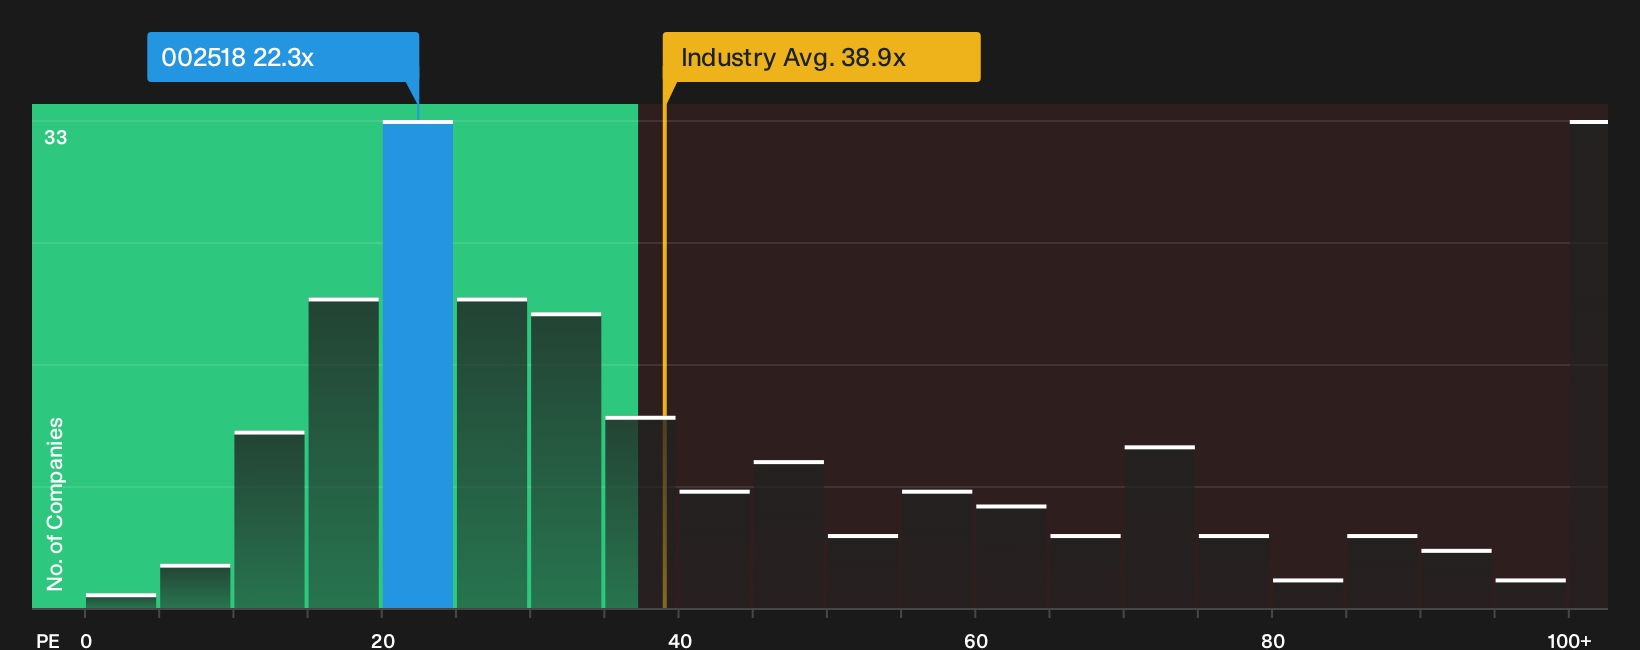
Shenzhen KSTAR Science and Technology is closely aligned with the AI infrastructure theme, with UPS, cooling, and data center hardware tied directly to power reliability for dense compute sites. The combination of its recent earnings momentum and a P/E below the wider Electrical industry may attract investors who believe AI-related capex could influence demand for critical power equipment.
That mix of earnings momentum and a lower P/E invites a closer look. The 4 key rewards and 1 important warning sign could show where Shenzhen KSTAR Science and Technology’s risk and upside really split.
nVent Electric (NVT)
nVent Electric plugs directly into the AI infrastructure theme, supplying the electrical connection, protection, and cooling gear that keeps high power data centers and other critical facilities running safely and reliably.
nVent Electric designs, manufactures, installs, and services electrical connection and protection solutions for data centers, industrial sites, buildings, and energy projects worldwide, and the business is valued at about US$20.4b by market cap.
"Accelerating AI related data center spending, supported by nVent Electric’s roughly $2.5b backlog and guidance that total data center sales are expected to move above $2b in 2026, points to a pipeline of projects that could sustain revenue and support adjusted EPS growth as that backlog converts."
What really moves the story from here is how one less visible swing factor ultimately filters through to returns on those projects.
That swing factor is exactly what the full narrative for nVent Electric unpacks in detail, separating temporary noise from the projects that could influence nVent Electric’s momentum.

Seeking Alternatives Before Momentum Flies
Fresh ideas can move fast. By the time every headline catches up, the best entry points might be dropping away. Scan under the radar for now and act now.
- Spot potential turnaround stories early and track proven balance sheets using the curated list of solid balance sheet and fundamentals (24 results) that filters for strength before the crowd catches on.
- Ride structural trends in minerals by reviewing a focused 16 top copper producer stocks built to surface producers positioned for grid, electrification, and infrastructure themes.
- Zero in on potential compounding machines through a tightly filtered 29 resilient stocks with low risk scores aimed at resilient businesses where risk scores stay contained while momentum builds.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com