


Is Atmos Energy (ATO) Cheap As Its Capex Story Supports Fair Value?
Atmos Energy (ATO) has been drawing fresh attention after its recent share price move, with the gas utility now trading at US$172.41. That shift raises a practical question: What exactly are investors paying for here?
Recent trading tells you a bit more about the mood around Atmos Energy. The 1 month share price return of 9.7% suggests momentum has picked up again, even though the 3 month share price performance dipped slightly. A 5 year total shareholder return of 107.58% points to a long run story that has so far rewarded patient holders.
Spot fresh momentum in Atmos Energy. Then widen your watchlist with a curated set of resilient utilities and infrastructure plays in our 29 resilient stocks with low risk scores.Atmos Energy now trades within sight of analyst targets, yet still shows a sizeable gap to one estimate of fair value. Is the recent burst of enthusiasm running ahead of fundamentals, or is the caution misplaced?
Most Popular Narrative: 7% Undervalued
On the widely followed narrative, Atmos Energy screens as modestly undervalued, with a fair value estimate of $185.55 against the last close at $172.41. That gap puts the focus firmly on whether the growth, capital spending and regulatory story can support that higher assessment.
Major multiyear capital investment programs, including about US$4.2b of fiscal 2026 capex with roughly 87% to 89% directed to safety, reliability and modernization, continue to expand the regulated asset base and support future rate filings that can increase regulated revenue and operating income.
See why 14 investors see Atmos Energy as 7% undervalued.
Result: Fair Value of $185.55 (UNDERVALUED)
Still, the Atmos Energy story can change quickly if the US$4.2b capex plan strains funding, or if the Dallas explosion lawsuit drives higher, less recoverable costs.
Find out about the key risks to this Atmos Energy narrative.
Another View: Atmos Energy Through The P/E Lens
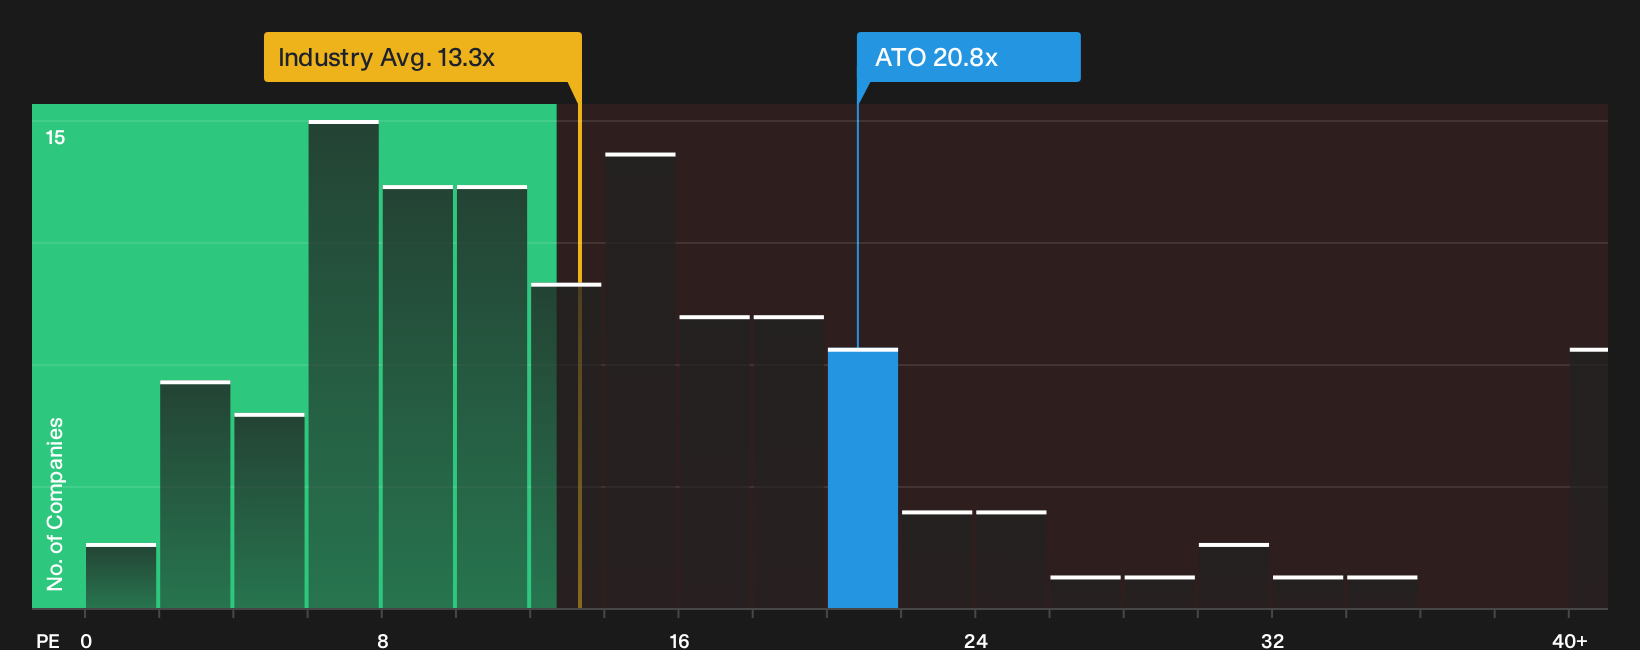
Atmos Energy may look appealing against a fair value estimate, yet the simple P/E check tells a different story. At 20.8x earnings, the stock trades well above the global gas utilities average of 13.3x and the fair ratio of 20.6x. This leaves only a thin margin for error if growth or regulation disappoints.
Investors who rely more on earnings multiples than narrative models might see this gap as a valuation risk rather than a cushion. This is particularly relevant when the peer average P/E sits near 14.4x and offers a cheaper way to access similar sector exposure. It is worth asking which anchor matters more for you: the fair value estimate, or the richer P/E footprint, before deciding how much room is left in the Atmos Energy story.
For a closer look at how the current P/E stacks up against history, peers and an estimated fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Atmos Energy so far. If this tension between potential upside and flagged concerns resonates, move quickly to review the data, pressure test your own thesis, and weigh the 2 key rewards and 2 important warning signs.
Looking for more Atmos Energy style investment ideas?
If Atmos Energy has sharpened your focus on quality, do not stop here. Broaden your opportunity set with a few targeted screens built to surface specific strengths across the market.
- Target sturdier balance sheets by scanning a list of solid balance sheet and fundamentals (24 results) that filters for companies with stronger financial footing and healthier fundamentals.
- Hunt for better value by running through a 33 high quality undervalued stocks that highlights businesses where price and fundamentals look out of sync.
- Prioritize reliable cash returns by checking a 5 dividend fortresses that focuses on companies offering higher yields with supportive financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com