


Corpay (CPAY) Could Be 13% Undervalued Following Q3 Earnings Optimism
Corpay (CPAY) heads into its third quarter earnings release on 4 November with attention on two fronts. The stock reflects past estimate beats, and a recent FX partnership with Newcastle United highlights its cross-border ambitions.
The share price has climbed strongly on a longer view, with a year to date share price return of 33.38% and a 1 year total shareholder return of 54.00%. The latest close at US$400.94 comes after a softer 7 day share price return of 1.84% and a more moderate 90 day share price return of 3.93%. This suggests momentum has cooled a little as investors weigh Corpay’s recent Newcastle United FX agreement and the upcoming third quarter results together.
Scan beyond Corpay and size up other payment and financial infrastructure players with the hand-picked 19 high quality undiscovered gems that share strong fundamentals and potential for a bigger story.
Corpay trades about 13% below the average analyst target and at a far larger modeled intrinsic discount, even after a strong run. Is that caution about the story or an opportunity in plain sight?
Most Popular Narrative: 13% Undervalued
Corpay's most followed narrative sets a fair value of $461, which sits above the latest close at $400.94 and frames the stock as trading at a meaningful discount based on long term cash generation and capital deployment plans.
Balance sheet optimisation, including a larger US$3.7b revolver, reduced term loan exposure, a natural hedge created by restricted cash and plans to deploy approximately US$15b of available capital through buybacks and corporate payments M&A, provides financial capacity that can amplify cash EPS and support long term earnings growth.
See why 14 investors see Corpay as 13% undervalued.
Result: Fair Value of $461 (UNDERVALUED)
Still, the proposed US$100m U.S. Vehicle Payments settlement and any shortfall versus analyst growth assumptions could be enough to challenge this 13% undervalued Corpay story.
Find out about the key risks to this Corpay narrative.
Another View: Corpay Through The P/E Lens
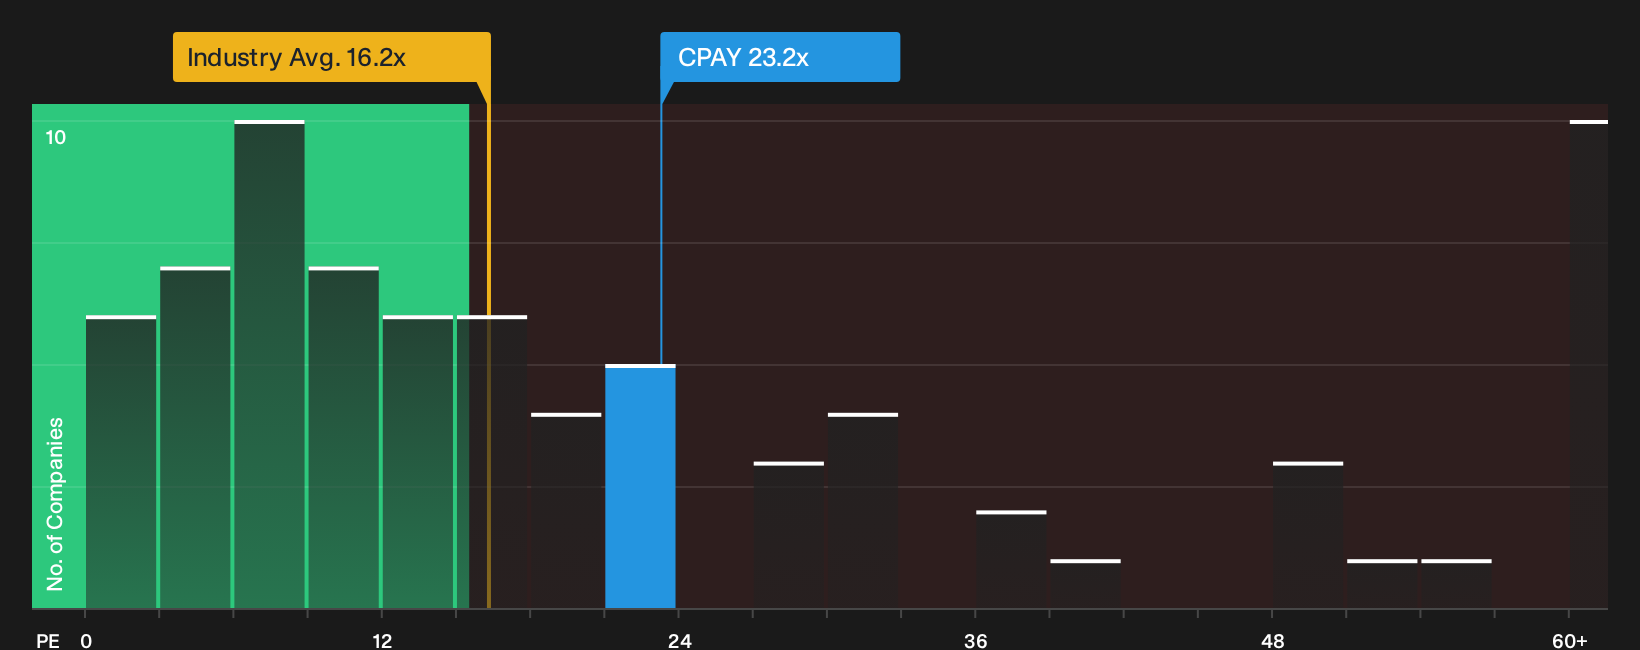
Corpay screens very differently when you swap the fair value narrative for the simple P/E check. The stock trades on 23.2x earnings, compared with 16.2x for the US Diversified Financial industry, 20x for peers, and a fair ratio of 16.8x that the market could eventually lean toward.
That gap points to valuation risk if sentiment cools, since even healthy profit growth might not protect you from multiple compression. How much of the future Corpay story do you think is already baked into this price compared with other options on your watchlist?
To pressure test that view against the current pricing, use the See what the numbers say about this price — find out in our valuation breakdown..
For a quick visual on how Corpay stacks up against its sector on earnings, refer to the
Next Steps
Mixed messages on valuation and sentiment only matter if you act on them. Run the numbers yourself, weigh both sides of the Corpay debate, then pressure test your view against the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Corpay?
If Corpay has sharpened your view on valuation and quality, do not stop here. Broaden your watchlist with ideas filtered for different strengths and risk profiles.
- Target resilient balance sheets and steadier financial footing by scanning the list of solid balance sheet and fundamentals (24 results).
- Prioritise value and quality together by reviewing the 33 high quality undervalued stocks that combine healthy fundamentals with potential mispricing.
- Dial down risk and potential volatility by focusing on the 29 resilient stocks with low risk scores that rank stronger on overall resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com