


Is Earnings Beat Altering The Investment Case For Amphenol Stock (APH)?
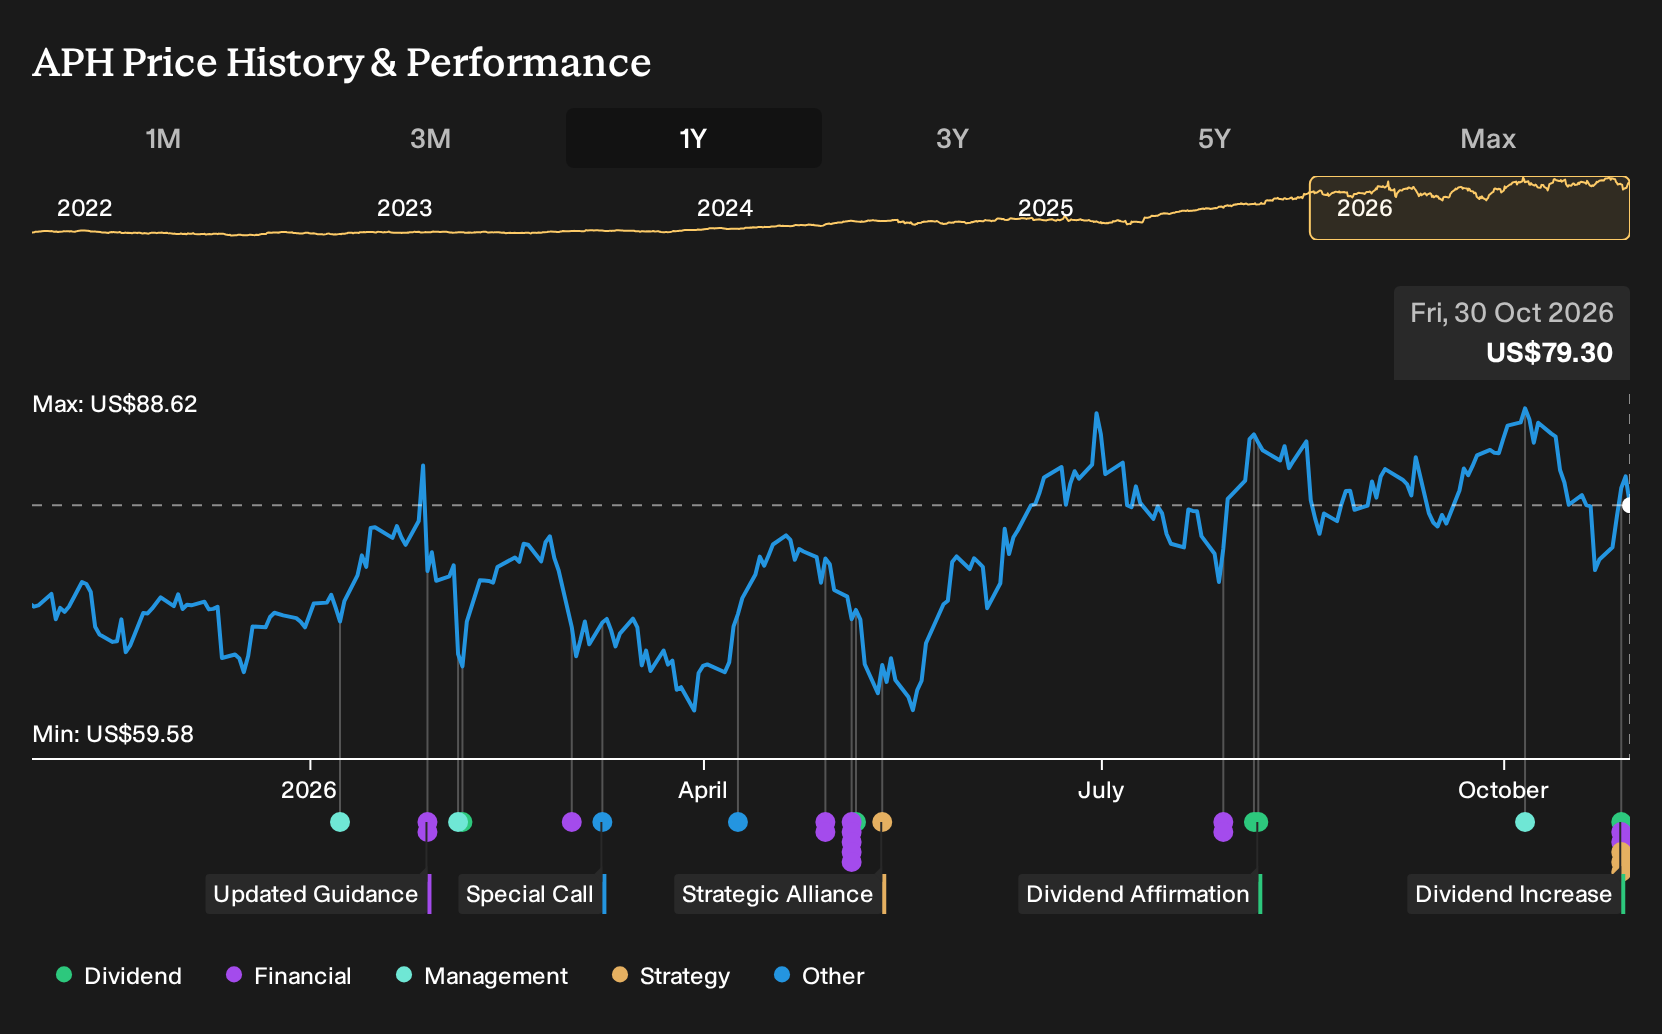
- Amphenol reported third quarter 2026 sales of US$10,229.7m and net income of US$2,034.3m, issued fourth quarter and full year guidance implying roughly 60% year over year sales growth, and increased its quarterly dividend on October 27, 2026 to US$0.15 per share from US$0.125.
- The combination of strong reported demand from AI focused data centers, contribution from recent acquisitions, and a 20% dividend raise points to management emphasizing both growth investment and direct cash returns to shareholders out of current earnings power.
- We will now assess how Amphenol's investment narrative could shift in light of its strong AI driven quarter and upbeat guidance.
Scan for other potential beneficiaries of the same AI and data center build out by reviewing our hand picked 54 AI infrastructure stocks alongside Amphenol's latest results.
Amphenol Investment Narrative Recap
To own Amphenol, you need to believe the build out of AI heavy data centers and broader electronics content continues to support high demand for its interconnects, while margins hold up as the business scales. The latest quarter, with strong AI data center demand and contribution from acquisitions, reinforces that thesis in the near term.
The main short term catalyst stays the same. Investors are watching whether AI driven IT datacom orders remain strong into 2027. The key risk is that any cooling in that demand, or higher ongoing taxes, could weigh on earnings even if reported sales stay at current levels.
The clearest announcement to focus on here is Amphenol’s Q4 and full year 2026 guidance. Management is calling for roughly 60% year over year sales growth for both the coming quarter and the full year, plus GAAP diluted EPS of US$0.80 to US$0.82 for Q4 and US$2.64 to US$2.66 for 2026.
Those numbers keep AI infrastructure, IT datacom and acquired assets such as CommScope CCS at the center of the story. They also set a high bar. Any sign that order intake, tax costs or acquisition integration trends move away from what this guidance implies would quickly become the next inflection point for the Amphenol investment case.
Amphenol's narrative projects US$53.0b revenue and US$11.7b earnings by 2029. That framework uses 17.0% yearly revenue growth and implies earnings rising by about US$5.8b from US$5.9b today to the US$11.7b analyst consensus level.
Uncover why Amphenol's fair value indicates a 32% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Another angle on Amphenol focuses on tax risk rather than AI strength. The most optimistic analysts were already penciling in US$62.1b in 2029 revenue and US$13.7b in earnings before this guidance and dividend hike. You now have a clear spread of opinion. Use it to compare several narratives and stress test your own view.
Explore 5 other Amphenol fair value estimates, including one that suggests potential upside of up to 54% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Amphenol research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amphenol. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amphenol's overall financial health at a glance.
Looking for more investment ideas beyond Amphenol?
Once you have formed a view on Amphenol, it can help to widen the lens and compare it with other businesses that fit different risk and return profiles using the Simply Wall St Screener.
- If you care most about quality at a sensible price, use our 33 high quality undervalued stocks to see companies that combine solid fundamentals with compressed expectations.
- If resilience and balance sheet strength sit at the top of your checklist, start with this list of solid balance sheet and fundamentals (24 results) to focus on businesses with room to handle shocks.
- If you want ideas that the market may be overlooking, scan through our 19 high quality undiscovered gems and compare their stories to what you see at Amphenol.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com