


Is Canon Marketing Japan (TSE:8060) Fully Priced As Earnings And Guidance Reset Expectations?
Canon Marketing Japan (TSE:8060) is back in focus after reporting nine month results to September 30, 2026, along with full year guidance that gives investors fresh numbers to reassess the stock.
The fresh earnings update has arrived after a strong run for Canon Marketing Japan, with a year to date share price return of 15.93% and a 1 year total shareholder return of 28.52%. The 3 and 5 year total shareholder returns of 140.90% and 297.32% point to momentum that has been building over a longer stretch.
Capitalize on the momentum around Canon Marketing Japan by scanning a curated set of 16 high quality undervalued stocks that combine solid cash flows with balance sheets built to handle tougher conditions.Canon Marketing Japan now has fresher earnings, firmer guidance, and a share price that has already moved. The business looks solid, but is the stock itself still priced on solid ground today?
Price-to-Earnings of 17.7x: Is it justified for Canon Marketing Japan?
On the latest numbers, Canon Marketing Japan trades on a P/E of 17.7x, which lines up with a share price of ¥4,021 that screens as expensive compared to both its sector and closer peers.
The P/E ratio compares what investors are currently willing to pay for each ¥1 of earnings. For a mature tech and solutions group like Canon Marketing Japan, P/E often reflects how the market weighs steady profit growth, capital discipline, and the reliability of cash generation rather than rapid expansion.
Here, the market is paying a higher multiple even though several metrics signal only moderate growth. Earnings are forecast to rise 4.6% per year and revenue 3.5% per year, both slower than the wider JP market forecasts, and Return on Equity sits at 11.9% with expectations of 11.7% in three years, which is described as low against a 20% benchmark. That kind of profile can mean investors are pricing in quality and consistency more than acceleration, which raises the bar for the valuation to hold.
The comparison points are clear. The P/E of 17.7x is described as expensive relative to the JP Electronic industry average of 15x, and also expensive versus a peer average of 12.8x. It is also high against an estimated fair P/E of 15x. This is a level the market could move towards if sentiment or growth expectations cool from here.
Explore the SWS fair ratio for Canon Marketing Japan.
Result: Preferred multiple of Price-to-Earnings 17.7x (OVERVALUED)
Still, that premium on Canon Marketing Japan could come under pressure if the modest 3.5% revenue and 4.6% earnings forecasts soften, or if the value score of 0 starts to matter more for sentiment.
Find out about the key risks to this Canon Marketing Japan narrative.
Another view on Canon Marketing Japan's valuation
There is a second lens to use for Canon Marketing Japan. The SWS DCF model pegs the future cash flow value at ¥4,017.15, which sits just under the current ¥4,021 price. That points to a market value that already bakes in most of the forecast cash generation. So where is the margin of error if expectations shift even slightly?
Look into how the SWS DCF model arrives at its fair value.
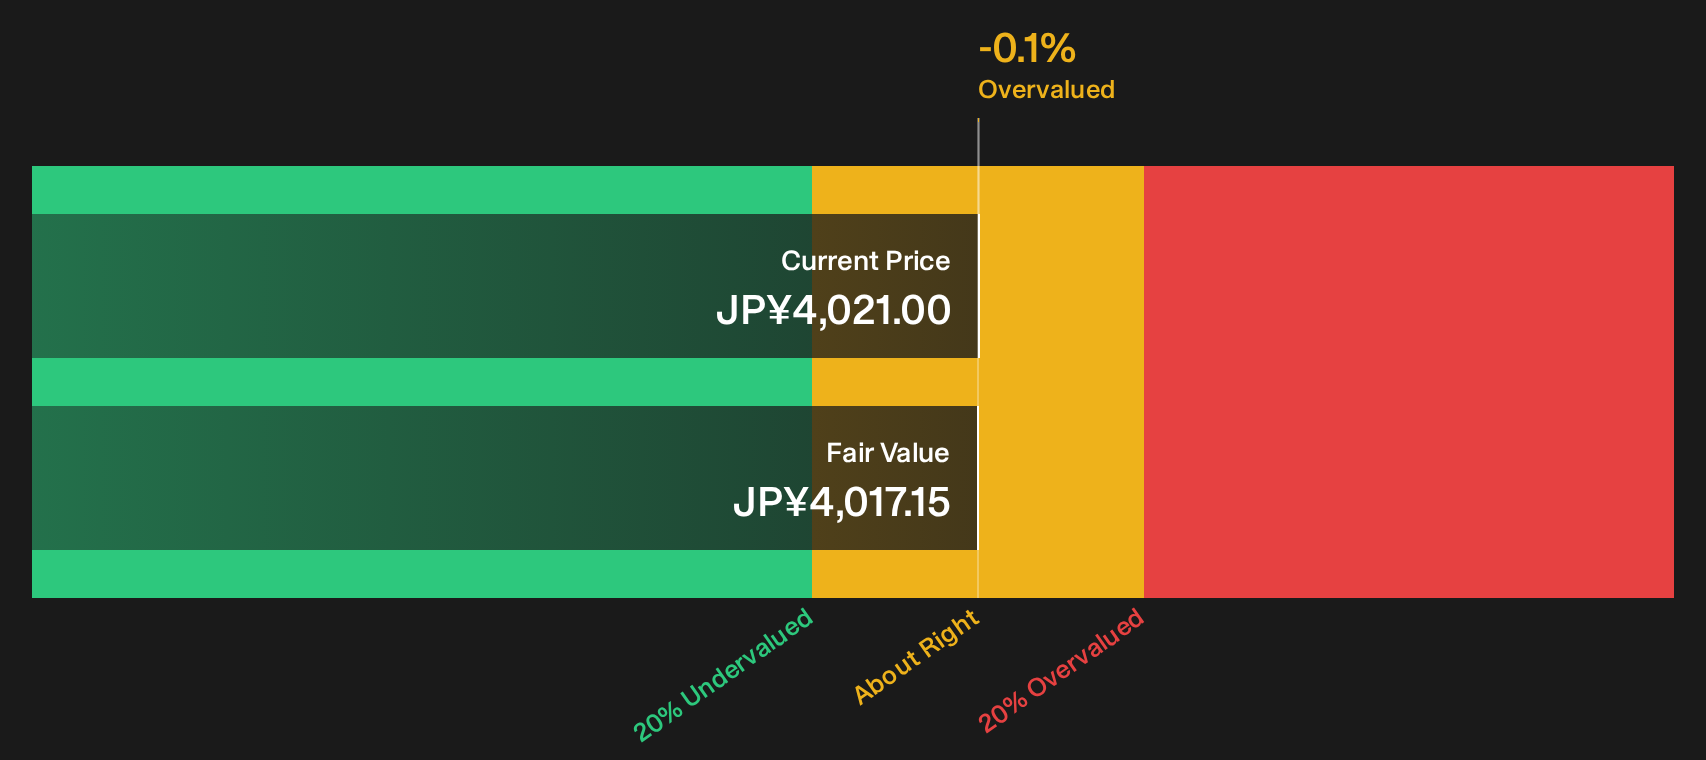
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Canon Marketing Japan for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Canon Marketing Japan's valuation and outlook can feel tricky, so treat this as a prompt to review the data yourself and decide where you stand in a timely way. To see both the potential advantages and the concerns that analysts are flagging, review the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Canon Marketing Japan?
If Canon Marketing Japan has sharpened your focus, do not stop here. A few targeted screens could surface opportunities that fit your style even better.
- Target sturdier portfolios by filtering for companies with resilient finances through the 23 resilient stocks with low risk scores.
- Hunt for overlooked potential by scanning the 69 high quality undiscovered gems before other investors catch on.
- Strengthen income prospects by reviewing a curated 28 dividend fortresses that may suit long term payout seekers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com