


Sino Land (SEHK:83) Could Be 27% Overvalued On AGM Dividend And Board Changes
Sino Land (SEHK:83) drew investor attention at its 27 October 2026 AGM after declaring a final dividend of HK$0.43 per share with a scrip option and confirming significant board changes.
At around HK$10.21 per share, Sino Land has seen its 7 day and 90 day share price returns drift lower. At the same time, the AGM dividend decision and board reshuffle keep governance and capital return in focus, while a 1 year total shareholder return of 11.76% and a 3 year total shareholder return of 50.66% point to stronger gains for long term holders than the more muted recent price performance suggests.
Scan beyond Sino Land to see which other property and real estate developers are moving on governance shifts and dividends with our hand picked 218 resilient stocks with low risk scores.
Sino Land has rewarded patient holders, while the recent share price drift and fresh dividend decision raise a practical question. Is most of the easy upside already in the rear view mirror, or does value still sit ahead?
Price-to-Earnings of 21.3x: Is it justified for Sino Land?
At around HK$10.21 per share, Sino Land trades on a P/E of 21.3x, which points to a richer valuation compared to many Hong Kong real estate peers that investors might use as a reference.
The P/E ratio compares the current share price with earnings per share. For a developer and landlord like Sino Land, it is a shorthand for how much the market is willing to pay for each dollar of profit from activities that range from property sales and leasing to hotels and investment income.
Here, the market is paying a materially higher P/E than both the Hong Kong Real Estate industry average of 8.5x and the peer group average of 14.6x. The current multiple also sits well above an estimated fair P/E of 13.3x. This indicates a level the valuation could potentially gravitate toward if sentiment or earnings expectations change.
Explore the SWS fair ratio for Sino Land.
Result: Price-to-Earnings of 21.3x (OVERVALUED)
Still, the rich 21.3x P/E leaves Sino Land exposed if revenue growth pressure continues or if property sentiment in Hong Kong and Mainland China weakens further.
Find out about the key risks to this Sino Land narrative.
Another View: What Sino Land's Cash Flows Say
The earnings multiple paints Sino Land as expensive, yet the SWS DCF model marks HK$10.21 as above an estimated future cash flow value of HK$8.03. That points to a stock priced roughly 27% higher than the model suggests. Which signal matters more for you: reported profit or projected cash?
Look into how the SWS DCF model arrives at its fair value.
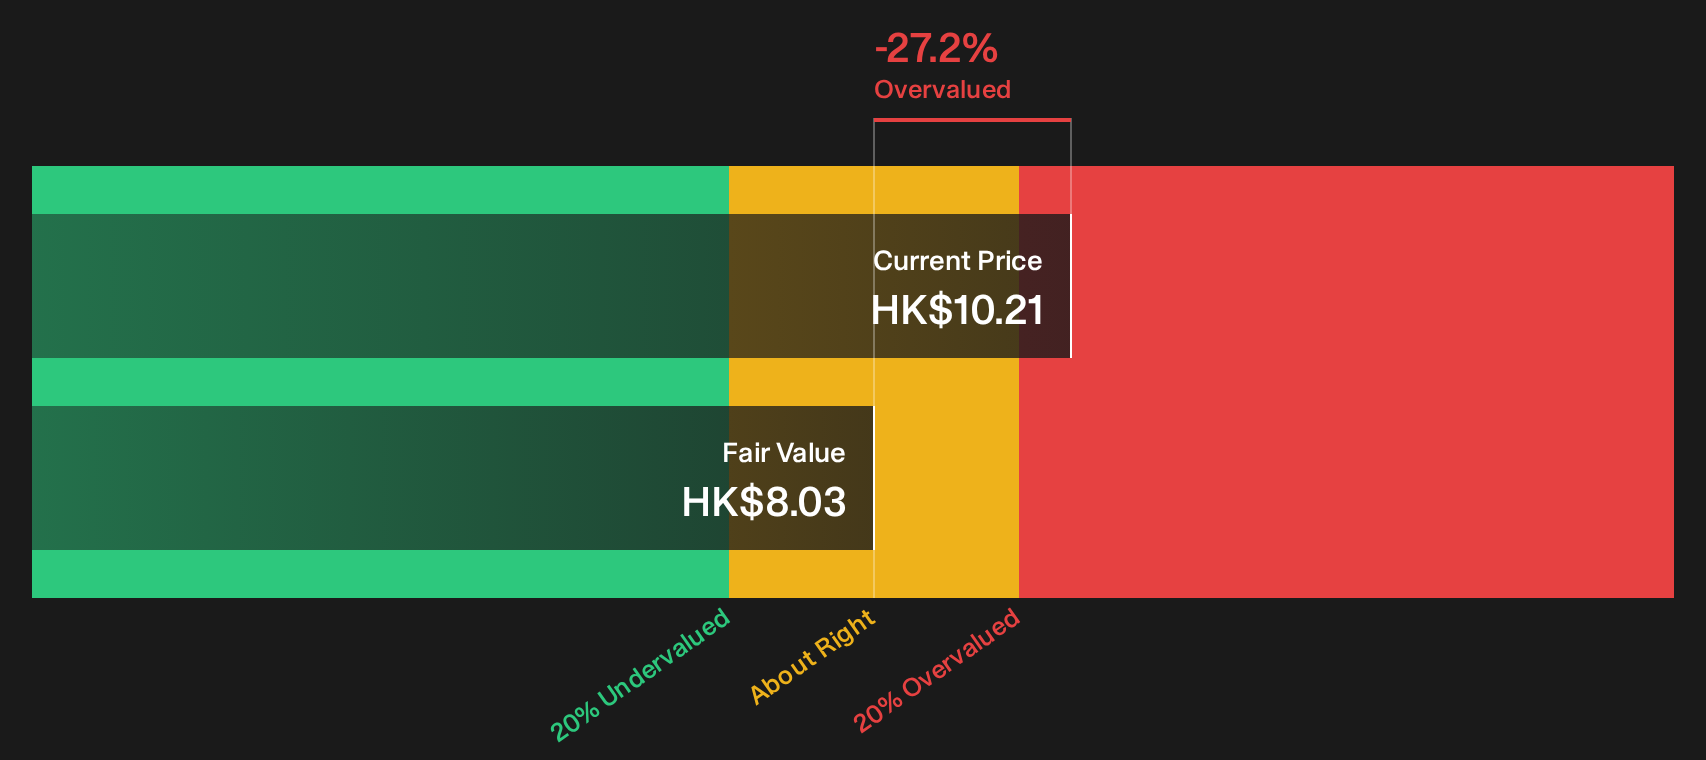
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sino Land for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 204 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Sino Land is mixed, and that is exactly when doing your own homework matters most. Use the full breakdown of its risks and rewards as your starting point by checking the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Sino Land?
If Sino Land has you rethinking your portfolio, this is the moment to widen your search and line up your next potential opportunity using focused screeners.
- Target reliable cash generators by scanning companies that feature as 222 dividend fortresses and could complement Sino Land's income profile.
- Hunt for mispriced opportunities by reviewing the 614 high quality undiscovered gems that combine solid fundamentals with lower market attention.
- Strengthen portfolio resilience by building a watchlist from the 218 resilient stocks with low risk scores that score well on financial stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com