


Why Fortive (FTV) Is Back In The Spotlight
Fortive (FTV) just delivered third quarter numbers that topped analyst expectations, supported by organic growth in its Intelligent Operating Solutions segment and new AI-enabled tools that led management to raise full year adjusted EPS guidance.
Fortive’s recent beat and guidance lift have arrived alongside a strong run in the shares, with a 30-day share price return of 13.5% and a 17.8% gain year to date. The 1-year total shareholder return of 30.2% points to momentum building over a longer stretch.
Scan for more Fortive-like momentum stories in capital goods and industrial tech by reviewing the hand-picked 19 high quality undiscovered gems that have recently impressed on earnings and product execution.
Fortive has just sprinted higher on earnings and guidance, which raises a simple fork in the road for investors. Is it worth stepping in after this run, or does patience for a better entry make more sense once valuation is unpacked next?
Most Popular Narrative: 2% Undervalued
Fortive is trading at $65.23 against a widely followed fair value marker of about $66.71, which suggests only a modest valuation gap and puts the focus squarely on whether its recurring revenue and cash generation can keep supporting that price.
The main thing that has to go right is that Fortive keeps converting its high-margin recurring revenue mix and AI product pipeline into consistent core growth while managing product mix shifts that have recently pressured gross margins.
The current narrative that Fortive is undervalued and bullish implies that the share price does not yet fully reflect the company’s 50% recurring revenue base, over $1b of annual free cash flow, and capital returns that have retired roughly 11% of diluted shares.
See why 1 investors see Fortive as 2% undervalued.
Result: Fair Value of $66.71 (UNDERVALUED)
Still, the Fortive story can wobble if lower margin products continue to weigh on gross margins or if any repeat of the prior 27.46% revenue drop occurs.
Find out about the key risks to this Fortive narrative.
Another View: Fortive Through The P/E Lens
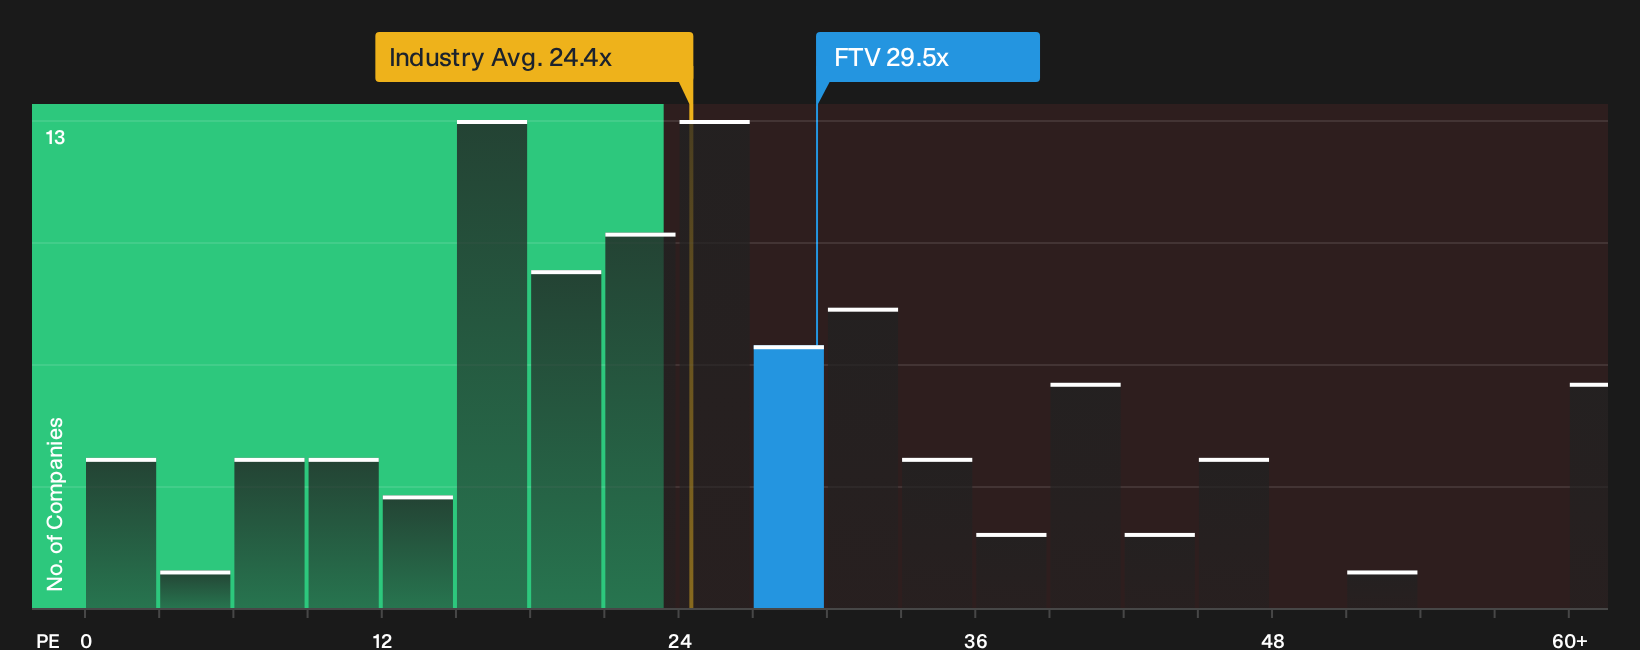
The first fair value marker paints Fortive as only modestly undervalued. Switch the lens to P/E and the picture shifts. The stock trades on 29.5x earnings versus 24.2x for the US Machinery group and a fair ratio of 20.9x, which signals investors are already paying a premium that could compress if sentiment cools.
Put simply, P/E suggests less of a bargain and more of a confidence trade, which raises a practical question for you. Is that valuation gap a risk worth accepting for this story, or a cue to look for similar quality on a lower multiple next?
For a deeper look at what these earnings multiples imply for risk and opportunity, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Fortive is divided between confidence in its recurring cash engine and concern about pockets of risk that could challenge that story. Move quickly, review the underlying data for yourself, and weigh up the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Fortive?
If Fortive has you thinking about where to put your next dollar, do not stop here. Broader idea hunting can sharpen your overall portfolio decisions.
Cast a wider net across quality and value by reviewing 33 high quality undervalued stocks that combine resilient balance sheets with pricing that still looks reasonable on key metrics.
Lock in income-focused ideas by scanning 5 dividend fortresses that aim for higher yields while maintaining coverage and balance sheet strength.
Dial down portfolio stress by checking 29 resilient stocks with low risk scores that screen for lower risk scores and steadier financial profiles before sentiment shifts again.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com