


China Everbright Environment Group (SEHK:257) Signs Dongguan Concession, Is It 38% Below Fair Value?
How the Dongguan project reshapes the China Everbright Environment Group story
The new Dongguan concession gives China Everbright Environment Group (SEHK:257) a long dated waste and kitchen waste treatment project, backed by a consortium structure and a build own operate transfer model.
This single contract introduces a 31 year operating horizon for a fresh municipal solid waste and kitchen waste platform in Guangdong, with fees from treatment services, on grid tariffs and resource utilisation products set out in the agreement framework.
Against this Dongguan announcement, China Everbright Environment Group’s share price sits at HK$4.795, with a 1 month share price return of 4.24% and a 3 month decline of 5.98%, suggesting momentum has cooled in the short term, while a 3 year total shareholder return of about 110% points to much stronger longer term gains.
Spot under-the-radar waste and environmental service opportunities alongside China Everbright Environment Group by scanning our hand picked 614 high quality undiscovered gems in this part of the market.China Everbright Environment Group now has a fresh 31 year Dongguan concession layered onto a long running waste portfolio. Strong operating foundations are one thing. Is the HK$4.795 share price attractive today?
Preferred P/E of 7.1x: Is it justified for China Everbright Environment Group?
On the numbers alone, China Everbright Environment Group trades on a P/E of 7.1x, which screens as inexpensive compared to both its own fair P/E estimate and the wider Commercial Services space. At a last close of HK$4.795, the stock is also flagged as trading at a 38% discount to an internal fair value estimate based on future cash flows of HK$7.73.
P/E simply compares the market price to annual earnings per share. For a business like China Everbright Environment Group, which is already profitable and runs long dated Environmental Energy, Greentech and Water projects, this metric gives a quick read on how much investors are paying for each unit of current profit. A lower P/E often indicates that the market is either cautious on future earnings, or has not fully repriced improving profitability.
Recent data shows a mixed picture. Earnings declined by 14.3% per year over the past 5 years, yet profit grew 32.6% over the last year and margins improved from 10.8% to 15.1%. Forecasts point to earnings growth of 3.8% per year and revenue growth of 2.2% per year, which are both slower than the wider Hong Kong market, and Return on Equity is currently a modest 6.1% with expectations for 8% in three years. That combination of recovering profitability but muted growth and low ROE helps explain why the multiple has not pushed higher, even though analysts are in solid agreement that the share price could rise from current levels.
- Compared with peers on P/E, China Everbright Environment Group trades at 7.1x versus a peer average of 19.9x.
- Relative to the Hong Kong Commercial Services industry, the same 7.1x P/E is below the 10.8x sector average.
- Against an estimated fair P/E of 8x, the current valuation still comes in lower than the level models suggest the ratio could move toward.
This is strong comparative pricing. The market is valuing each dollar of China Everbright Environment Group earnings at a sizeable discount to both the sector and peer averages, and even below an internally assessed fair multiple.
Explore the SWS fair ratio for China Everbright Environment Group.
Result: Preferred multiple of price-to-earnings of 7.1x (UNDERVALUED)
Still, the China Everbright Environment Group story can change quickly if funding costs rise or if new environmental concessions, like Dongguan, are delayed or repriced.
Find out about the key risks to this China Everbright Environment Group narrative.
Another view on China Everbright Environment Group’s value
The low 7.1x P/E paints China Everbright Environment Group as cheap, yet the SWS DCF model suggests the shares trade about 38% below an estimated future cash flow value of HK$7.73. One metric signals a discount today, while the other points to a bigger gap. Which one do you trust more?
Look into how the SWS DCF model arrives at its fair value.
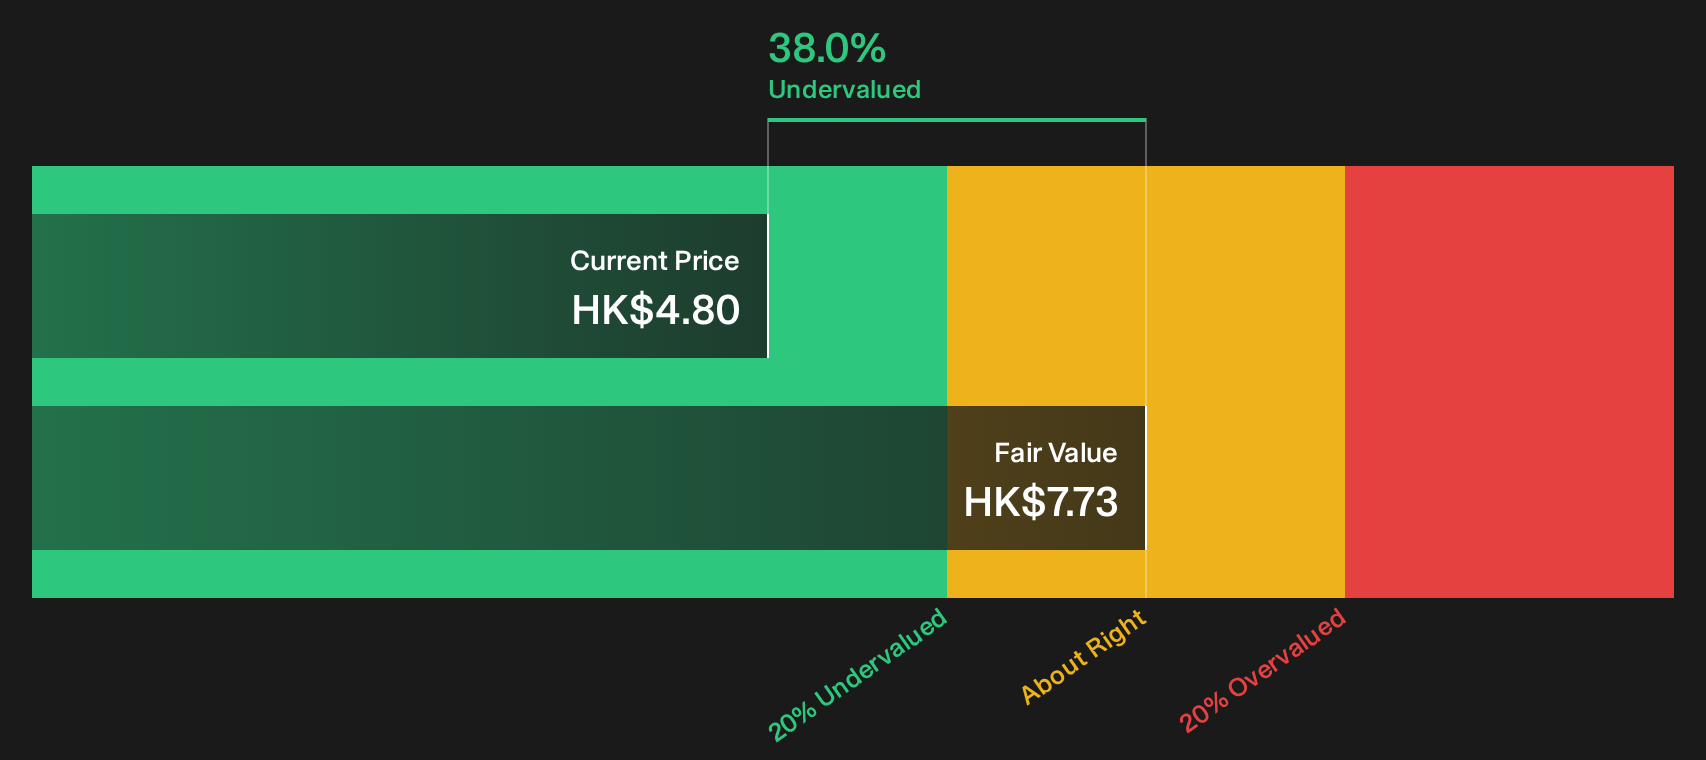
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Everbright Environment Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 204 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Reading this, you can see the China Everbright Environment Group picture is not one sided, with both concerns and reasons for optimism in the mix. Move quickly and review the underlying data before markets reset around it and focus on the 5 key rewards and 2 important warning signs
Looking for more investment ideas beyond China Everbright Environment Group?
If you stop with China Everbright Environment Group, you miss a wider field of potential opportunities that could better fit your risk appetite and portfolio goals.
- Target potential bargain entries by scanning a curated set of companies that look undervalued on quality and price using the 204 high quality undervalued stocks.
- Strengthen your income stream by filtering for businesses that combine higher yields with resilient payout profiles through the 222 dividend fortresses.
- Dial down portfolio stress by focusing on companies screened for sturdier balance sheets and cleaner fundamentals using the list of solid balance sheet and fundamentals (199 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com