


Yamada Holdings (TSE:9831) Looks Pricey As Raised Guidance Lifts The Stakes
What Yamada Holdings’ Guidance Revision Tells You
Yamada Holdings (TSE:9831) has raised its consolidated earnings guidance for the six months to 30 September 2026, citing stronger air conditioner demand under new energy rules and firmer large appliance sales.
At a share price of ¥733.2, Yamada Holdings has seen momentum build, with a 30‑day share price return of 2.86% and a year to date share price gain of 39.74%. The 1‑year total shareholder return of 63.30% shows how strongly recent news and guidance revisions have fed into both price performance and dividends over time.
Scan how Yamada Holdings’ guidance upgrade compares with other retailers benefiting from strong appliance demand by reviewing the hand-picked 16 high quality undervalued stocks that may warrant a closer look.
The guidance lift and sharp share price run put Yamada Holdings at an interesting crossroads. Do you accept today’s terms, or wait and hope for a cheaper entry that still reflects this upgraded outlook?
Price-to-Earnings of 30.6x: Is It Justified?
Yamada Holdings is being valued on a P/E of 30.6x at a last close of ¥733.2, which places a rich price on each yen of current earnings compared with similar retailers.
The P/E ratio measures how much investors are willing to pay for one unit of profit. For a retailer like Yamada Holdings that is tied to household spending and appliance cycles, a higher P/E usually reflects strong confidence in future profits or in the resilience of the business model.
Here that optimism sits beside some mixed fundamentals. Earnings are forecast to grow 13.9% per year, faster than the wider JP market at 9.5%. However, reported profit has declined over the past year and over the past 5 years, and recent margins of 0.9% are lower than last year. That kind of disconnect suggests the market is paying up well ahead of the current earnings profile. The estimated fair P/E of 18.7x points to a level the valuation could move toward if sentiment cools or forecasts change.
The comparison with peers is also stark. Yamada Holdings trades at a P/E of 30.6x while the JP Specialty Retail industry average sits at 13.4x and the peer group average is 12.1x. This means the shares are priced at more than double what similar retailers command and well above the 18.7x level suggested by the fair ratio model.
Explore the SWS fair ratio for Yamada Holdings.
Result: Price-to-Earnings of 30.6x (OVERVALUED)
Still, the story can change quickly if appliance demand cools under tougher consumer budgets or if Yamada Holdings’ thin 0.9% margins come under further pressure.
Find out about the key risks to this Yamada Holdings narrative.
Another View On Yamada Holdings’ Value
The SWS DCF model paints a very different picture for Yamada Holdings. At a share price of ¥733.2, the stock trades well above the estimated future cash flow value of ¥343.43. That signals an overvalued reading on this method and raises a simple question: Are you comfortable paying more than double what the cash flows imply?
Look into how the SWS DCF model arrives at its fair value.
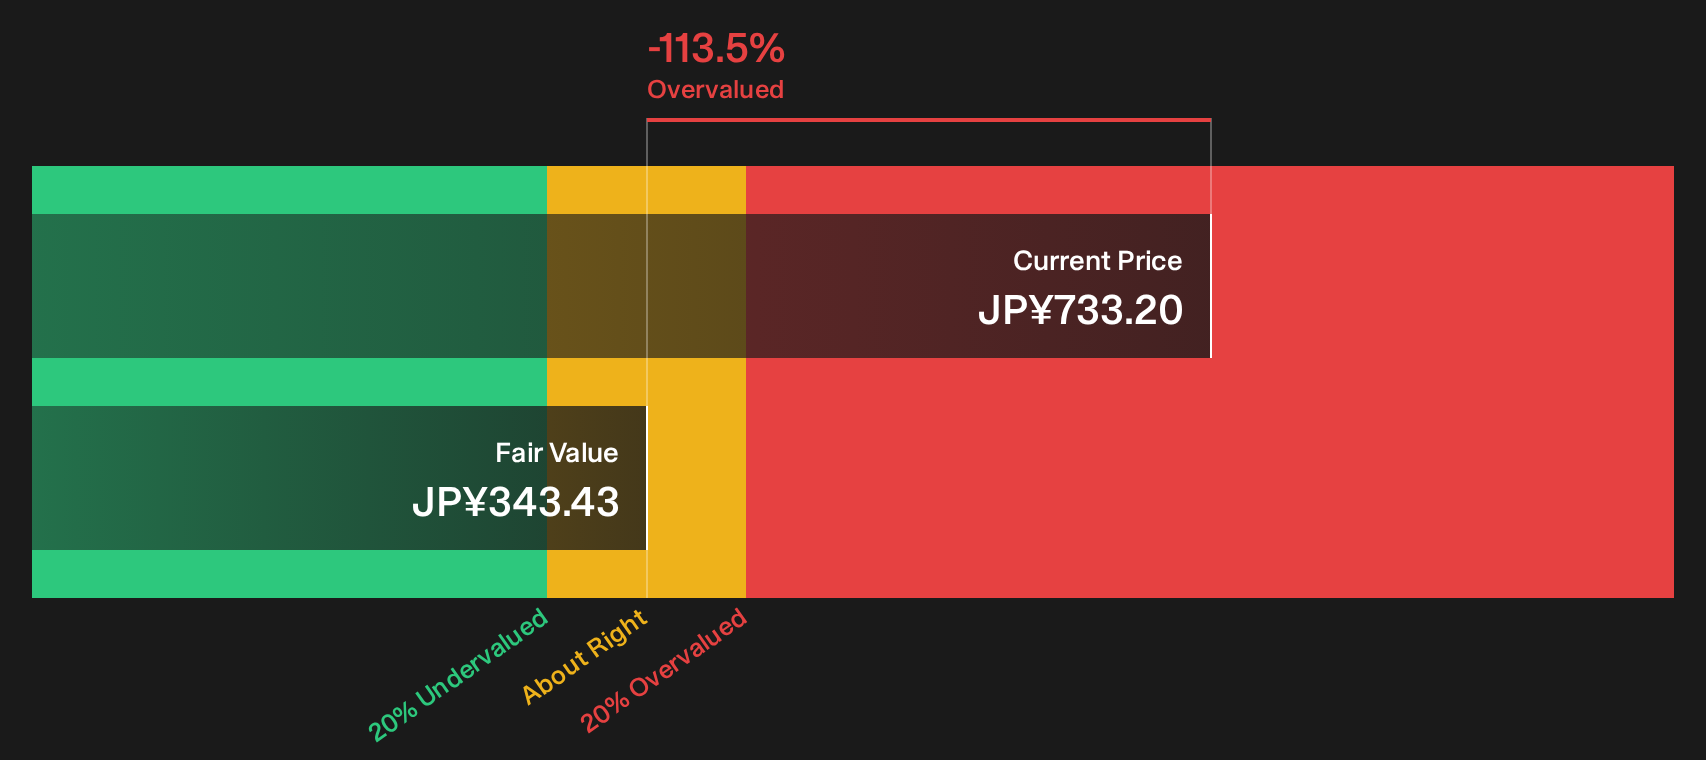
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yamada Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Yamada Holdings so far. Act while the data is still fresh and weigh both sides by checking the 1 key reward and 3 important warning signs.
Looking For More Investment Ideas Beyond Yamada Holdings?
If Yamada Holdings has your attention, broaden the watchlist now so you do not rely on a single story when plenty of other opportunities exist.
- Target resilience first by scanning a 23 resilient stocks with low risk scores that filters for companies with stronger balance sheets and steadier risk profiles than most investors usually monitor.
- Hunt for mispriced quality through a 69 high quality undiscovered gems that surfaces under-followed businesses with fundamentals that may not be fully reflected in current prices.
- Build a sturdier income stream by reviewing a 28 dividend fortresses focused on higher yielding payers that still back those distributions with solid financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com