


How Stronger Earnings Will Impact Highwoods Properties Stock
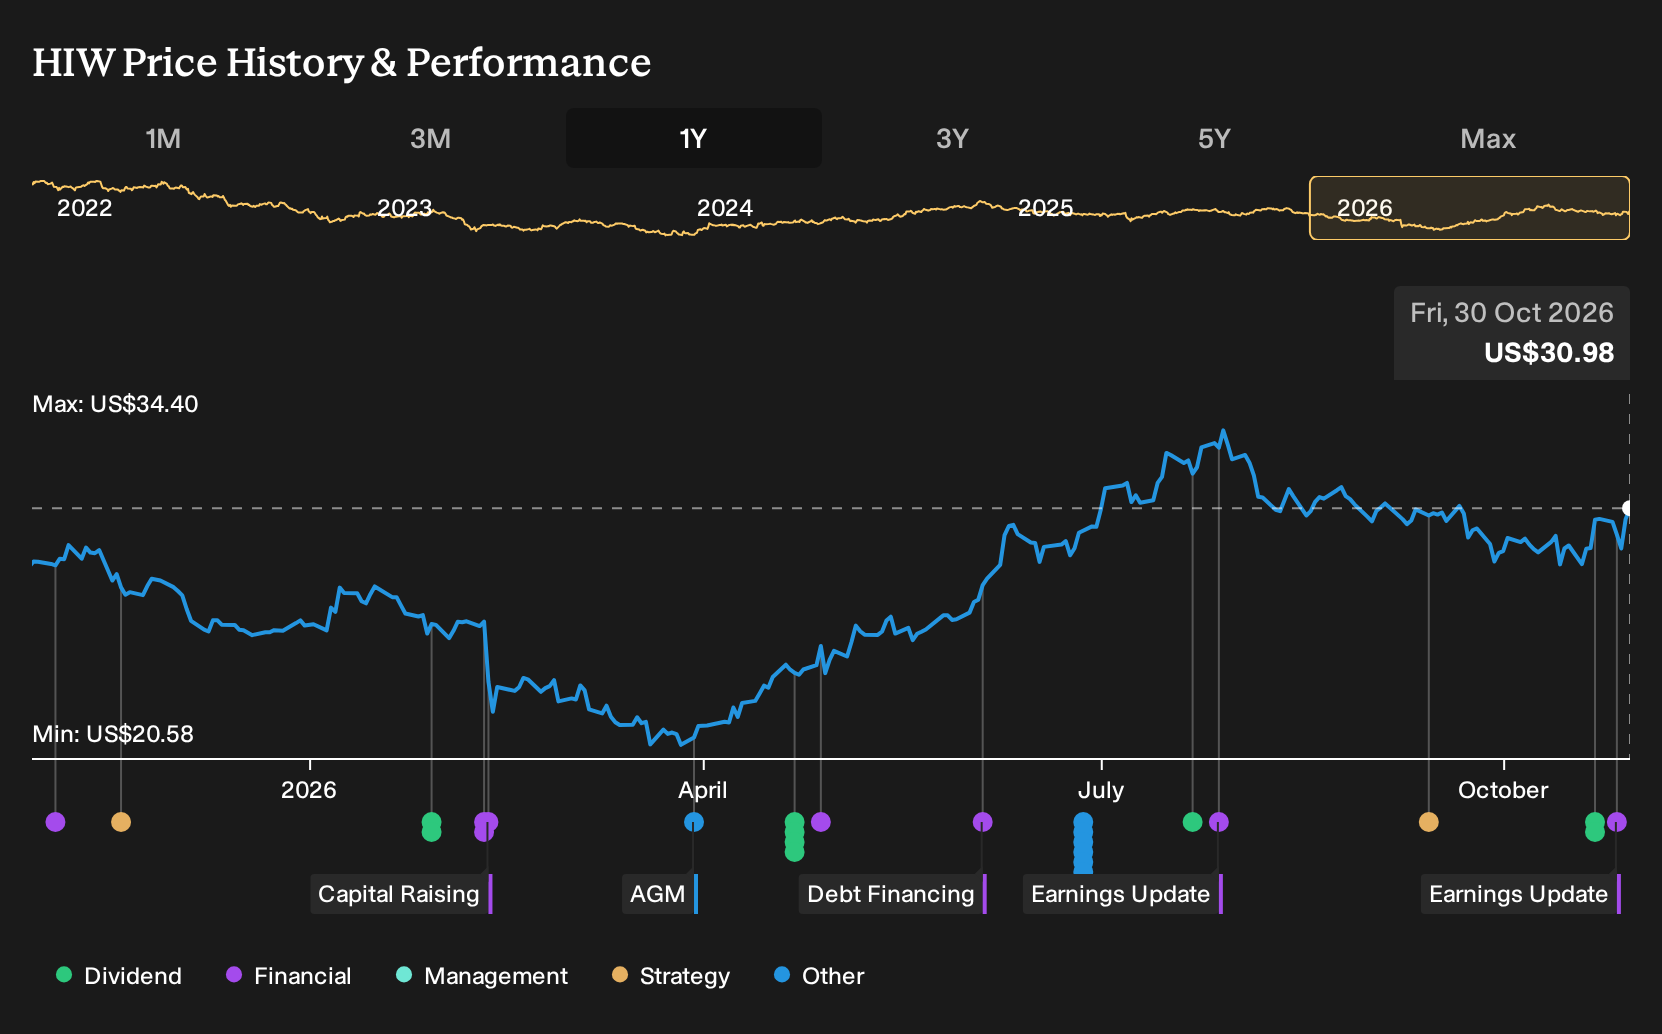
- Highwoods Properties reported third quarter 2026 basic and diluted earnings per share from continuing operations of US$0.29, with year to date EPS at US$1.42, and affirmed a quarterly common dividend of US$0.50 per share and a scheduled preferred dividend.
- The combination of higher earnings per share from continuing operations and continued common and preferred dividend declarations shows how Highwoods Properties is balancing income distributions with current profitability from its office portfolio.
- We will now look at how Highwoods Properties’ earnings per share may relate to its investment narrative for income focused investors.
Highwoods Properties Investment Narrative Recap
To own Highwoods Properties, you need to believe its Sun Belt office focus and business district exposure can keep properties leased and cash flows resilient despite ongoing pressure on traditional office demand. The third quarter EPS of US$0.29 from continuing operations, and US$1.42 year to date, points you back to how durable that earnings base really is.
The short term swing factor is whether signed leases, rent terms and leasing CapEx start to translate into cleaner, less one off earnings without stretching the balance sheet. The biggest risk is that dividends and elevated leasing spend keep pulling on cash flow at the same time as office demand remains under strain.
The most relevant update for you right now is the reaffirmed US$0.50 quarterly common dividend, which implies US$2.00 per share on an annualized basis. Set that against the recent EPS run rate and you get a quick sense of how much of Highwoods Properties’ current earnings is being returned to shareholders.
If you are concerned about dividend coverage, that payout level keeps the focus squarely on funds from operations, leasing CapEx near US$170 million annualized, and any dilution from asset recycling. For income focused holders, potential catalysts appear tied to whether leasing progress and rent spreads feed through to cash generation strongly enough to support that dividend policy without adding financial strain.
Highwoods Properties is framed around analysts’ expectations that revenue could reach US$919.4 million and earnings US$91.6 million by 2029, based on a 3.1% yearly revenue growth rate but an earnings decline of about US$74.8 million from current earnings of US$166.4 million.
Discover why Highwoods Properties' fair value indicates a 4% potential upside to its current price, which could narrow faster than income investors expect.
Exploring Other Perspectives
You can see a very different angle if you focus on the bullish catalyst around lease-up. The most optimistic analysts were working off revenue of about US$966.1 million and earnings of US$78.1 million by 2029, as well as a higher P/E multiple, before this Highwoods Properties earnings and dividend news, so their narrative may shift meaningfully from here.
Explore 2 other Highwoods Properties fair value estimates, including one that suggests potential upside of as much as 12% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Highwoods Properties research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Highwoods Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Highwoods Properties' overall financial health at a glance.
Looking for more investment ideas beyond Highwoods Properties?
If Highwoods Properties has sharpened your focus on income and balance sheet resilience, it can help to line it up against a wider watchlist. Use the Simply Wall St Screener to spot other businesses with income profiles, risk levels, and financial foundations that fit your own comfort zone.
- For investors who care about both quality and value, scan a curated pool of companies that screen well on fundamentals and valuation edges using the 19 high quality undiscovered gems.
- If capital preservation and stability sit higher on your priority list, narrow the field to businesses with steadier risk characteristics by filtering through the 29 resilient stocks with low risk scores.
- When consistent income is the focus, compare Highwoods Properties' yield and payout profile with a broader universe of high distribution payers by working through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com