


Is Kinetik Holdings (KNTK) Undervalued On Its New Dividend And Capacity Outlook?
Kinetik Holdings (KNTK) is back in focus after declaring a quarterly dividend of $0.81 per share, which implies a 5.82% annualized yield and highlights the midstream operator’s current income profile.
Recent trading has reflected rising optimism around Kinetik Holdings, with the share price delivering a 30-day return of 7.75% and a 90-day move of 14.6% to around $56.60. The year-to-date share price return of 55.24% and three-year total shareholder return of 94.91% indicate strong momentum over both shorter and longer horizons as investors weigh the richer dividend and prior operational improvements against shifting views on risk, including a 1-day share price decline of 2.56% following the latest news.
Scan other income-focused midstream plays by checking the hand-picked 5 dividend fortresses alongside the latest move from Kinetik Holdings.
After a sharp run and a rich yield on offer, Kinetik Holdings now poses a harder question for new money. Does the current price still leave enough upside to justify the midstream risk profile?
Most Popular Narrative: 1.2% Undervalued
Kinetik Holdings last closed at $56.60, fractionally below the most followed fair value estimate of $57.31. As a result, the current setup depends on how future projects and contracts support that gap closing.
The main thing that has to go right is that Kinetik executes its capital-heavy buildout, including Kings Landing II, ECCC expansion, and additional cryogenic capacity, while keeping leverage within its stated range and managing Waha-related price risk through Gulf Coast access and hedging.
See why 9 investors see Kinetik Holdings as 1% undervalued.
Result: Fair Value of $57.31 (UNDERVALUED)
Still, high 2026 capex of about US$560 million and ongoing Waha gas price dislocations could challenge Kinetik Holdings if cash flows or hedging underperform expectations.
Find out about the key risks to this Kinetik Holdings narrative.
Another View: Kinetik Holdings On Earnings Multiples
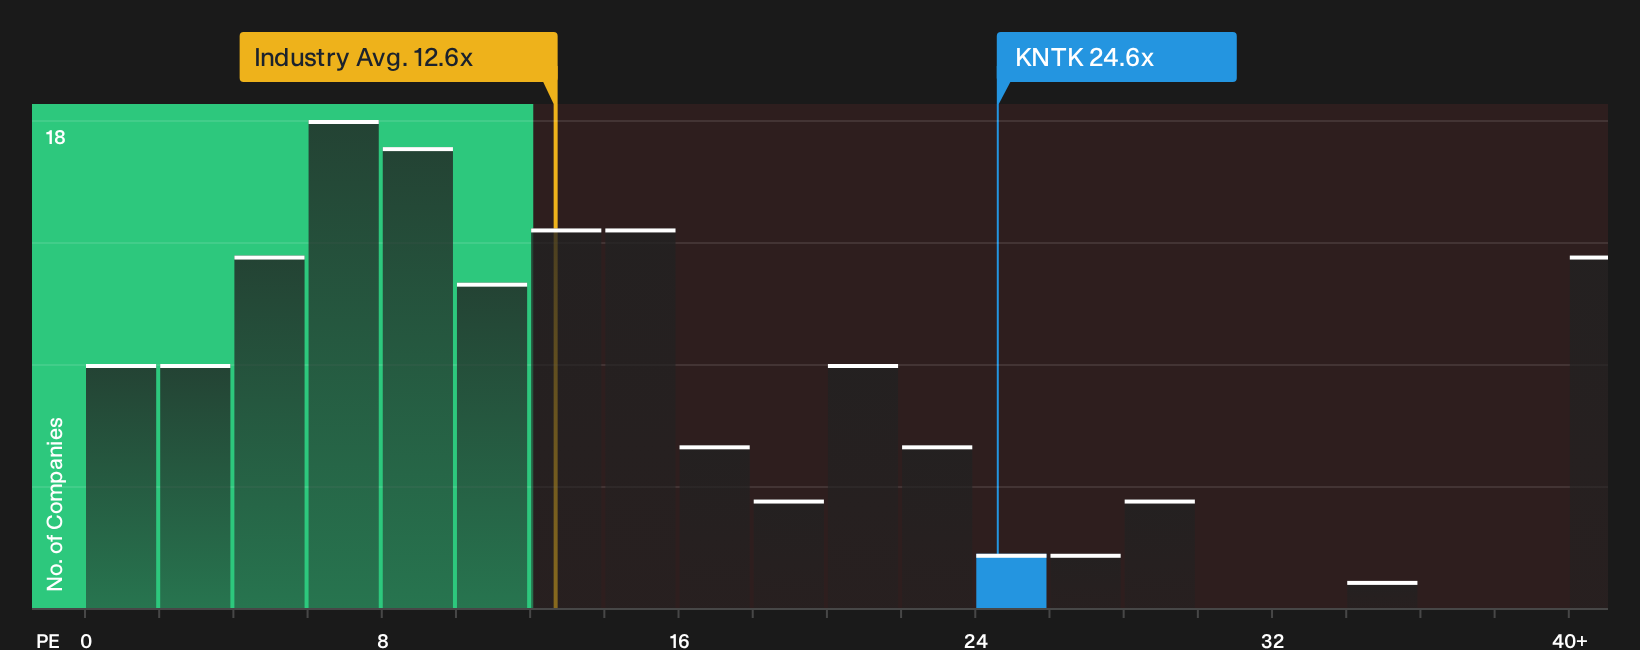
Where the fair value narrative points to Kinetik Holdings as modestly undervalued, the earnings multiple tells a tougher story. The stock trades on a P/E of 24.6x, which is well above the US Oil and Gas industry at 12.6x and peers at 15.4x, and also above a fair ratio of 17.4x. That gap suggests investors are already paying a premium, so how comfortable are you with that valuation if sentiment cools?
See what the numbers say about this price in more detail by reviewing the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Kinetik Holdings is split, which is exactly why you should look through the underlying data yourself and decide where you stand. If you want a quick way to frame both sides of the debate, start by weighing the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Kinetik Holdings?
If you stop at Kinetik Holdings, you miss a wider opportunity set. Use a few targeted screens to pressure test your income, value, and risk assumptions.
- Target resilient cash generators by scanning companies with robust finances and low leverage through the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispricings by reviewing the 33 high quality undervalued stocks and comparing market expectations to underlying fundamentals.
- Strengthen your income playbook by lining up high-yield candidates inside the 5 dividend fortresses before the next round of payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com