


Raised 2026 Revenue Guidance Might Change The Case For Investing In Leonardo DRS (DRS)
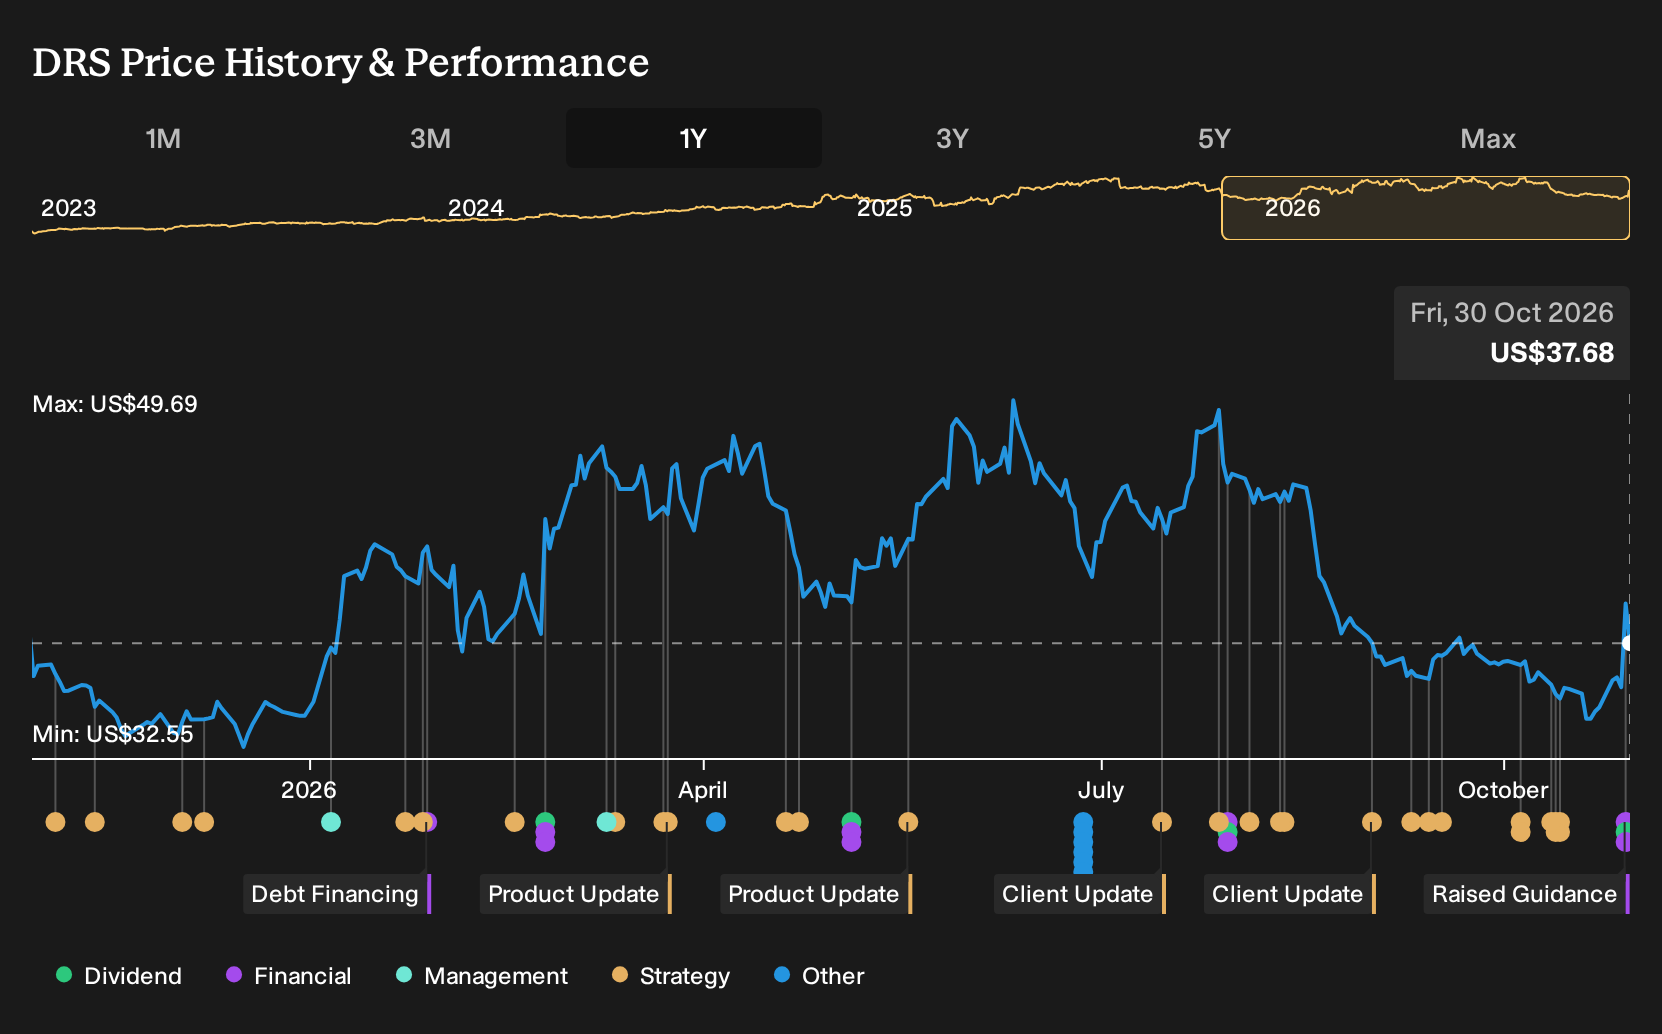
- Leonardo DRS reported third quarter 2026 sales of US$1,066 million and net income of US$115 million, with both basic and diluted EPS from continuing operations at US$0.43.
- The business paired these results with raised 2026 revenue guidance and a US$0.09 per share cash dividend, indicating management focus on both growth execution and direct cash returns.
- We will now explore how Leonardo DRS's earnings results and higher full year revenue guidance could influence the broader investment narrative.
Scan beyond Leonardo DRS and line up other defense contractors and mission-critical suppliers with the same kind of earnings momentum using the hand picked 29 resilient stocks with low risk scores.
Leonardo DRS Investment Narrative Recap
To own Leonardo DRS, you need to be comfortable with a defense electronics business that relies on converting a large funded backlog into consistent deliveries, while spending more on R&D and capacity. The latest quarter showed higher sales, earnings and EPS versus a year ago, which supports that execution story in the near term.
The key short term catalyst is how efficiently those record bookings, radar programs, naval power systems and space sensing contracts turn into revenue and cash. The biggest risk is that the heavier investment and higher expectations fade back toward older growth patterns, which could pressure margins and free cash flow if order momentum slows.
The raised 2026 revenue guidance looks most relevant here because it directly ties to whether Leonardo DRS can translate its US$5.6b funded backlog and recent wins into near term performance. Management now expects revenue of US$3.95b to US$3.985b, slightly above the prior range, and this anchors a lot of investor attention on delivery pacing.
This updated outlook interacts with catalysts such as radar, infrared and naval propulsion awards, plus the planned RAFT acquisition that targets AI mission software integration. It also sharpens focus on risk. Any stumble in ramping capacity, integrating new capabilities or sustaining order flow could leave the raised guidance hard to meet and limit how much earnings benefit investors actually see.
Analysts currently frame the Leonardo DRS narrative around revenues reaching US$4.7b and earnings of US$458.3 million by 2029. This implies 7.9% yearly revenue growth and an earnings increase of about US$136 million from the current US$322.0 million base.
Uncover how Leonardo DRS' fair value indicates a 39% potential upside to its current price that may not be sustained.
Exploring Other Perspectives
For the most optimistic analysts, the real swing factor is radar and counter UAS demand. Before this latest Leonardo DRS update, they were already pencilling in roughly 8.8% yearly revenue growth and earnings around US$479.0 million by 2029. You might read the new guidance and dividend and wonder if those bullish narratives now look too low or too high.
Explore 4 other Leonardo DRS fair value estimates, including one that suggests potential upside of as much as 57% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Leonardo DRS research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Leonardo DRS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Leonardo DRS' overall financial health at a glance.
Looking for more investment ideas beyond Leonardo DRS?
If the Leonardo DRS story has sharpened your thinking but you want a broader watchlist, use the Simply Wall St Screener to line up other opportunities that fit your own risk and return preferences.
- If you are drawn to resilient balance sheets and cleaner fundamentals, start with a list of solid balance sheet and fundamentals (24 results) that can help you focus on financially robust businesses.
- If value is your main priority, shortlist potential candidates using a 33 high quality undervalued stocks that highlights companies where quality and pricing look out of sync.
- If you want ideas that still fly under most investors' radar, cast a wider net with a 19 high quality undiscovered gems that surfaces lesser known stocks with stronger fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com