


Is Earnings And Dividend Hike Altering The Investment Case For Prosperity Bancshares (PB)?
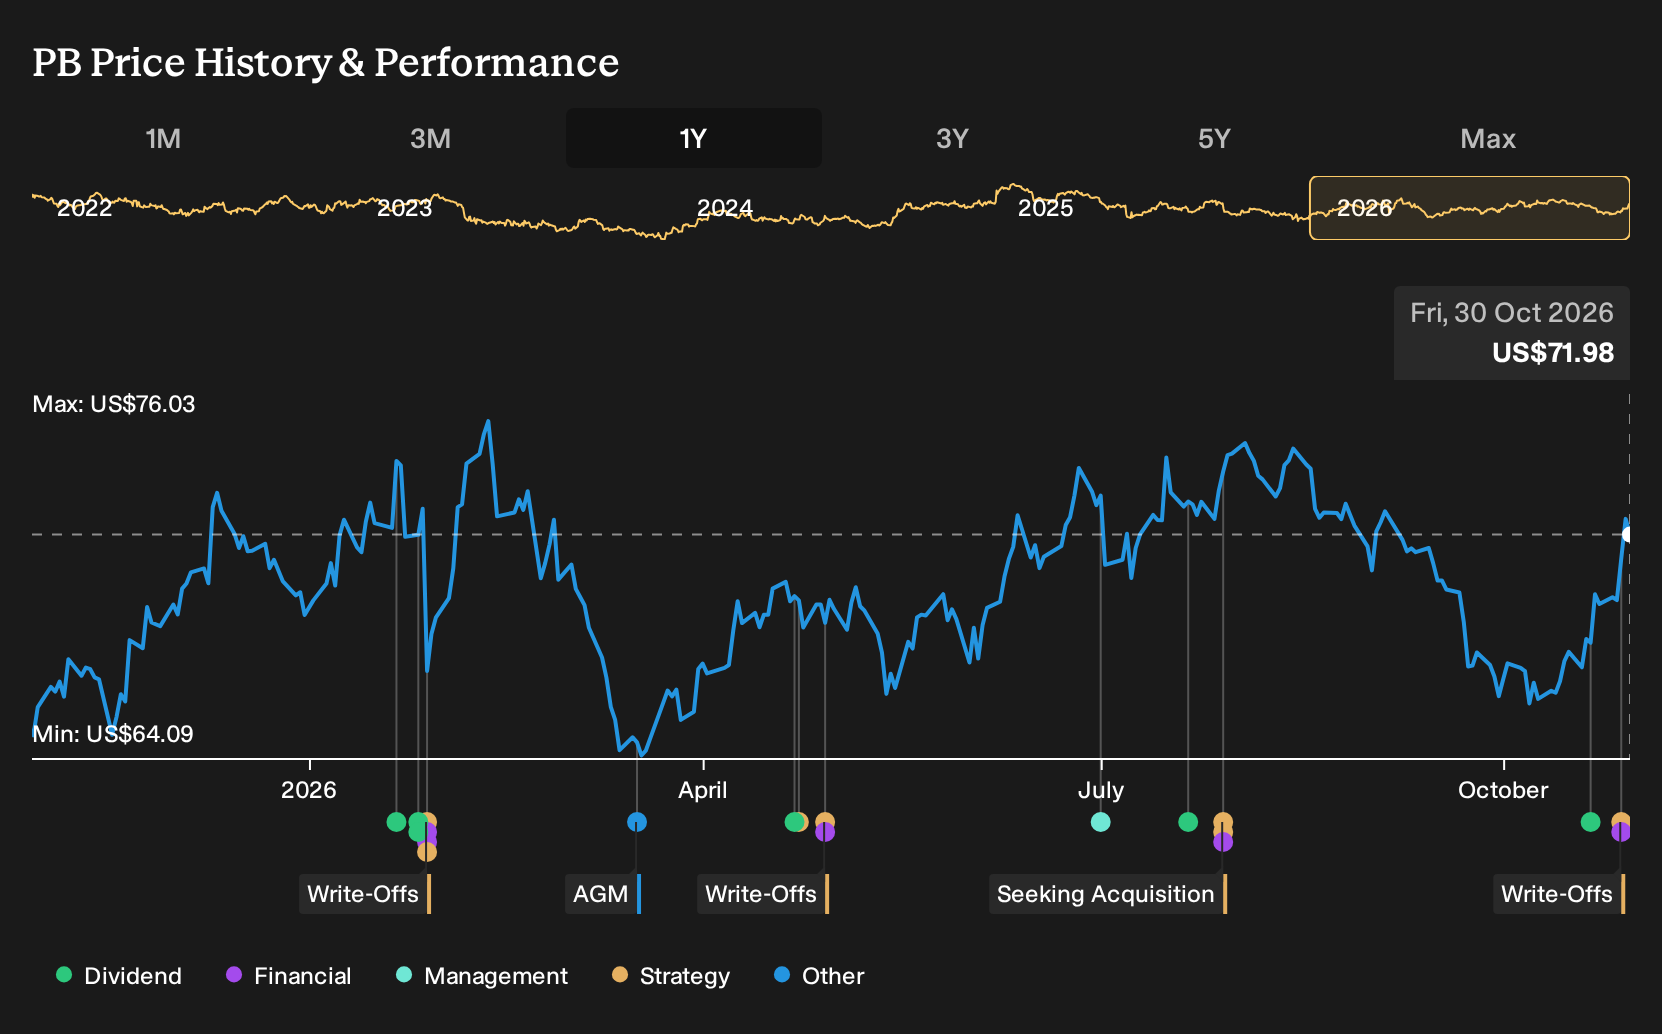
- Prosperity Bancshares reported third quarter 2026 net interest income of US$442.98 million and net income of US$141.46 million, alongside a higher quarterly dividend of US$0.64 per share and ongoing buybacks.
- Despite higher net interest income and lower net charge offs of US$4.44 million, earnings per share from continuing operations were lower than a year earlier, which points to shifting balance sheet and cost dynamics beneath the headline figures.
- In this context, we will look at how Prosperity Bancshares' investment narrative interacts with rising net interest income and a higher dividend commitment.
Scan how Prosperity Bancshares' latest earnings, dividend move, and buybacks compare with other banks by checking our curated 29 resilient stocks with low risk scores in one place.
Prosperity Bancshares Investment Narrative Recap
For a shareholder in Prosperity Bancshares, the core belief is that a growing Texas and Oklahoma footprint, a relatively low cost deposit base and tight expense control can turn solid net interest income into resilient earnings over time. The latest quarter fits that story on revenue, but the lower earnings per share keep execution on costs and integration as the key short term catalyst.
The biggest risk still sits on the credit and loan growth side. Recent net charge offs of US$4.44 million are well below the spike seen earlier in 2026, yet any renewed issues in shared national credits or continued flat loan balances could quickly eat into that higher net interest income and limit progress on profitability.
The dividend increase to US$0.64 per share is the clearest new data point for investors. It raises the cash commitment and signals that Prosperity Bancshares is comfortable distributing a larger slice of earnings while also running an active buyback program in the background.
That higher payout links directly to the main near term questions around the stock. Investors now need to watch whether the bank can sustain this larger dividend while still funding growth, managing credit risk after the earlier 2026 charge off spike and delivering the cost savings and efficiency targets tied to its recent acquisitions and systems work.
Prosperity Bancshares' analyst story lines up around revenues of US$2.5b and earnings of US$1.1b by 2029, based on forecast yearly revenue growth of 21.1% and an earnings increase of about US$537.7m from current earnings of US$562.3m.
Uncover why Prosperity Bancshares' fair value indicates a 13% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The Simply Wall St Community currently offers 2 fair value views on Prosperity Bancshares, stretching from about US$81.54 to US$116.55 per share, which shows how far apart private investors can be. Set those gaps against live risks around loan growth and credit costs, then decide which narrative you think best fits the bank today.
Explore another Prosperity Bancshares fair value estimate, including one that suggests up to 62% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Prosperity Bancshares research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Prosperity Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Prosperity Bancshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond Prosperity Bancshares?
If you want to pressure test your view on Prosperity Bancshares, compare it with a wider watchlist built from companies that match the kind of risk, balance sheet strength, or upside potential you are comfortable with. The Simply Wall St Screener can help you quickly surface a focused set of alternatives.
- If you prefer stability first and foremost, with an emphasis on resilience and lower perceived risk, then scan our 29 resilient stocks with low risk scores to round out your defensive watchlist.
- If you are hunting for quality at what may be attractive prices, weigh Prosperity Bancshares against our 33 high quality undervalued stocks that filters for strong fundamentals at potentially appealing valuations.
- For readers who want income to play a bigger role, set Prosperity Bancshares alongside the high yield options in our 5 dividend fortresses and see which mix of payout and fundamentals you prefer.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com