


Dividend Raise Could Be A Game Changer For Sekisui Chemical Stock (TSE:4204)
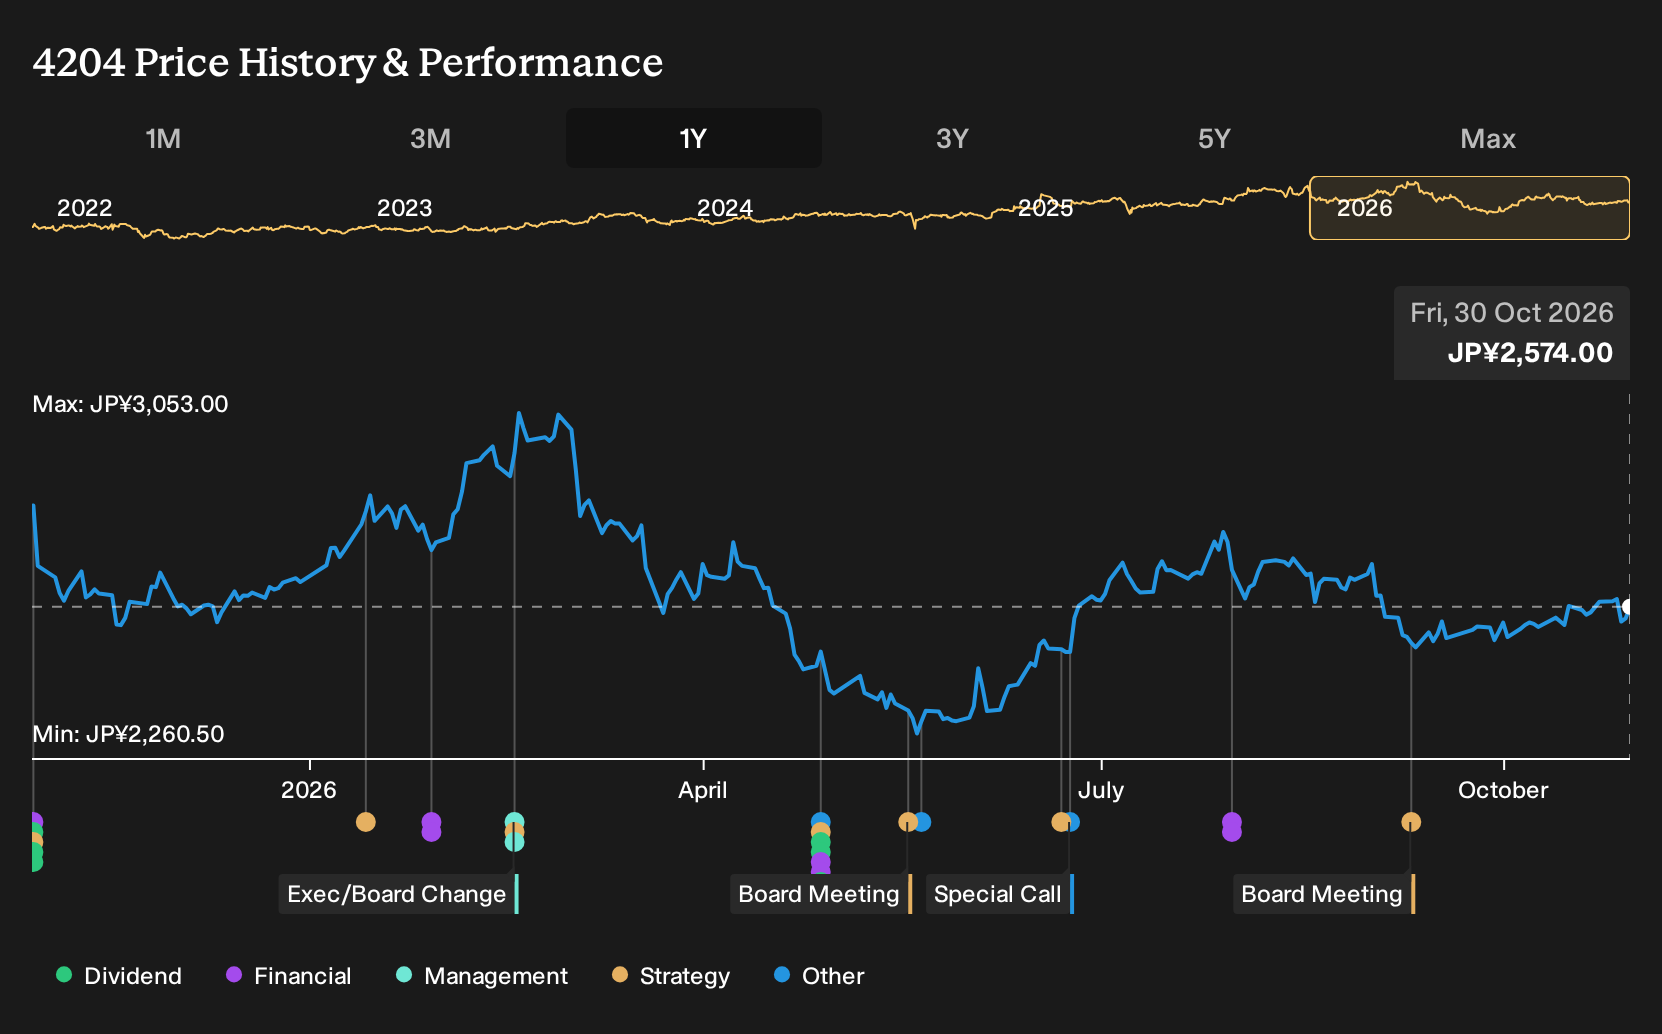
- Sekisui Chemical announced in October 2026 that it would pay an interim dividend of ¥41 per share, up from ¥40 a year earlier, and kept its Board approved payout and total return targets tied to its Accelerate 2028 capital allocation plan.
- The company paired this dividend move with higher full year net sales and operating profit forecasts, signaling confidence in demand for higher value added products despite what it still describes as uncertain market conditions.
- Next, the focus turns to how Sekisui Chemical's investment narrative absorbs this higher interim dividend and upgraded earnings guidance.
Scan how Sekisui Chemical’s richer interim dividend and updated earnings guidance stack up against peers by reviewing our curated list of 28 dividend fortresses
Sekisui Chemical Investment Narrative Recap
To hold Sekisui Chemical, an investor needs to believe the shift toward higher value housing, materials and infrastructure products can offset softer areas like mobility, smartphones and medical testing. The upgraded full year sales and operating profit forecast points to that mix shift still working, even as management keeps stressing uncertain demand.
In the near term, the key swing factor is execution on premium housing, perovskite solar and overseas infrastructure while keeping margins intact. The biggest risk remains end market weakness in Japanese housing, autos and electronics that could undercut that plan. The slightly higher interim dividend does not materially change those core drivers.
The most relevant update alongside the dividend decision is the revised fiscal 2026 outlook to ¥1,491,000m in net sales and ¥123,000m in operating profit. Those figures sit against the Accelerate 2028 plan, where management is trying to build earnings around high value housing, solar related materials and infrastructure renewal products.
For catalysts, that guidance leans on spreads holding up and better profitability from higher value products rather than volume recovery in weaker segments. The risk is that softer smartphone, auto and medical demand lingers longer than expected, which would pressure the High Performance Plastics and Medical units and test that higher payout commitment.
Sekisui Chemical's current analyst narrative points to revenues of ¥1.5819b and earnings of ¥99.8b by 2029, which assumes revenue grows at about 5.8% a year and requires earnings to rise by roughly ¥25b from ¥74.8b today.
Uncover why Sekisui Chemical's fair value indicates a 3% potential upside to its current price that could close sooner than many investors expect.
Exploring Other Perspectives
You can read the Sekisui Chemical story very differently. The most optimistic analysts treat the perovskite solar rollout as the real swing factor, not housing or smartphones. Before this dividend and guidance update, they were working off revenue of ¥1,626.0b and earnings of ¥101.5b by 2029. These views may shift once this new information is fully reflected, so compare both narratives to decide which interpretation you find more reasonable.
Explore 2 other Sekisui Chemical fair value estimates, including one that suggests as much as 20% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Sekisui Chemical research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sekisui Chemical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Sekisui Chemical's overall financial health at a glance.
Looking for more investment ideas beyond Sekisui Chemical?
Once you have a view on Sekisui Chemical, it helps to line it up against other opportunities so you can decide where your next yen of capital works hardest.
- If you care most about valuation and quality together, scan companies that screen well on both using our 16 high quality undervalued stocks.
- If balance sheet resilience matters to you, focus on businesses that combine low leverage with healthier fundamentals through this list of solid balance sheet and fundamentals (21 results).
- If you want to hunt for less followed opportunities, widen your search to a 69 high quality undiscovered gems that may not yet be widely tracked.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com