


Did China Securities Approval Just Shift Citigroup (C) Stock Narrative?
- Citigroup received approval from the China Securities Regulatory Commission to set up Citigroup Securities China Company Limited in Shanghai, giving it a wholly owned onshore platform for brokerage, underwriting, research and principal trading.
- The new securities arm lets Citigroup serve both domestic and foreign clients directly in China, widening its capital markets footprint across equities, bonds, funds and other local instruments in a single onshore hub.
- We will look at how Citigroup's China securities license, and broader onshore build out, feeds into the existing investment narrative.
Scan how Citigroup’s China push compares with other global banks by reviewing hand picked list of solid balance sheet and fundamentals (24 results) that could benefit from similar cross border expansion themes.
Citigroup Investment Narrative Recap
To own Citigroup, you need to be comfortable with a large, globally diversified bank that is working to turn a strong services franchise, AI adoption and simplification into steadier returns on capital. The key near term swing factor remains execution, particularly keeping Services and U.S. Cards healthy while managing credit quality and costs.
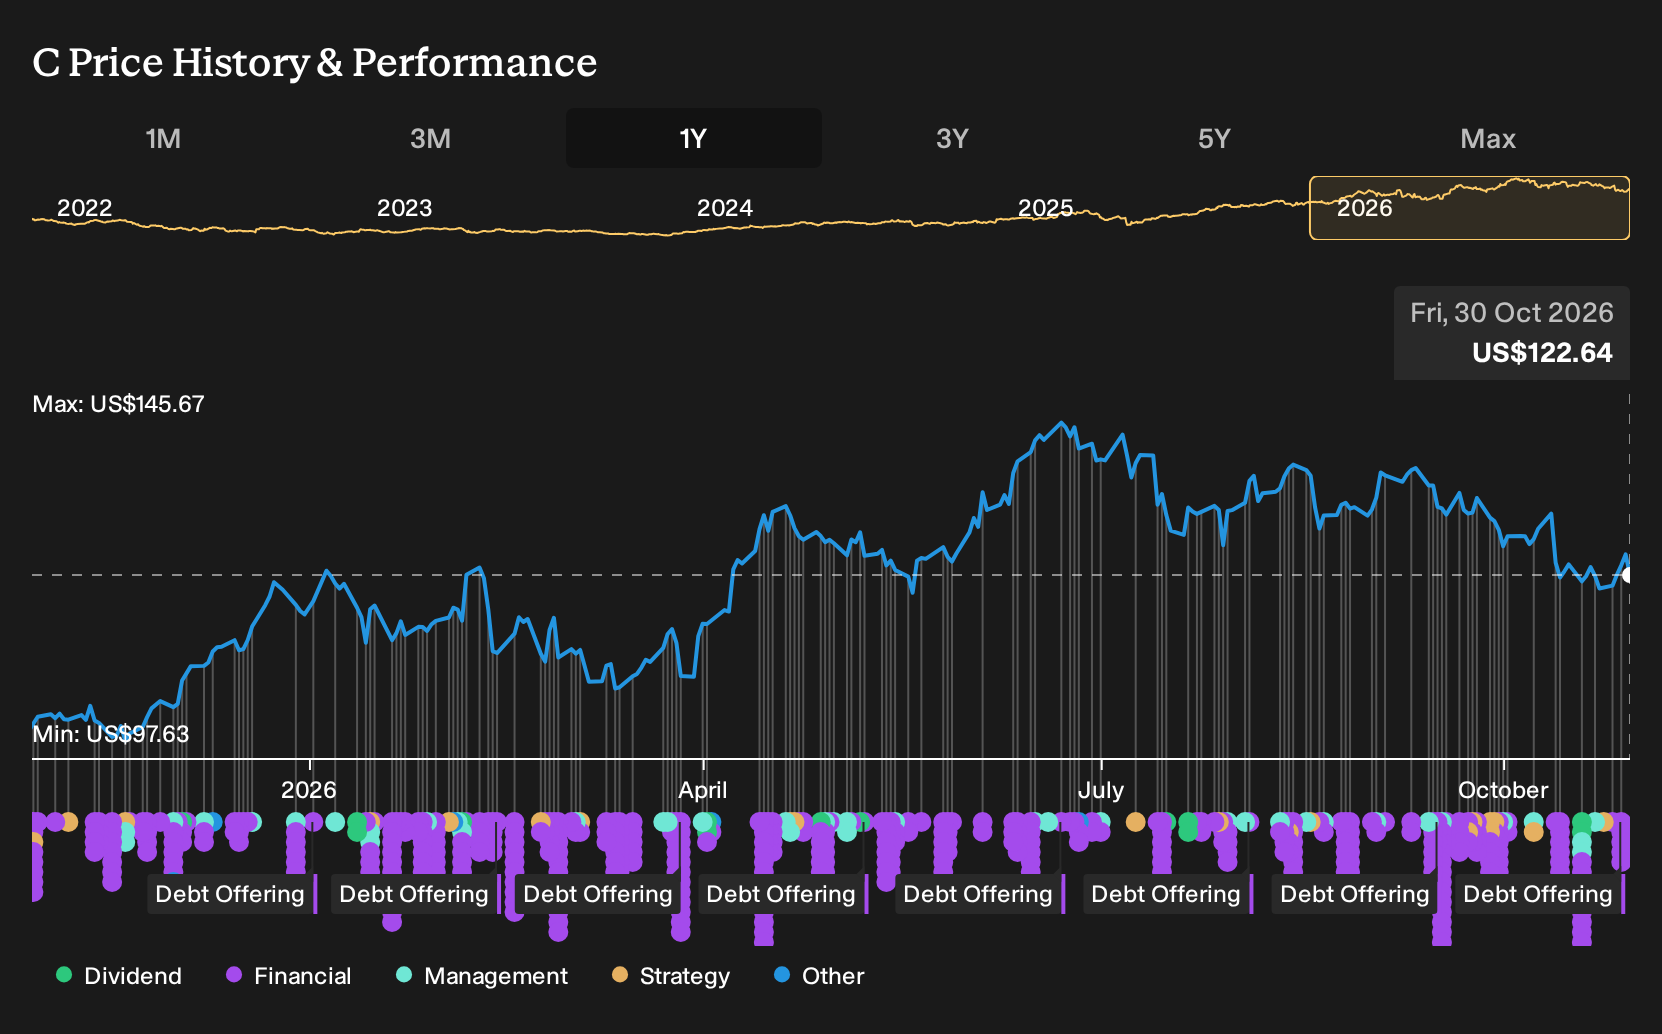
The recent stream of fixed income offerings and redemptions appears more like routine balance sheet management than a major shift. At this stage, these bond issues do not alter the main short term focus on earnings quality and capital deployment, or the largest risk related to regulatory and conduct events.
The most recent item that connects closely to Citigroup’s broader funding story is the cluster of new fixed income offerings in late October 2026, including multiple callable, senior unsecured notes across maturities from 2028 to 2046 and fixed to floating euro notes out to 2033. These instruments add term funding at defined coupons.
For you as a shareholder, the relevance is indirect. The way Citigroup manages maturities, coupons, and subordinated versus senior layers influences interest expense, capital ratios and flexibility around the planned Banamex IPO and share repurchases. Execution quality on this funding stack sits alongside credit discipline and controls as important moving parts for the outlook.
Citigroup China Build Out Through the Numbers
Citigroup's narrative projects US$108.8b revenue and US$22.4b earnings by 2029. This is consistent with analyst assumptions for 9.3% yearly revenue growth and an earnings increase of about US$4.5b from the current US$17.9b level.
Uncover why Citigroup's fair value indicates a 23% potential upside to its current price before the discount to Citigroup closes.
Exploring Other Perspectives
One alternate angle is that higher technology and compliance spending could eat into Citigroup’s China gains and recent bond funding moves. The most cautious analysts already worked off slightly lower revenue expectations of about US$107.2b and earnings near US$22.8b by 2029. Those views came before this approval, so you may see their narrative shift as fresh information filters through.
Explore 4 other Citigroup fair value estimates, including one that suggests it could be worth just $150.71!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own judgment.
- A great starting point for your Citigroup research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Citigroup. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Citigroup's overall financial health at a glance.
Looking For More Investment Ideas Beyond Citigroup?
Once you have a handle on Citigroup, it can help to widen the net and compare it with other businesses that share some of the qualities you value most, whether that is balance sheet strength, income potential, or lower risk profiles.
- If you care about financial resilience first, start with a list of solid balance sheet and fundamentals (24 results) that filters for companies with stronger balance sheets and fundamentals than the broader market.
- If income is your priority, scan a curated set of 5 dividend fortresses that may suit investors who want higher yields backed by more established cash flows.
- If you prefer potential mispricing opportunities, review a focused group of 33 high quality undervalued stocks that combine quality fundamentals with prices that analysts judge as not yet fully reflecting those strengths.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com