


Procter & Gamble (PG) Stock Still Looks Undervalued Despite Recent AI Buzz
Procter & Gamble has delivered a solid multi-year run, and recent enthusiasm around its earnings and technology push has kept attention firmly on the stock. The open question for investors is whether the current share price can be supported by the cash flows the business is expected to generate over time.
- Over the past 5 years, Procter & Gamble has returned 25.8%, which puts real weight on the issue of whether that share price performance lines up with its underlying cash flow profile.
- Recent earnings outperformance and management’s focus on agentic AI shopping may support expectations for how efficiently Procter & Gamble can convert its sales engine into future cash generation.
- If you'd rather focus on earnings, this one's for you. See why Procter & Gamble's 23.8x P/E tells a different valuation story.
The issue now is whether Procter & Gamble's current valuation is fully justified by its cash flows when assessed using a Discounted Cash Flow (DCF) view of intrinsic value.
If you are weighing Procter & Gamble against other ideas tied to AI and infrastructure, a focused screen of 54 AI infrastructure stocks.
Is Procter & Gamble Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model here takes Procter & Gamble’s future cash generation and discounts it back to today. On this view, the business is throwing off a sizeable amount of cash already, with latest twelve month free cash flow of about $15.8b. The projections behind the 2 Stage Free Cash Flow to Equity model assume that this cash pool keeps growing in a measured way over the next decade rather than swinging sharply up or down.
What matters for you is that these projected and discounted cash flows add up to an estimated intrinsic value that, according to the DCF, is meaningfully above the current share price of $161.57. Because fiscal first quarter earnings topped expectations and management is leaning into agentic AI shopping, the recent results help explain why the stock price has moved closer to what the cash flows point to, even if the model still indicates a gap. Find out what Procter & Gamble could be worth using our Discounted Cash Flow (DCF) estimate.
The Procter & Gamble Narrative: What Would Justify Today's Price?
Procter & Gamble's Simply Wall St Narratives sit on the Community page and pick up where the valuation puzzle leaves off. They map out which paths for future growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price. Where a single ratio or DCF output gives you one neat figure, the Narratives unpack the future that figure rests on, so you can monitor how reality lines up with it over time.
Community views on Procter & Gamble are split between modest upside from execution on AI and productivity programs and a stricter valuation perspective that sees limited room for error.
Bull case: 6% undervalued
"P&G is focusing on productivity improvements to mitigate cost pressures, including Supply Chain 3.0, unattended shifts and dark warehouses..."
Discover why this Narrative puts Procter & Gamble at 6% undervalued.
Bear case: 50% overvalued
"Overall it seems Procter & Gamble is overvalued at its current market price..."
Explore why this Narrative puts Procter & Gamble at 50% overvalued.
One more Procter & Gamble signal investors cannot ignore yet
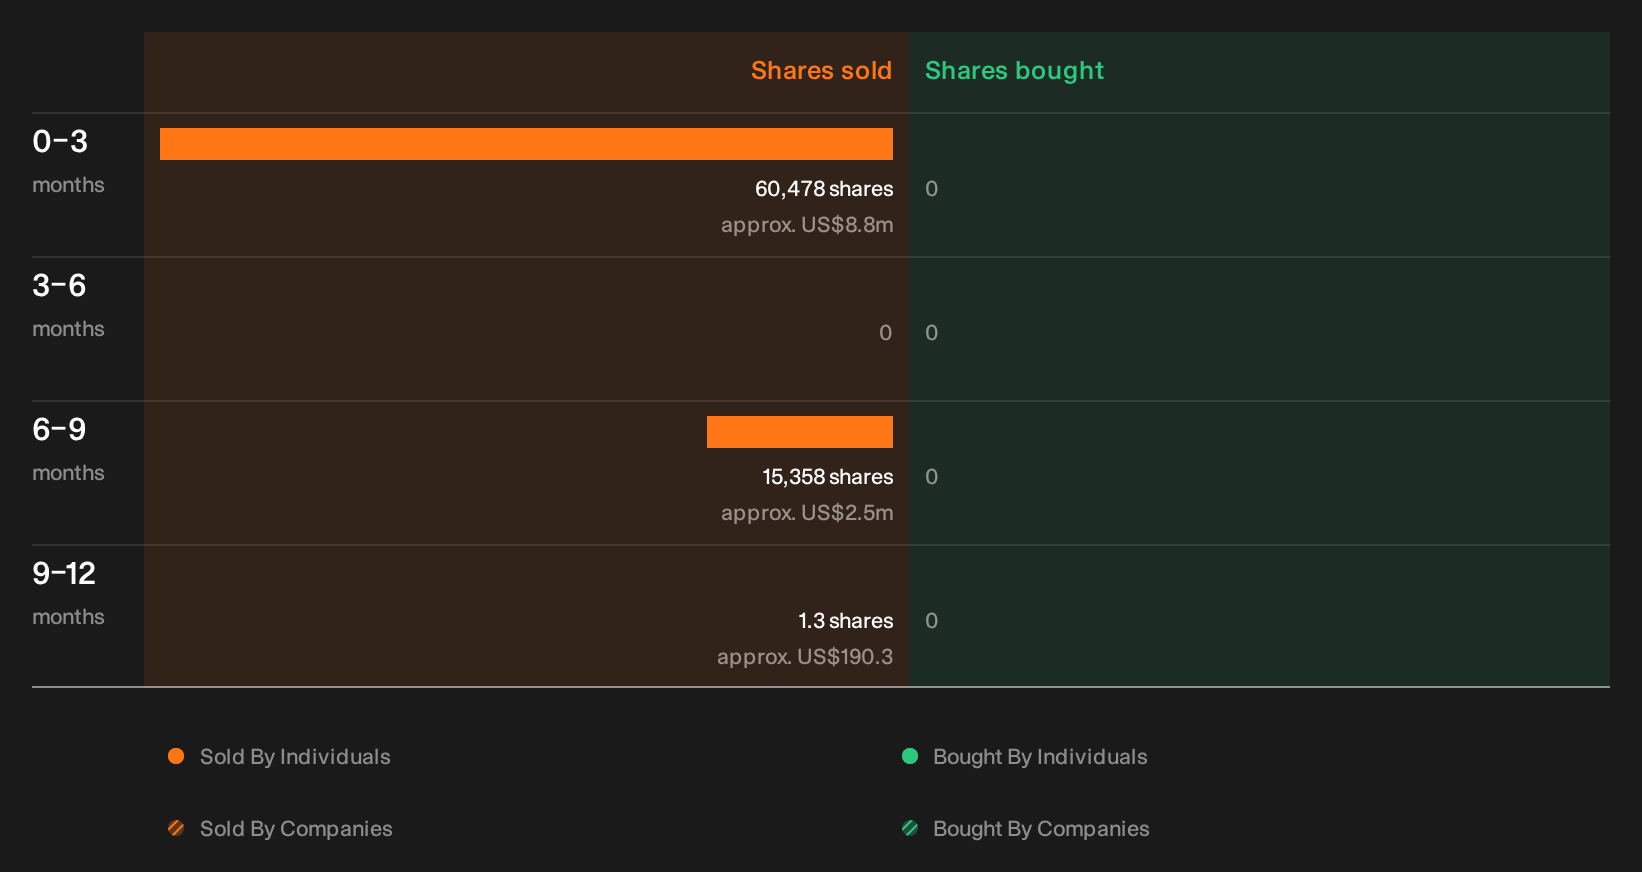
Before closing the file on Procter & Gamble, there is one loose thread that matters for anyone serious about ownership: the pattern of recent insider trades and what those transactions might suggest. See the recent insider selling flagged for Procter & Gamble.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com