


Castle Biosciences (CSTL) Dropped, So What Is Driving Attention Now?
How Castle Biosciences Stock Has Been Trading
Castle Biosciences (CSTL) has been moving on recent trading momentum rather than a single headline event, with the shares closing at US$37.16 and showing mixed returns across different time frames.
The stock is down about 3.6% over the past day but up roughly 12.3% over the past week and 4.5% over the past month, with a gain of 22.3% over the past 3 months.
Despite the pullback at US$37.16, Castle Biosciences has been experiencing firm positive momentum in recent weeks. The share price return year to date is slightly down, while the 1-year total shareholder return of 45.7% points to a much stronger longer-term picture.
Compare Castle Biosciences' recent momentum with a hand picked group of healthcare peers by scanning the 34 healthcare AI stocks for ideas riding similar trends.
Bulls point to Castle Biosciences' recent momentum and revenue growth, while bears focus on ongoing losses and the 5 year share price decline. Which story does the current valuation really tell?
Most Popular Narrative: 18% Undervalued
Castle Biosciences is trading at $37.16 against a widely followed narrative fair value of about $45.22, which frames the recent share price swings against a longer term story built on test volumes, reimbursement decisions and cash reserves.
Castle Biosciences is expanding its test menu into underpenetrated indications such as Barrett’s esophagus and atopic dermatitis, with TissueCypher volumes rising 63% to 14,988 reports in Q2 2026 and AdvanceAD-Tx orders progressing from about 650 in Q1 2026 to more than 1,000 in Q2 2026. This points to broader exposure to new patient groups and potential support for future revenue growth.
See why 4 investors see Castle Biosciences as 18% undervalued.
Result: Fair Value of $45.22 (UNDERVALUED)
Still, the Castle Biosciences story could shift quickly if Medicare coverage for DecisionDx SCC remains unresolved or if newer tests continue to pressure gross margins.
Find out about the key risks to this Castle Biosciences narrative.
Another View On Castle Biosciences Valuation
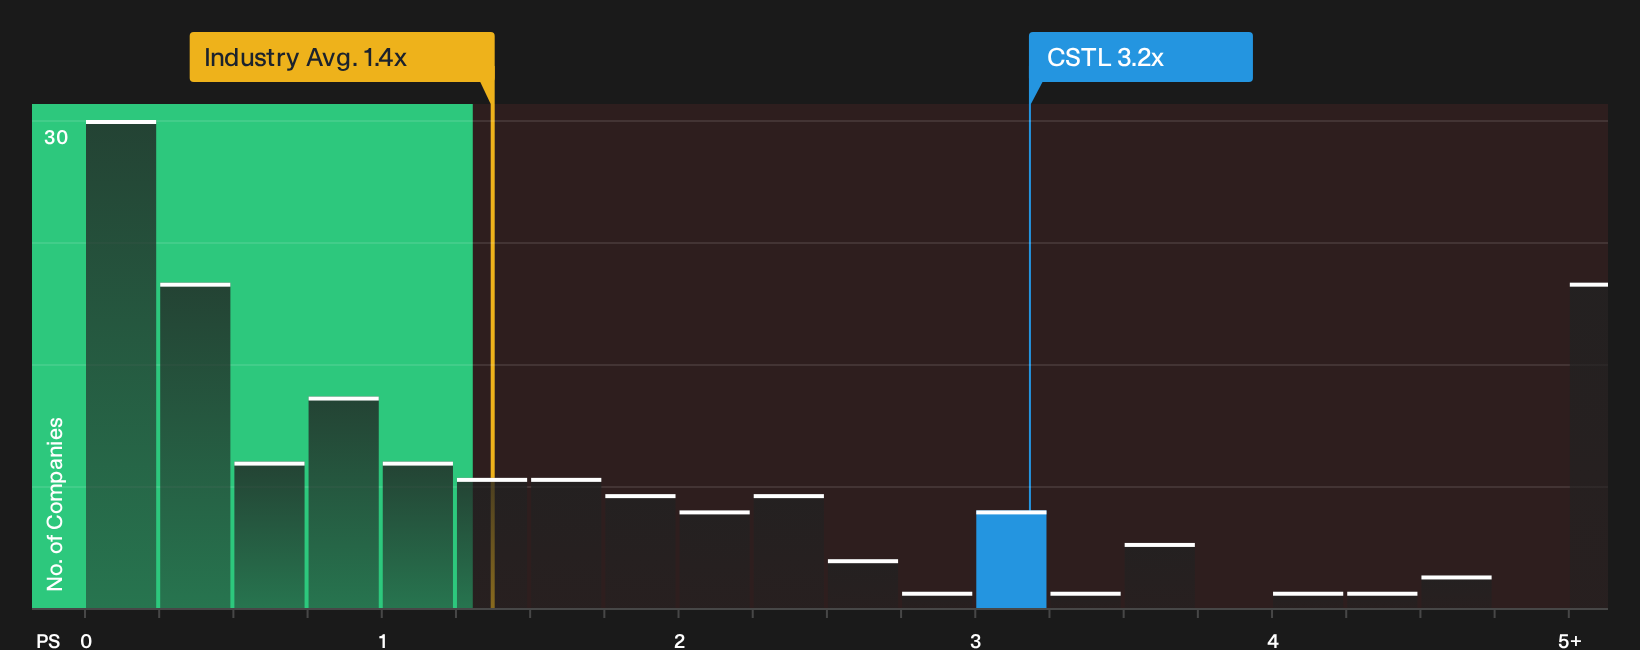
The earlier fair value of $45.22 leans on analyst forecasts and earnings power. A different lens looks at the current P/S ratio of 3.2x, which is more than double the US Healthcare average of 1.4x and above the 1x peer level, even though it is below a fair ratio of 3.6x.
That mix of rich pricing versus sector and peer groups, yet still below a fair ratio the market could move toward, raises a simple question for anyone following Castle Biosciences: Is this a premium story being priced reasonably, or a lot of expectation packed into one healthcare stock, with not much margin for disappointment, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Castle Biosciences so far, right. With both risks and potential rewards in play, now is the moment to dig into the underlying data and pressure test your own thesis using the 2 key rewards and 1 important warning sign.
Looking for more Castle Biosciences investment ideas?
If Castle Biosciences has sharpened your focus, broaden the lens and use powerful screeners to spot other stocks that might fit your playbook before the market does.
- Target quality at a discount by scanning a curated set of 33 high quality undervalued stocks that combine solid fundamentals with prices the market has not fully caught up with yet.
- Prioritize strength and resilience by reviewing a list of solid balance sheet and fundamentals (24 results) so you are not caught off guard by weak financial footing.
- Get ahead of the crowd by hunting through 19 high quality undiscovered gems that have strong metrics but limited attention from other investors so far.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com