


Nippon Yakin Kogyo (TSE:5480) Stock Q1 Results Clash With Weaker Trailing EPS
Traders came into this week already on the back foot with Nippon Yakin Kogyo down over the past month and quarter, sitting at ¥5,030 at Friday’s close. Then the company dropped its Q1 2027 scorecard. Basic earnings per share landed at ¥199.80 and net income reached ¥2,768 million, a punchy profit print for a specialty steel maker.
The twist is in the longer view. Trailing earnings now total ¥577.13 per share while the stock still trades on a single digit P/E and above an estimated discounted cash flow value. The real debate is not today’s tick-by-tick reaction; it is how durable this profit profile looks across the next few years.
Like the earnings power at Nippon Yakin Kogyo but worried that a low P/E and discounted cash flow gap could still mask risks to durability? You may want to review our curated list of solid performers with sturdy balance sheets in the list of solid balance sheet and fundamentals stocks (21 results)
Q1 2027 Earnings Summary
- Revenue (Q1 2027 vs. Q1 2026): ¥42,275 million vs. ¥39,199 million (up about 7.8%)
- Net Income (Excl. Extra Items, Q1 2027 vs. Q1 2026): ¥2,768 million vs. ¥1,988 million (up about 39.3%)
- Basic EPS (Q1 2027 vs. Q1 2026): ¥199.80 per share vs. ¥142.39 per share (up about 40.3%)
- Trailing 12 Month Basic EPS (Q1 2027 TTM vs. Q1 2026 TTM): ¥577.13 per share vs. ¥710.11 per share (down about 18.7%)
Earnings quality looks strong even as growth and margins slip. Ask Charlie what Nippon Yakin Kogyo’s low P/E might miss.
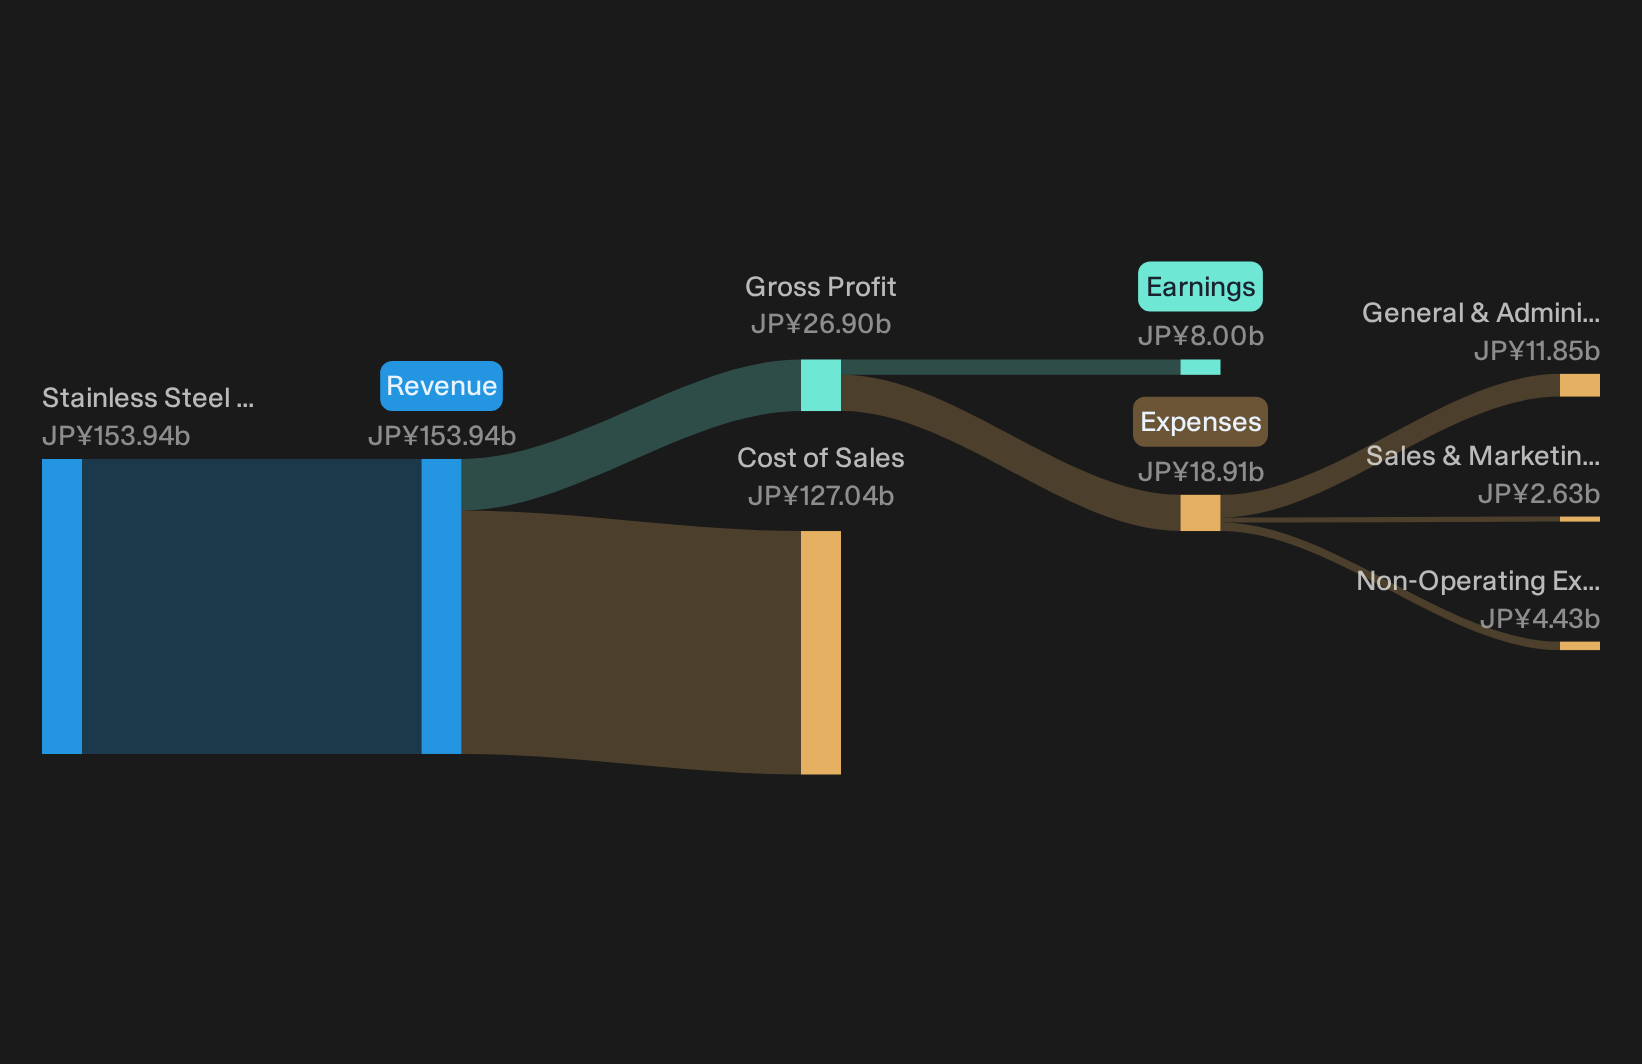
Earnings quality and Nippon Yakin Kogyo’s bullish hooks
Nippon Yakin Kogyo gives bulls something concrete to work with. Revenue in Q1 2027 is higher than the prior year period and net income excluding extra items climbs even faster, which points to healthier economics on current volumes. Basic EPS follows that pattern. For a business built around higher spec alloys, that combination of top line progress and stronger profit per share supports the idea that customers still pay for performance materials rather than treating the group like plain steel.
Where the Nippon Yakin Kogyo bear case still bites
The caution flag is the trailing 12 month EPS trend. That figure is below the prior year level, so the latest quarter has not yet repaired the drop in recent earnings power. Short term share price performance echoes that mixed picture, with the stock down over the past week, month and quarter. For a cyclical producer selling into capital goods and industrial spending, that pattern fits a more hesitant read on durability, even as the most recent quarter looks stronger on its own.
After a quarter like this, the obvious question is whether Nippon Yakin Kogyo’s weaker trailing EPS, debt coverage concerns and uneven dividend record hint at deeper structural issues. Review the independent risk analysis for Nippon Yakin Kogyo which shows 2 important warning signsHunt Quiet Disconnects In Japan
Nippon Yakin Kogyo reports a single quarter that raises questions about business durability. The real opportunity is in studying stocks that could be undervalued before the market closes the gap.
- Company 1 - 42% below our estimate - turns complex internal workflows into shared structured databases employees can update and search.
- Company 2 - 33% below our estimate - supplies photomasks enabling chip designers to adopt finer geometries and advanced packaging formats.
- Company 3 - 44% below our estimate - runs regional lending and fee-based services that connect borrowers, real estate clients and payment users.
Those are three of them. See the full list of 16 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com