


Makino (TSE:6135) Stock Price Slides Despite Strong Q1 Earnings
Makino Milling Machine shareholders have been reminded that precision engineering stocks can move in anything but a straight line. The share price closed at ¥2,917 on 30 October, leaving the stock down about 5% over the past week and roughly 10% lower across the past month, even as fresh Q1 2027 numbers hit the tape.
The headline result is simple. Quarterly net income reached ¥5,661m, with basic earnings per share at ¥48.40 and trailing twelve month EPS now at ¥217.23. Short term traders focused on the recent pullback. Longer term investors are more likely to focus on that earnings power against a P/E of 13.4x and a wide gap to the modelled cash flow value.
Like the earnings power at Makino Milling Machine but want more options on similarly priced industrials with strong cash generation? Compare this setup against our 16 high quality undervalued stocks
Q1 2027 Earnings Summary
- Revenue (Q1 2027 vs Q1 2026): ¥69,770 million vs. ¥55,397 million (up about 26%)
- Net Income (Excl. Extra Items, Q1 2027 vs Q1 2026): ¥5,661 million vs. ¥1,247 million (very large increase, more than 4x)
- Basic EPS (Q1 2027 vs Q1 2026): ¥48.40 per share vs. ¥10.66 per share (very large increase, more than 4x)
- Trailing 12 Month Net Income (Excl. Extra Items, Q1 2027 vs Q1 2026): ¥25,406 million vs. ¥12,426 million (up about 104%)
Tired of scrolling through dense paragraphs and raw earnings tables trying to piece together what Makino Milling Machine is really doing financially? Get the full picture of the business in clean, visual charts that lay out its valuation story at a glance in our company report for Makino Milling Machine.
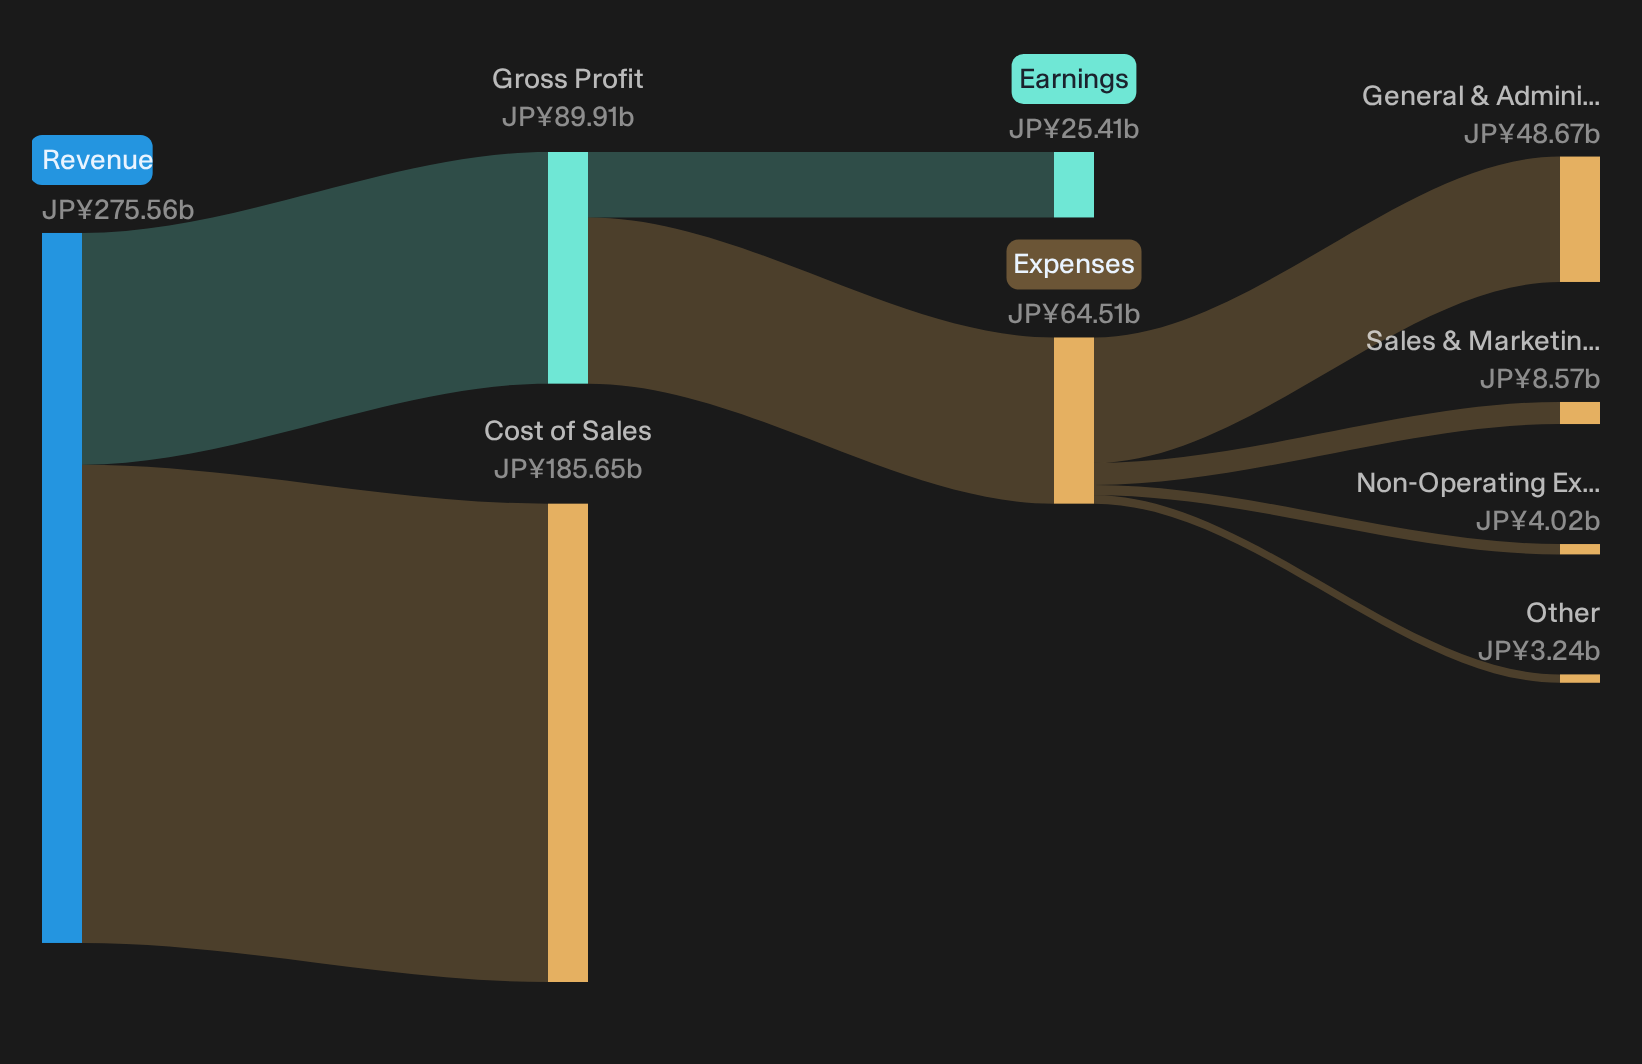
Makino bullish story leans on earnings power
For anyone leaning positive on Makino Milling Machine as a precision and automation play, the latest quarter helps that story. Revenue of ¥69,770 million and quarterly net income of ¥5,661 million both sit comfortably ahead of the prior year, while trailing 12 month profit of ¥25,406 million is roughly double the earlier period. That kind of step up in earnings capacity fits a view that Makino’s higher end machining and automation offerings are resonating with customers rather than just drifting with the cycle.
Short term setbacks keep Makino risk in focus
The cautionary side of the Makino Milling Machine narrative shows up in the share price tape rather than the income statement. The stock has fallen about 5% over the past week and roughly 10% across the past month, even as earnings and revenue move in a positive direction year on year. That disconnect keeps cyclical risk firmly on the table. It also suggests some investors are still treating Makino mainly as a capital goods cyclical, not fully crediting the precision and automation angle.
Are analysts treating Makino Milling Machine as a precision and automation story yet, or still a pure cyclical? Check the consensus price target analysis for Makino Milling Machine.Hunt For Mispriced Earnings Power
Makino Milling Machine shows how a solid earnings story can appear alongside a choppy share price. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 37% below our estimate - designs climate and utility systems developers use when retrofitting complex buildings for tighter efficiency and safety demands.
- Company 2 - 39% below our estimate - builds virtual performers corporations adopt when replacing traditional talent with always-on digital personalities for events and campaigns.
- Company 3 - 34% below our estimate - supplies precision films and electronic components device makers use when screens thin and sensors move into cars and factory equipment.
Three companies from the same screener. Open the full list of 16 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com