


CCI Group (TSE:7381) Q1 Earnings Recovery Meets Questions Over Staying Power
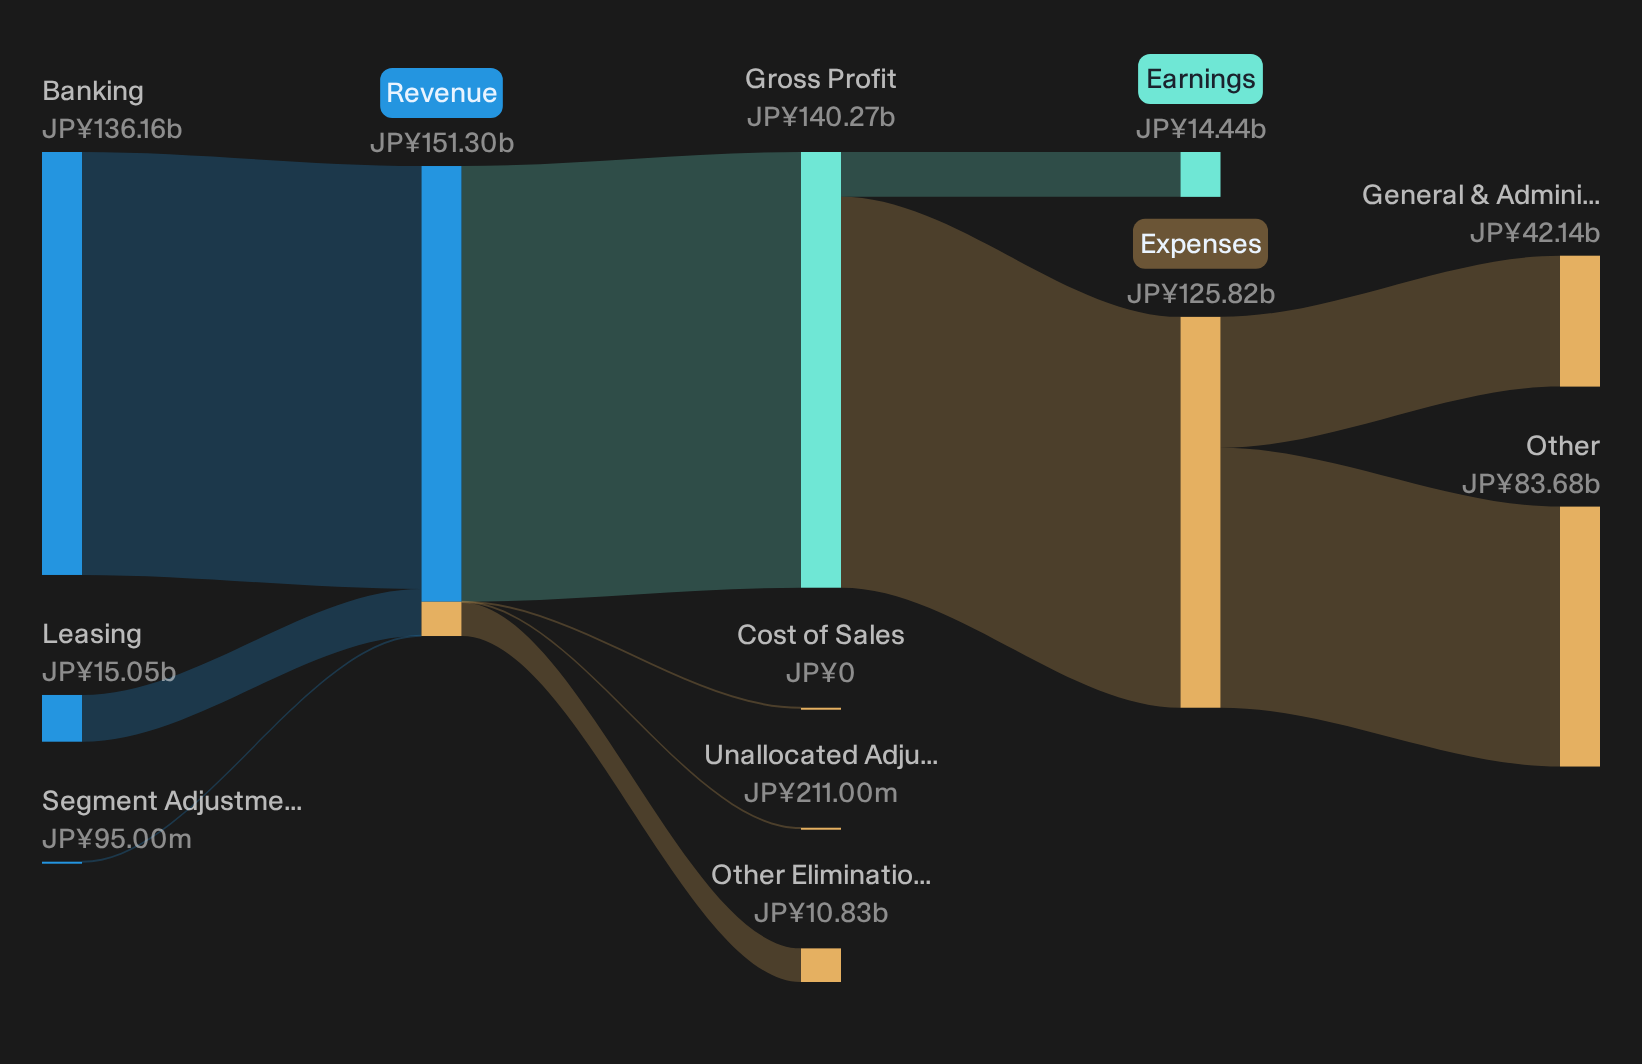
CCI Group stock closed at ¥1,130 on Friday, roughly flat over the past week after a choppy month that left shorter term traders unimpressed. Yet the Q1 2027 earnings release tells a different story. Basic earnings per share came in at ¥33.85 and net income reached ¥7,521m, a solid rebound from the small loss reported in Q4 2026. The gap between a muted share price and this earnings reset puts the focus squarely on the bigger question for you as an investor: how durable this profit recovery really is over the coming years.
Impressed by CCI Group’s quick earnings rebound but uneasy about how steady that recovery might be? Compare this setup with a curated list of companies screened for resilient balance sheets and consistent fundamentals in our list of solid balance sheet and fundamentals stocks (21 results).
Q1 2027 Earnings Summary
- Revenue (Q1 2027 vs Q1 2026): ¥22,415m vs. ¥21,682m (up about 3.4%)
- Net Income (Q1 2027 vs Q1 2026): ¥7,521m vs. ¥5,709m (up about 31.8%)
- Basic EPS (Q1 2027 vs Q1 2026): ¥33.85 vs. ¥25.15 (up about 34.6%)
- Total Loans (Q1 2027 vs Q1 2026): ¥3,219,585m vs. ¥2,973,825m (up about 8.3%)
Earnings are up, but CCI Group trades above its DCF and peers. Ask Charlie what justifies CCI Group’s premium valuation.
CCI Group earnings reset supports cautious optimism
For a business often seen as a steady regional platform, CCI Group’s latest quarter gives the bullish story some real backing. Revenue is higher year on year while net income and basic EPS move up at a much faster clip, which suggests earnings quality rather than just volume growth. Total loans now sit at ¥3,219,585m, above last year’s level, so the lending engine still matters. Combined with a rebound from the Q4 loss, the recovery argument looks directionally consistent with a patient, income oriented thesis.
Short term volatility keeps risk questions alive
The bear story does not disappear. A 30 day share price decline of about 15.9% alongside flat performance over the past week shows investors are still cautious even after the earnings rebound. Loan expansion of roughly 8.3% over 12 months can raise questions about future credit costs for a regional lender if conditions weaken. The sharp swing from a small loss in Q4 2026 to solid profit in Q1 2027 also invites scrutiny of how smooth earnings might be over a full cycle rather than just one strong quarter.
After a quarter that flips from a small loss to solid profit, it is fair to ask whether loan growth and a low bad loan allowance are early hints of deeper stress or just noise. Before assuming the Q1 rebound settles the risk story for CCI Group, review an independent risk analysis for CCI Group which shows 5 important warning signs to see if this is only the visible part of a larger problem.Hunt For Quiet Mispricings Now
CCI Group shows how earnings and share prices do not always move together. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 36% below our estimate - manages complex infrastructure builds for logistics, transport, and public facilities with long term tenant and municipal reliance. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 2 - 41% below our estimate - expands multi service auto hubs where drivers complete purchases, inspections, repairs, and insurance in a single visit. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 3 - 21% below our estimate - supplies high spec connectors embedded inside vehicles, smartphones, and industrial equipment that customers rarely redesign after qualification. The real opportunity is finding stocks that could be undervalued before the market corrects them.
Those are three of them. See every one of the 16 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com