


Earnings Beat Could Be A Big Deal For CNO Financial Group Stock (CNO)
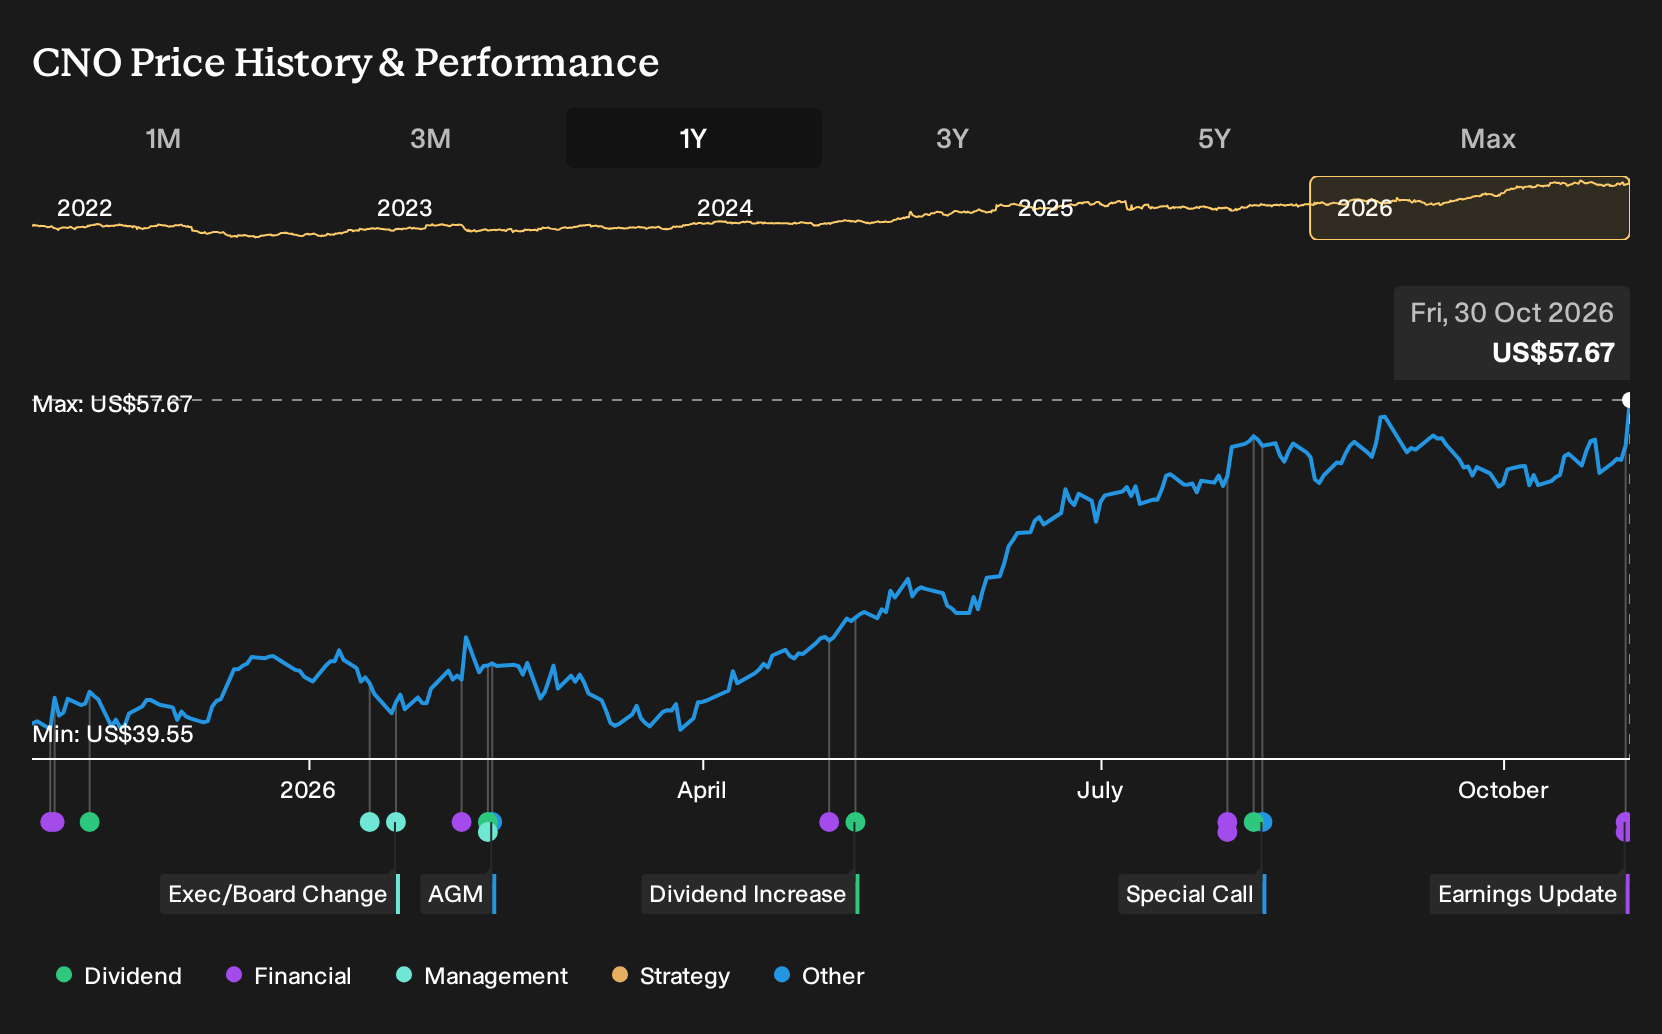
- CNO Financial Group reported third quarter 2026 revenue of US$1,086 million and net income of US$161.1 million, with diluted earnings per share from continuing operations of US$1.71, and raised full year 2026 operating EPS guidance after a 47% rise in operating EPS to US$1.90.
- The insurer paired its earnings jump with a US$270 million life reserve transfer to its Bermuda reinsurance affiliate, which freed up capital while leaning into a middle income retirement focus built on Medicare Supplement momentum and a growing captive agent force.
- We will now look at how CNO Financial Group's investment narrative could be influenced by the raised full year operating earnings guidance.
CNO Financial Group Investment Narrative Recap
To own CNO Financial Group, you need to believe the insurer can keep turning its middle income retirement niche, captive agents and Medicare Supplement focus into steady operating earnings. The raised 2026 operating EPS guidance, alongside higher reported net income for both the quarter and year to date, supports that execution story in the near term.
The key short term swing factor is whether margin gains and Medicare Supplement repricing hold up as disruption in Medicare Advantage evolves. The main operational risk is that premium growth again slows toward historical trends while technology spending stays heavy, which would put pressure on earnings progress implied by the upgraded guidance.
The most relevant announcement for this earnings print is CNO Financial Group lifting its 2026 operating EPS guidance midpoint by 9%. That revision sits on top of a 47% rise in third quarter operating EPS to US$1.90 and sharply higher reported net income, which together highlight how current pricing, mix and expense control are flowing into profits.
For investors, the higher guidance tightens the focus on execution around captive distribution, Medicare Supplement repricing and the US$170m technology modernization program. Any stumble on agent productivity, benefit ratios or expense discipline would make it harder to sustain the operating earnings profile that management signals for the rest of 2026.
CNO Financial Group's analyst narrative points to revenues of US$4.1b and earnings of US$550.1m by 2029, based on a forecast 4.1% yearly decline in revenue and an earnings increase of about US$270.5m from US$279.6m today.
Uncover why CNO Financial Group's fair value indicates a 7% potential downside to its current price, leaving little room for error.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CNO Financial Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CNO Financial Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CNO Financial Group's overall financial health at a glance.
Looking for more investment ideas beyond CNO Financial Group?
Once you have formed a view on CNO Financial Group, it can help to compare that thesis with other businesses filtered for the qualities you care about most, whether that is value, resilience or income potential.
- If you prefer quality at a discount and want a starting list that filters for strong fundamentals and appealing valuations, take a look at 33 high quality undervalued stocks.
- If capital preservation matters more to you than aiming for very high returns, you might appreciate a focus on stability through the 29 resilient stocks with low risk scores.
- Income focused investors who care about consistency and payout strength can use the 5 dividend fortresses to anchor a watchlist around yield.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com