


ATI Could Be 33% Below Fair Value On Raised 2026 Guidance
ATI (ATI) is back in focus after its third quarter 2026 earnings update, where management reported higher sales, stronger profitability across aerospace and defense, and raised full year guidance for the third time.
ATI’s third quarter update landed against a backdrop of sharp price swings, with the share price down 5.38% on the day to US$165.59 and 1 month and 3 month share price returns also lower. However, the year to date share price return of 38.92% and a 1 year total shareholder return of 67.31% indicate that longer term momentum remains firmly positive.
Spot similar aerospace and defense momentum stories by scanning our hand-picked 19 high quality undiscovered gems, which echo ATI’s mix of specialty materials exposure and earnings surprise potential.ATI has delivered strong earnings, raised guidance again, and still trades at a discount to analyst targets after a sharp pullback. Is the meaningful upside ahead of investors or already priced in?
Most Popular Narrative: 33% Undervalued
ATI is trading at $165.59, while the most followed narrative anchors fair value at about $248.89. This puts the story firmly in undervalued territory based on those assumptions and a discount rate of 8.16%.
Global defense spending needs in areas like naval nuclear, missiles, missile defense and armor intersect with ATI's materials and process positions. The roughly US$1b multi year naval nuclear contract through 2030, which more than doubles annual revenue versus the prior agreement with a large uplift from price and mix, can support higher defense revenue and structurally stronger margins.
See why 20 investors see ATI as 33% undervalued.
Result: Fair Value of $248.89 (UNDERVALUED)
Still, the story can unravel if overseas customers lean harder into local suppliers, or if ATI’s industrial and medical demand stays weaker for longer.
Find out about the key risks to this ATI narrative.
Another View: ATI Through The P/E Lens
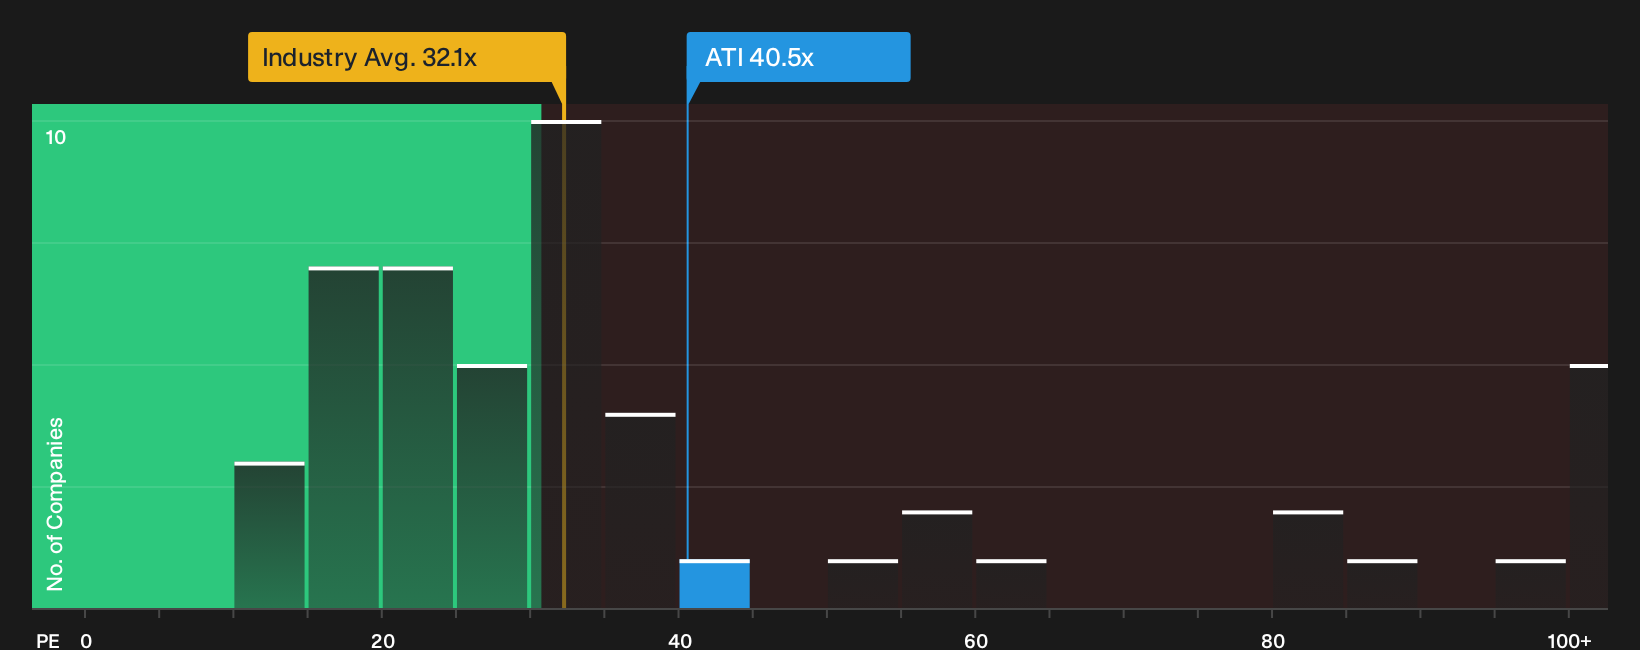
ATI might look attractive against analyst fair value estimates, yet the current P/E of 40.5x is well above the US Aerospace & Defense average of 32.1x and the 30.2x fair ratio. That richer multiple can mean less room for error if growth expectations cool.
It is worth asking whether this valuation premium reflects ATI’s quality and growth profile, or whether the market could drift closer to that fair ratio over time. That shift would pressure returns even if earnings progress as expected, especially for investors buying after a strong multi year share price run.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around ATI can stir plenty of debate, so move quickly, pull up the numbers, and weigh both the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond ATI?
ATI is only one story. Fresh ideas often come from scanning wider, so do not leave the rest of the market on the table.
- Target resilient cash generators with healthy finances by checking companies in the list of solid balance sheet and fundamentals (24 results) that pair balance sheet strength with solid fundamentals.
- Hunt for mispriced opportunities by reviewing the 30 high quality undervalued stocks that combine quality metrics with attractive valuations before the crowd turns its attention.
- Build a steadier income stream by reviewing the 5 dividend fortresses where higher yields meet a focus on sustainability and financial robustness.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com