


China Mobile (SEHK:941) Stock Looks About Right After A 134% Run
China Mobile has delivered a long stretch of gains for shareholders, and that kind of track record naturally raises a question about whether the current share price is still supported by its earnings power. With the stock now trading around HK$80.0, the key issue is how that price lines up against what the business earns today and what it may reasonably earn over time.
- Over the past 5 years, China Mobile has returned 134.0%, which puts real pressure on the current valuation to be underpinned by solid and durable profits.
- The group’s role as a large telecom operator means earnings are closely tied to how efficiently it turns network investment into recurring cash flows, which can affect how much investors are willing to pay for each dollar of profit.
- There is a second opinion on China Mobile worth weighing. See what analysts think China Mobile's shares could be worth.
The stock’s next move may depend on whether those earnings are strong and resilient enough to support today’s price tag.
If you are weighing China Mobile against other earnings focused ideas, it can help to compare the current setup with 197 high quality undervalued stocks that also clear quality hurdles.
Is China Mobile Fairly Priced on Earnings?
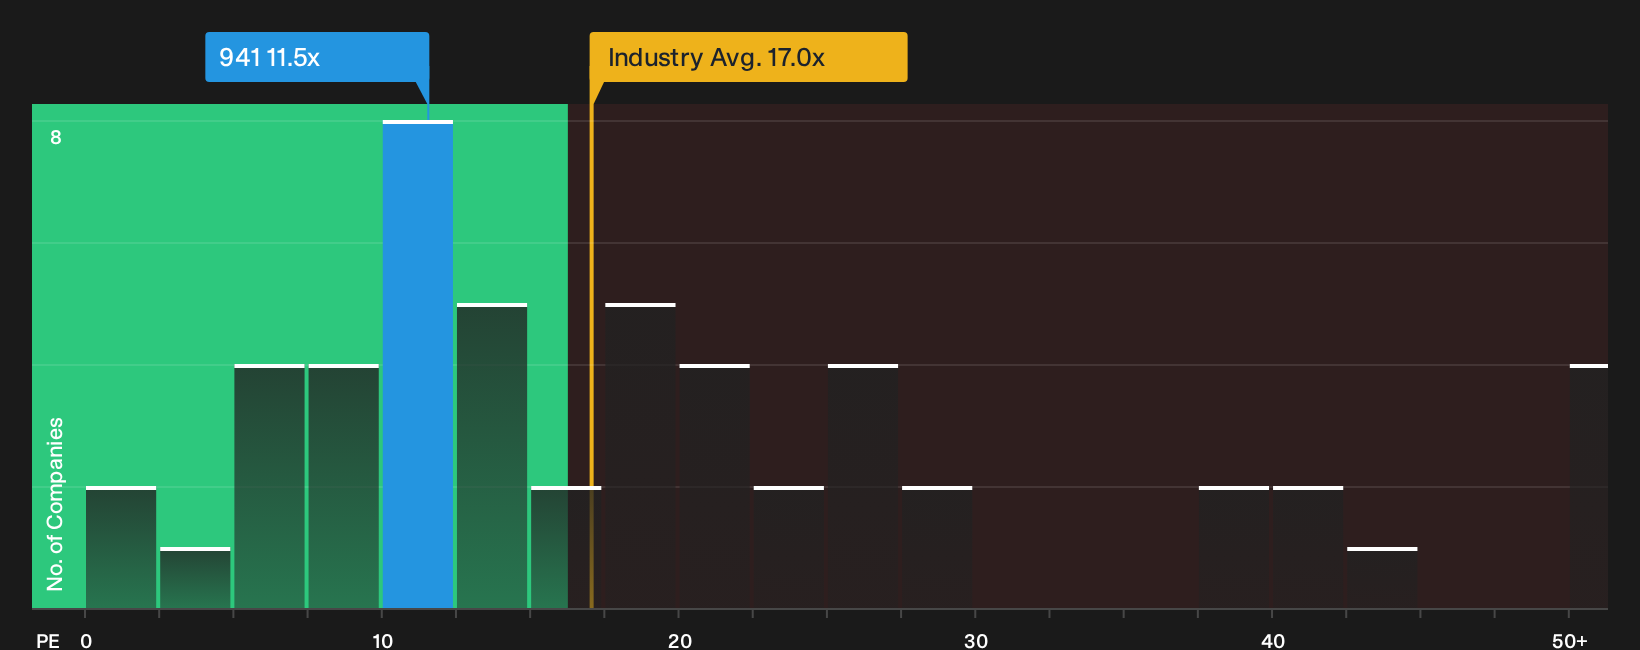
The P/E ratio works well for a mature telecom like China Mobile because profits tend to be the main driver of long term value. On this lens, the stock trades on about 11.5x earnings, which is below the Wireless Telecom industry average of roughly 14.9x and well under the broader peer group at about 23.7x. That gap indicates the market is pricing China Mobile on a lower earnings multiple than many comparable operators.
The fair multiple from the model, which reflects China Mobile’s own growth profile, margins, scale and risk level rather than broad sector norms, comes out very close to where the shares currently trade. As a result, the present P/E does not clearly indicate that the stock is overvalued or undervalued on this framework and places more emphasis on how you assess the quality and durability of its earnings stream. Explore the numbers behind China Mobile's P/E valuation.
The China Mobile Narrative: What Would Justify Today's Price?
Narratives on China Mobile pick up where the valuation puzzle leaves off and spell out which earnings, margin and growth paths would need to play out for the current P/E to look either too low or too rich. Each narrative then links its implied value to a specific view on how China Mobile's growth prospects, profitability and risk profile might evolve, giving you a reference point you can revisit as new information emerges.
One of the top community narratives on China Mobile: 33% undervalued
"China Mobile Limited remains the world’s largest telecommunications operator by subscriber base and a leading integrated provider of communications, computing, and AI services..."
Discover why this Narrative puts China Mobile at 33% undervalued.
One more China Mobile piece that can change the picture
Price tags and profit multiples only tell part of the story for China Mobile. The people setting priorities and how they are rewarded can tilt long term outcomes in very different directions. See who runs China Mobile and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com