


DiamondRock Hospitality (DRH) Following Its Portfolio Focus Shift Looks Close To Fair Value
DiamondRock Hospitality (DRH) has drawn fresh attention after a recent share price move, with the stock closing at US$14.25. Investors are assessing this hotel REIT’s performance over the recent month and across its past 3-month return figures.
Recent trading tells a mixed story. The share price return declined 1.45% over the last session yet still shows a 13.37% gain over 30 days and a 56.25% share price return year to date. At the same time, the 1 year total shareholder return of 89.47% and 3 year total shareholder return of 87.93% hint that investors have been reassessing both DiamondRock Hospitality’s income potential and risk profile over time.
Compare DiamondRock Hospitality’s recent momentum with a curated group of real estate players by scanning the list of solid balance sheet and fundamentals (24 results) that may better balance upside and resilience.
Bulls point to DiamondRock Hospitality’s strong recent shareholder returns and sizeable discount to estimated intrinsic value, while bears flag slowing profit growth. Which side do the current valuation numbers support more?
Most Popular Narrative: 2% Overvalued
Against the last close at $14.25, the most followed narrative pegs DiamondRock Hospitality’s fair value at $14.04, which leaves the stock trading at a small premium once that 8.32% discount rate is applied.
The refreshed thesis on DiamondRock Hospitality shifts the focus from an expected broad recovery in travel demand to a tighter emphasis on higher ADR assets, disciplined capital recycling, and a stronger balance sheet, while reaffirming the core view that the company’s portfolio and operating approach can support resilient earnings power over time.
See why 2 investors see DiamondRock Hospitality as 2% overvalued.
Result: Fair Value of $14.04 (OVERVALUED)
Still, rising labor costs in New York and tougher asset recycling conditions could pressure DiamondRock Hospitality’s hotel margins and reduce the payoff from its reinvestment program.
Find out about the key risks to this DiamondRock Hospitality narrative.
Another View: DiamondRock Hospitality Through Earnings Multiples
The first fair value estimate for DiamondRock Hospitality comes from a narrative and analyst price target framework that points to the stock trading about 2% above that $14.04 mark. A very different picture appears when you look at earnings multiples.
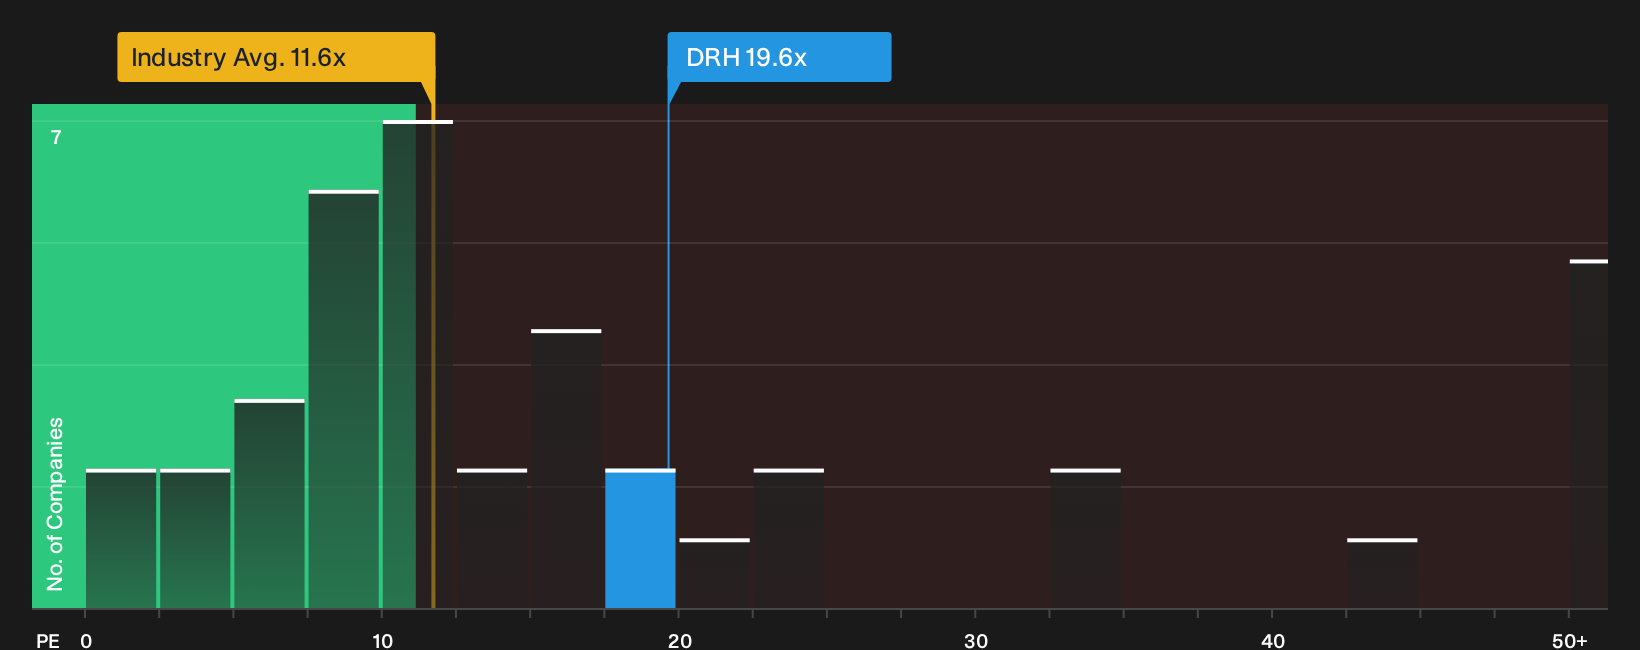
On a P/E of 19.6x, DRH screens expensive versus the global Hotel and Resort REITs average of 11.6x. Yet it looks inexpensive beside peer levels at 73.1x and a fair ratio of 29.2x that the market could move toward. That mix of discount and premium raises a simple question. Is this multiple signaling upside that justifies the risk or warning you to be careful about what you pay for recent performance?
Our valuation work digs into that trade off in more detail. It is worth seeing what the numbers imply before deciding how much room is left in the current P/E set up. See what the numbers say about this price — find out in our valuation breakdown.
For readers who want a visual snapshot of how DiamondRock Hospitality compares against its sector on this metric today, the following chart provides a clear side by side on valuation.
Next Steps
Mixed signals can feel confusing, especially when DiamondRock Hospitality shows both appealing rewards and flagged risks at the same time. Act while the information is fresh and pressure test the thesis for yourself by reviewing the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond DiamondRock Hospitality?
Do not stop with DiamondRock Hospitality. Broaden your watchlist now with a few targeted stock ideas that match different risk levels and income goals.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive entry points through the 30 high quality undervalued stocks.
- Build a more dependable income stream by reviewing higher yielding payers screened as 5 dividend fortresses.
- Dial down portfolio stress by focusing on financially resilient businesses highlighted in the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com