


Tyler Technologies (TYL) Could Be 128% Overvalued On Strong Q3 And AI Wins
Tyler Technologies (TYL) just reported third quarter results that included higher revenue, earnings per share, and net income, along with record free cash flow and increasing recurring and SaaS contributions to the business.
The latest results have shifted sentiment around Tyler Technologies, with the share price up 5.45% on the day of the report and showing a 22.15% 1 month share price return, even though the year to date share price return is still down 9.53% and the 1 year total shareholder return has fallen 17.21%. This points to momentum rebuilding recently after a tougher stretch for longer term holders.
Scan how Tyler Technologies fits into the broader software and AI trend by comparing it against 39 AI small caps, which are also leaning into recurring revenue and cloud-first models.
Tyler Technologies’ sharp rebound now sits between two stories. Recent results and AI wins suggest the fundamentals are doing the heavy lifting. At the same time, the longer term share price record points to a sentiment reset that valuation now needs to justify.
Most Popular Narrative: 128% Overvalued
At a last close of $394.30, Tyler Technologies is set against a widely followed fair value estimate of $172.63 that, according to Esteban, implies the current price is far above what the business fundamentals support under that framework.
Tyler Technologies is the dominant software platform for U.S. state and local government, a market defined by mission-critical workflows, 12 to 24 month implementation cycles, and a procurement environment that structurally protects incumbents. The investment thesis is built on three compounding forces: (1) a largely complete SaaS cloud transition that is converting a high-gross-margin subscription base from flat to accelerating, with ARR already at $2.06B and growing 11% annually; (2) a payments platform (NIC) that turns Tyler’s 40,000+ client relationships into a recurring transaction revenue stream now generating $808M per year and growing at double digits; and (3) a Tyler 2030 strategic roadmap that articulates a credible path to 30%+ non-GAAP operating margins by the end of the decade.
See why 8 investors see Tyler Technologies as 128% overvalued.
Result: Fair Value of $172.63 (OVERVALUED)
Still, the Tyler Technologies story can be knocked off course if the shift from on-premises to cloud slows further, or if stock-based compensation continues to pressure free cash flow quality.
Find out about the key risks to this Tyler Technologies narrative.
Another View On Tyler Technologies’ Valuation
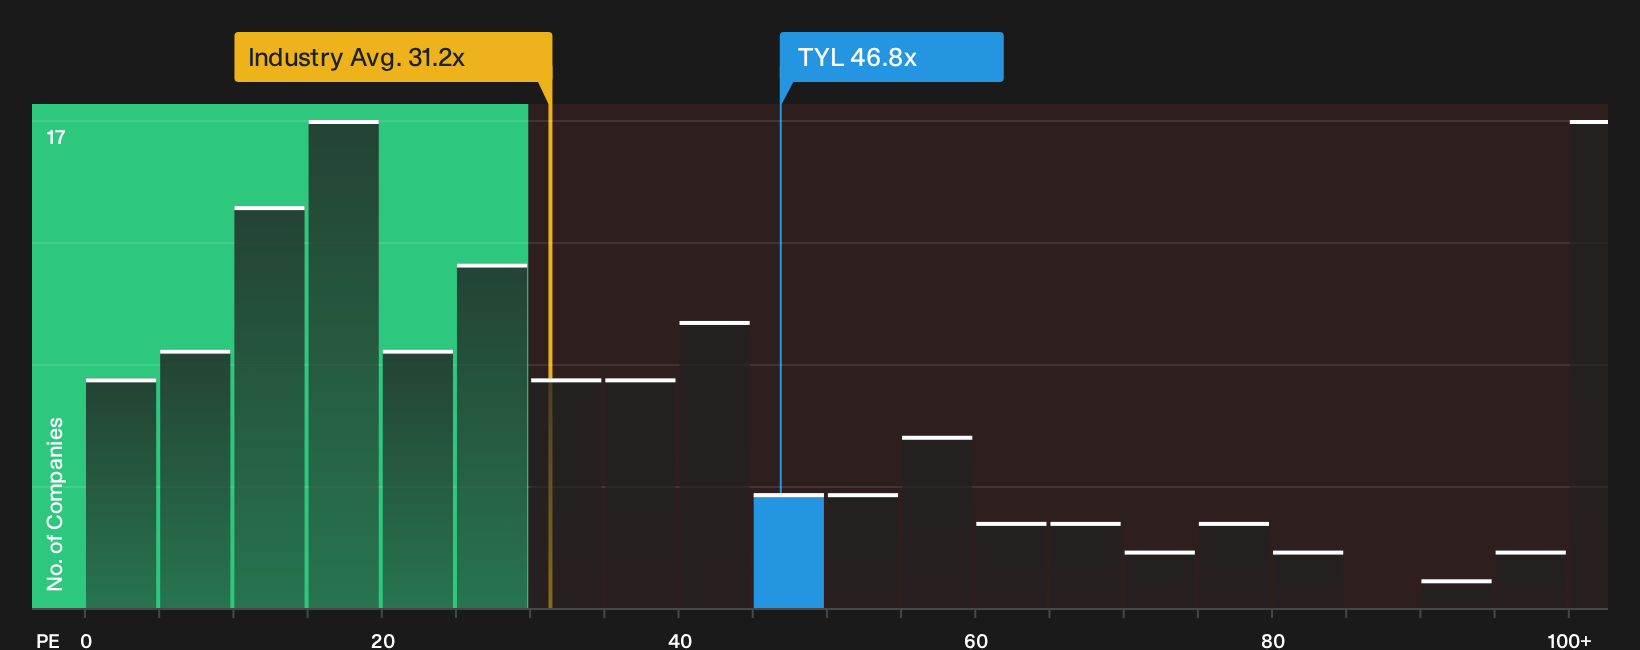
While Esteban’s narrative points to Tyler Technologies trading well above a fair value of $172.63, the preferred P/E lens tells a more mixed story. The stock sits on a 46.8x P/E, which is cheaper than direct peers at 57.2x, yet richer than the US software group at 31.2x.
The fair ratio sits at 30.9x, so current pricing leans well above where the market could drift if enthusiasm cools. For investors weighing upside against downside risk, the question is whether Tyler Technologies’ quality justifies staying north of that fair ratio for long.
To stress test that view, it helps to see what the numbers imply across different valuation checks, not just one P/E snapshot. This is where See what the numbers say about this price — find out in our valuation breakdown..
For a clearer picture of how Tyler Technologies’ current P/E compares with its sector and this fair ratio, review the side by side comparison in
Next Steps
Sentiment in this article has leaned toward caution, so treat it as a prompt to test the figures yourself and act early on your own judgement. To see what is driving optimism on Tyler Technologies right now, review the 3 key rewards.
Looking for more investment ideas beyond Tyler Technologies?
If Tyler Technologies has sharpened your thinking, do not stop there. Fresh ideas often come from comparing it with very different opportunities uncovered by focused screeners.
Use the Simply Wall St screener to quickly surface other stocks that fit clear, targeted themes before the crowd gets interested.
- Target potential mispricings by scanning a curated list of 30 high quality undervalued stocks that pair solid fundamentals with prices the market has not fully embraced yet.
- Prioritise resilience first by filtering for 29 resilient stocks with low risk scores that may help steady your portfolio when volatility picks up again.
- Hunt for fresh stories by checking 19 high quality undiscovered gems where strong financials have not yet attracted mainstream attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com