


Why Everyone Is Watching CRH (CRH) Right Now
What CRH's latest earnings signal for shareholders
CRH (NYSE:CRH) just delivered third quarter 2026 figures that paired higher revenue with weaker profitability, as rising energy, haulage, and raw material costs pushed management to trim full year profit targets.
CRH's latest update landed as the share price has climbed 10.82% over the past month, yet still fallen 28.18% on a year to date share price return. The 5 year total shareholder return of 100.33% shows a much stronger longer term picture as the market weighs lower guidance against the new Arcosa deal, dividend increase, and fresh US$6b buyback plan.
Scan how investors are pricing CRH's margin pressure and capital returns against peers by reviewing our curated list of 30 high quality undervalued stocks in similar sectors.
Margin pressure is still biting even as CRH shares have bounced. After this mix of weaker guidance and bigger buybacks, does the current valuation still leave more upside than downside for new money?
Most Popular Narrative: 26% Undervalued
CRH last closed at $90.81 against a narrative fair value of $122.72, which frames the current weakness against a longer runway tied to infrastructure and reindustrialization demand.
The ongoing rollout of U.S. federal infrastructure funding, with management expecting around 40% of IIJA highway funds still unspent at the end of 2026 and referencing the proposed BUILD America 250 Act authorizing an additional US$580b for transportation programs, points to a multiyear pipeline of public works that can support CRH revenue, order backlog and earnings.
See why 31 investors see CRH as 26% undervalued.
Result: Fair Value of $122.72 (UNDERVALUED)
Still, the CRH story can change quickly if public infrastructure funding slows, or if the planned Arcosa acquisition and integrations deliver weaker cash returns than expected.
Find out about the key risks to this CRH narrative.
Another View: What CRH's P/E Says
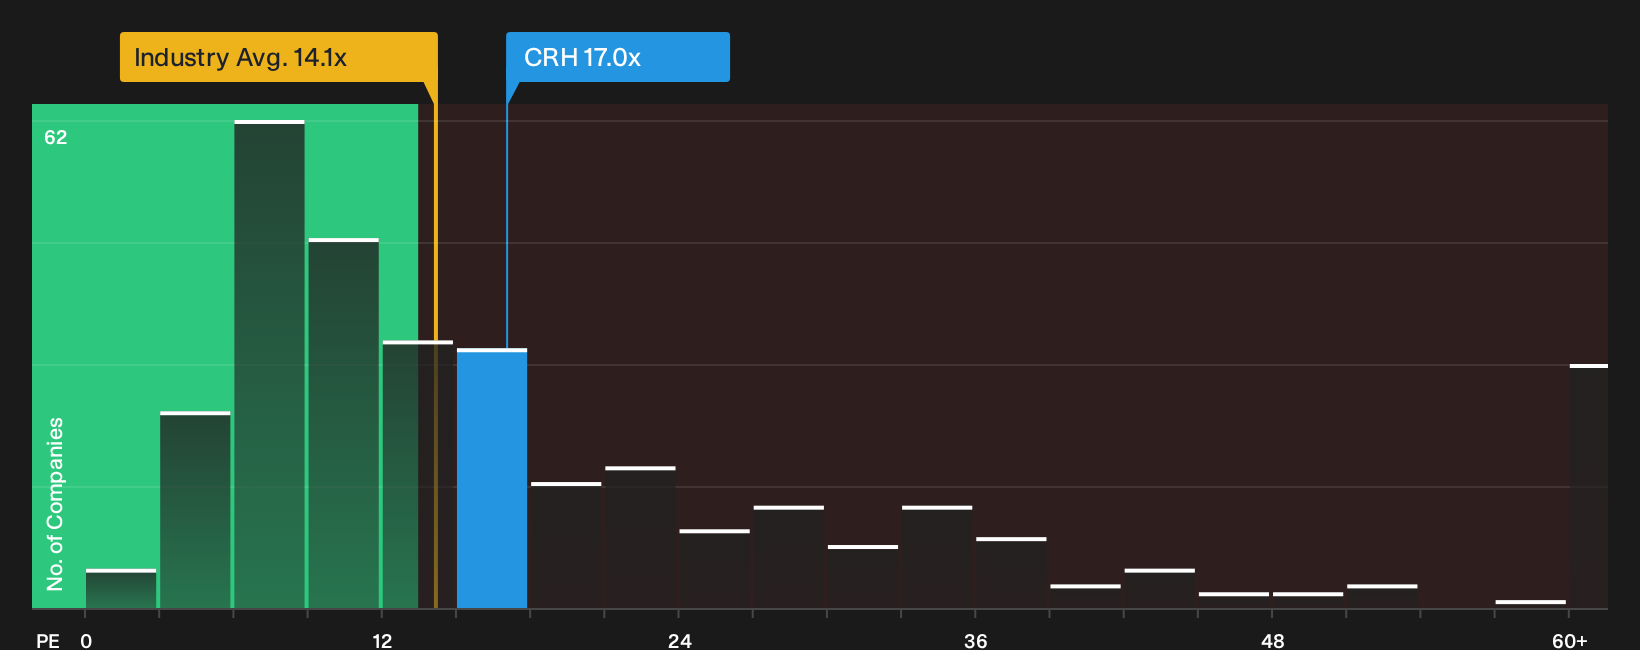
The SWS DCF model points to value upside for CRH, yet the plain P/E picture is less generous. At about 17x earnings, the stock trades above the Global Basic Materials group on 14.1x, even though the internal fair ratio sits higher at 22.3x.
That spread means investors are paying more than the wider industry but less than what the fair ratio suggests the market could move toward if sentiment and earnings line up. The question is whether you see that gap as a margin of safety or as a signal that expectations are already baking in a lot of good news.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on CRH so far, with buybacks, dividends and margin strain all pulling in different directions. Make your own call before sentiment shifts and weigh up the 5 key rewards and 1 important warning sign.
Looking for more CRH-sized investment ideas?
If CRH has you rethinking where you put fresh capital, do not stop at one ticker. Broader research now can save a lot of second guessing later.
- Spot potential mispricing early and scan a curated 30 high quality undervalued stocks that line up strong balance sheets with solid cash generation.
- Build a portfolio that works harder for you by reviewing a focused 5 dividend fortresses offering yields that may help support your income goals.
- Sleep easier through market swings by filtering for a 29 resilient stocks with low risk scores that score well on resilience and financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com