


Black Diamond Group (TSX:BDI) Lifted Its Dividend On Strong Q3 Revenue, Is It Still A Bargain?
Black Diamond Group (TSX:BDI) is back in focus after reporting Q3 2026 results that showed higher year-over-year revenue and a 22% increase to its quarterly dividend, along with active Workforce Solutions demand.
At a share price of CA$21.11, Black Diamond Group has seen strong momentum build in recent months, with a 7-day share price return of 13.13% and a 90-day move of 20.56%. The 1-year total shareholder return of 42.72% and very large 5-year total shareholder return highlight how earlier investors have been rewarded.
Scan how Black Diamond Group compares to other companies rewarding shareholders with rising cash flows and dividends by reviewing the hand picked 3 dividend fortresses.Black Diamond Group has already rewarded investors who were in before the recent surge, and the fresh dividend lift adds another layer of appeal. Does it still make sense to commit capital at today’s price, or is patience the better move?
Most Popular Narrative: 8% Undervalued
Against the last close of CA$21.11, the most followed narrative points to a fair value of CA$22.96. As a result, the discussion tilts toward upside potential that depends heavily on recurring rental and lodging cash flows holding up over time.
Growing contracted rental revenue of $142.5 million in Q1 2026 and $136.5 million in Q2 2026, alongside 16% to 17% rental revenue growth over the same period, points to Black Diamond Group steadily expanding its recurring rental and lodging base, which can support more predictable revenue and earnings.
See why 12 investors see Black Diamond Group as 8% undervalued.
Result: Fair Value of CA$22.96 (UNDERVALUED)
Still, compressed earnings from lower margin lodging and higher interest costs, alongside bid conversion risk in Workforce Solutions, could quickly weaken the narrative for Black Diamond Group.
Find out about the key risks to this Black Diamond Group narrative.
Another View: What Black Diamond Group’s P/E Is Telling You
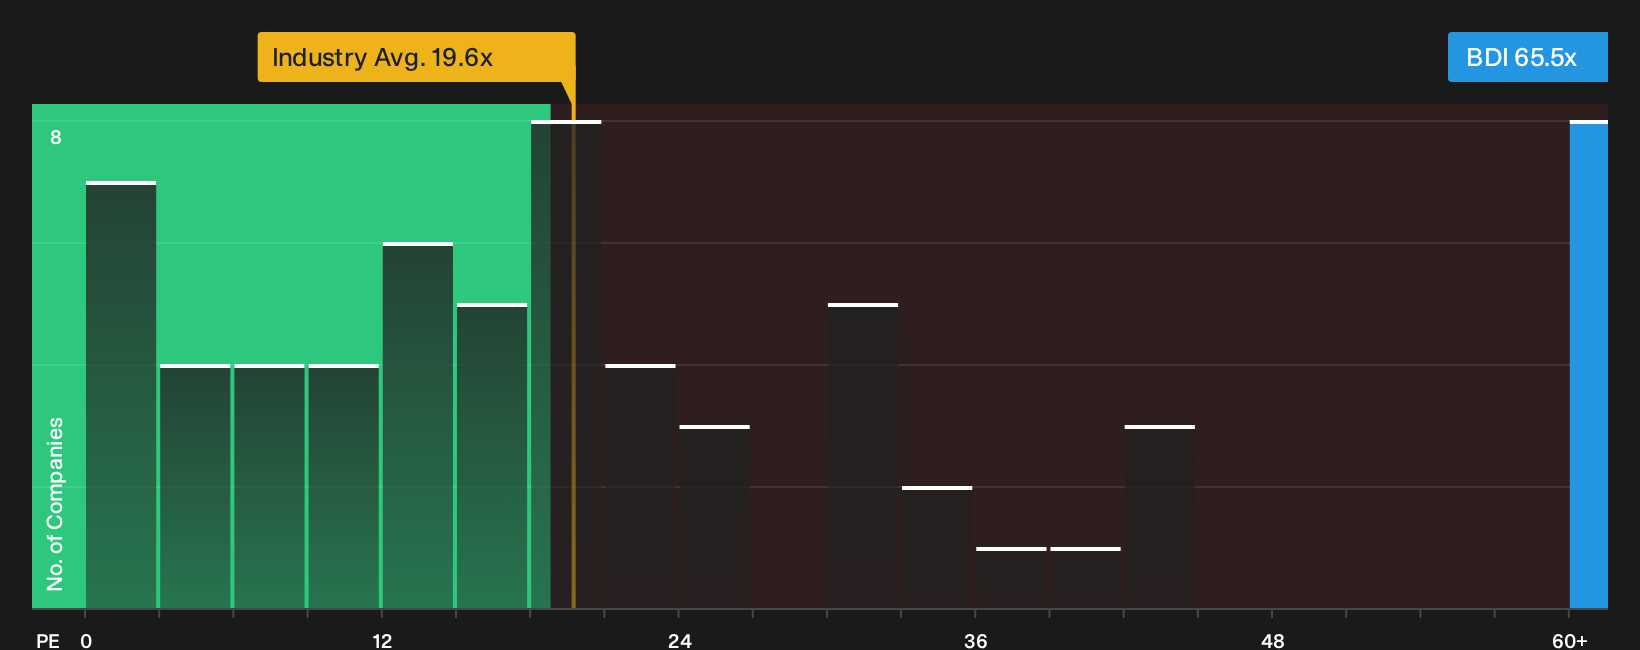
Analysts see upside to CA$22.96, yet on simple earnings multiples Black Diamond Group looks expensive. The stock trades on a P/E of 65.5x, compared with 19.6x for the wider Commercial Services group and 37.9x for peers, while the fair ratio is 31.6x. Is the market paying too much for the growth story?
Those richer valuations point to meaningful downside risk if sentiment cools or earnings fall short of expectations, since the P/E could drift closer to the fair ratio or even the sector average over time. It is therefore worth stress testing what needs to go right for that premium to hold.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on value and risk can make Black Diamond Group hard to pin down, so consider acting promptly, review the numbers yourself, and weigh both sides. To round out that view, it is worth checking the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Black Diamond Group?
If you are serious about building a stronger portfolio, do not stop at one stock. Use fresh screeners to uncover ideas that match your risk and income goals.
- Target resilient cash generators by scanning a 4 high quality undervalued stocks that combines robust fundamentals with pricing that still looks restrained.
- Prioritise staying power and sleep-at-night balance sheets by reviewing a list of solid balance sheet and fundamentals (6 results) tailored to financially healthier businesses.
- Hunt for potential future market favourites before the crowd arrives by checking a 8 high quality undiscovered gems built around quality metrics, not hype.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com