


Are Weaker Earnings Altering The Investment Case For PulteGroup (PHM)?
- PulteGroup reported third quarter 2026 results, with revenue of US$3,973.85 million and net income of US$475.73 million, alongside lower earnings per share than a year earlier.
- The nine month figures show revenue of US$11,365.38 million and net income of US$1,294.73 million, highlighting how earnings power and pricing are being tested against affordability pressures and product mix choices.
- We will now look at how PulteGroup's investment narrative lines up with the softer third quarter revenue trend and earnings step down.
Scan how PulteGroup's latest earnings reset compares with other housing and construction plays by reviewing our hand picked list of solid balance sheet and fundamentals (24 results) for potential alternatives in the same pressure zone.
PulteGroup Investment Narrative Recap
PulteGroup appeals to investors who believe its mix shift toward higher priced move up and active adult buyers, along with tighter cost control and disciplined land use, can support earnings quality even when volumes and pricing are under pressure. The latest quarter showed softer revenue and lower earnings per share, which keeps the focus firmly on execution rather than expansion.
The key short term swing factor is how effectively PulteGroup manages affordability, incentives and community mix while demand remains uneven across regions like the West. The biggest risk is that weak homebuyer appetite and heavy incentives persist, keeping margins compressed. The latest results reinforce this risk, but do not fundamentally change it.
The most relevant information for this earnings reset is the prior context of double digit active adult order growth earlier in 2026 and the push toward a higher share of build to order sales. Those initiatives are designed to tie more homes to specific buyers and lean on communities with stronger pricing, which can cushion earnings when closings soften.
In that light, the current report reads as a test of whether PulteGroup's product mix and cost discipline can offset pressure from affordability and regional softness, rather than a change in direction. For you as a shareholder or potential shareholder, the question is whether this operational playbook, including incentives around 10% to 11%, still looks durable given the revenue and profit step down year on year.
PulteGroup's current analyst framework points to revenues of US$17.0b and earnings of US$1.9b by 2029, building on earnings today of US$1.8b. That setup relies on projected revenue growth of 2.0% per year and an earnings increase of US$0.1b over that period.
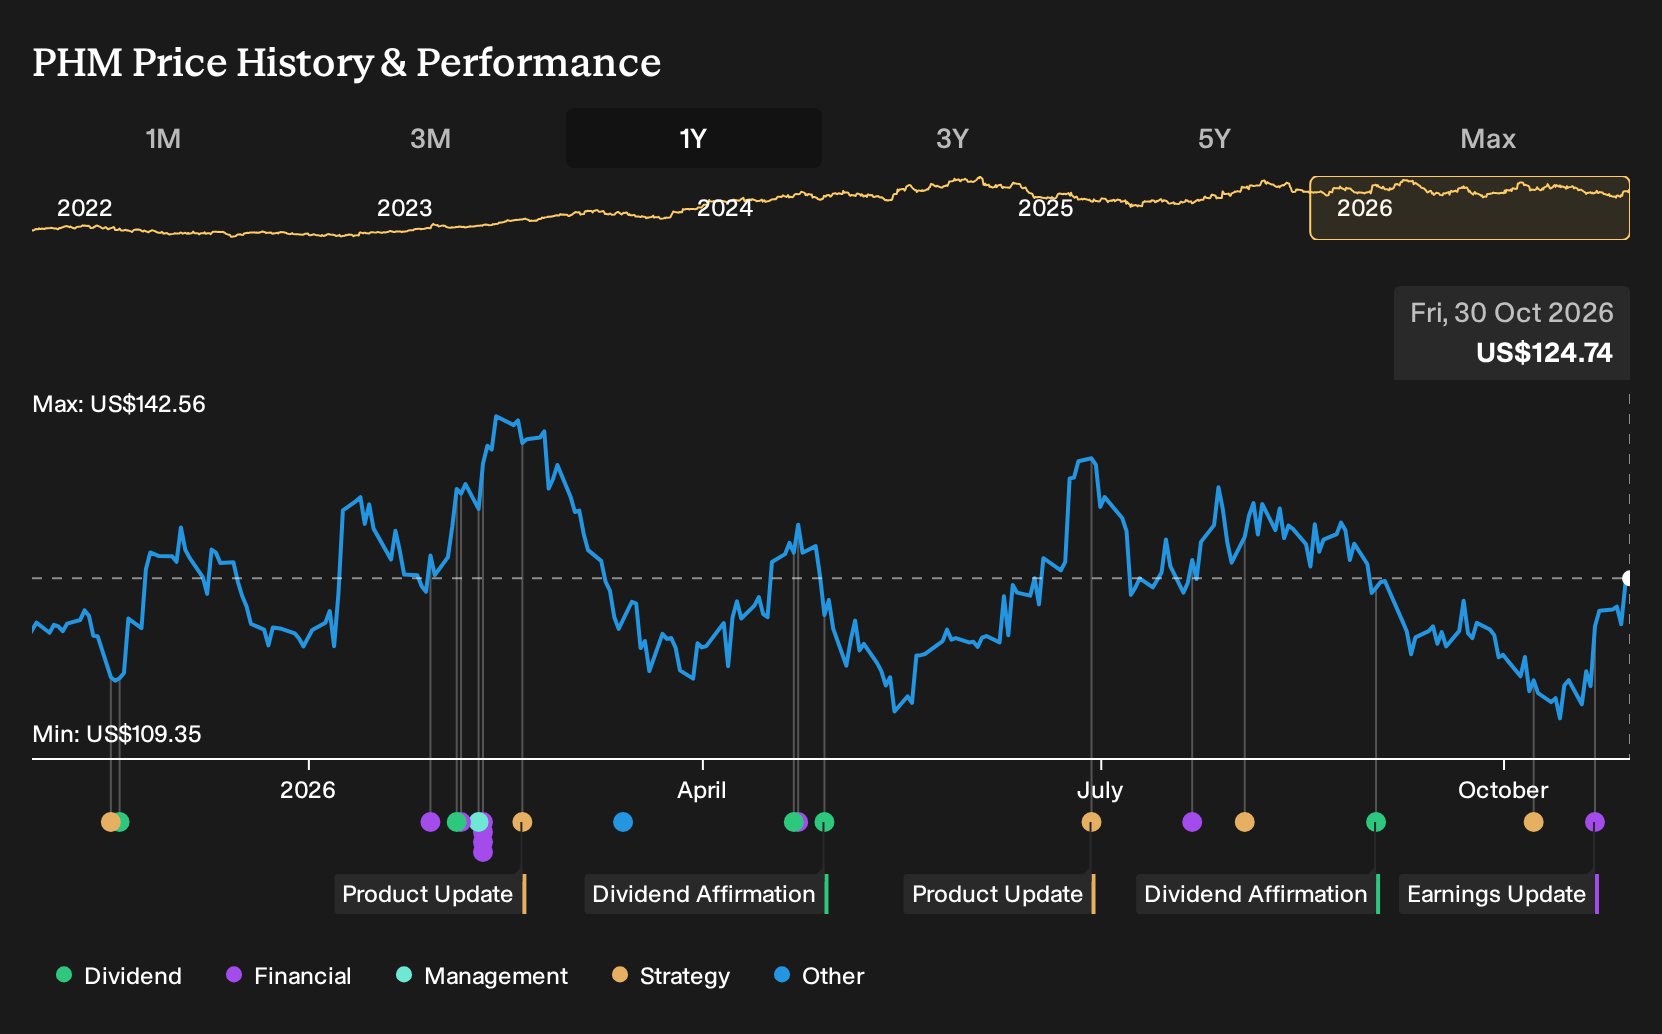
Uncover how PulteGroup's fair value indicates a 7% potential upside to its current price before the discount closes.
Exploring Other Perspectives
The lowest PulteGroup analysts emphasize the risk that weaker orders and pricing could persist. Before this earnings update, they were estimating roughly flat earnings of about US$1.8b on revenues of around US$15.8b by 2029. That is a much more cautious story than the consensus. Treat this quarter as fresh input and compare several viewpoints before deciding what makes sense for you.
Explore 4 other PulteGroup fair value estimates, including one that suggests as much as 16% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your PulteGroup research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for PulteGroup. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PulteGroup's overall financial health at a glance.
Looking for more investment ideas beyond PulteGroup?
If this PulteGroup update has sharpened your view on housing, broaden the watchlist and let the Simply Wall St Screener surface other opportunities that better match your risk tolerance, income needs, or value focus.
- If you want potential mispricing with stronger fundamentals to back it up, take a look at 30 high quality undervalued stocks that pass a quality and valuation filter.
- For income focused investing where cash payouts matter, scan through 5 dividend fortresses that pair higher yields with more robust balance sheets.
- When capital preservation ranks higher on your list, concentrate on 29 resilient stocks with low risk scores that score better on financial resilience and volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com