


TWC Enterprises (TSX:TWC) Stock Looks Cheap After Q3 Earnings Strength
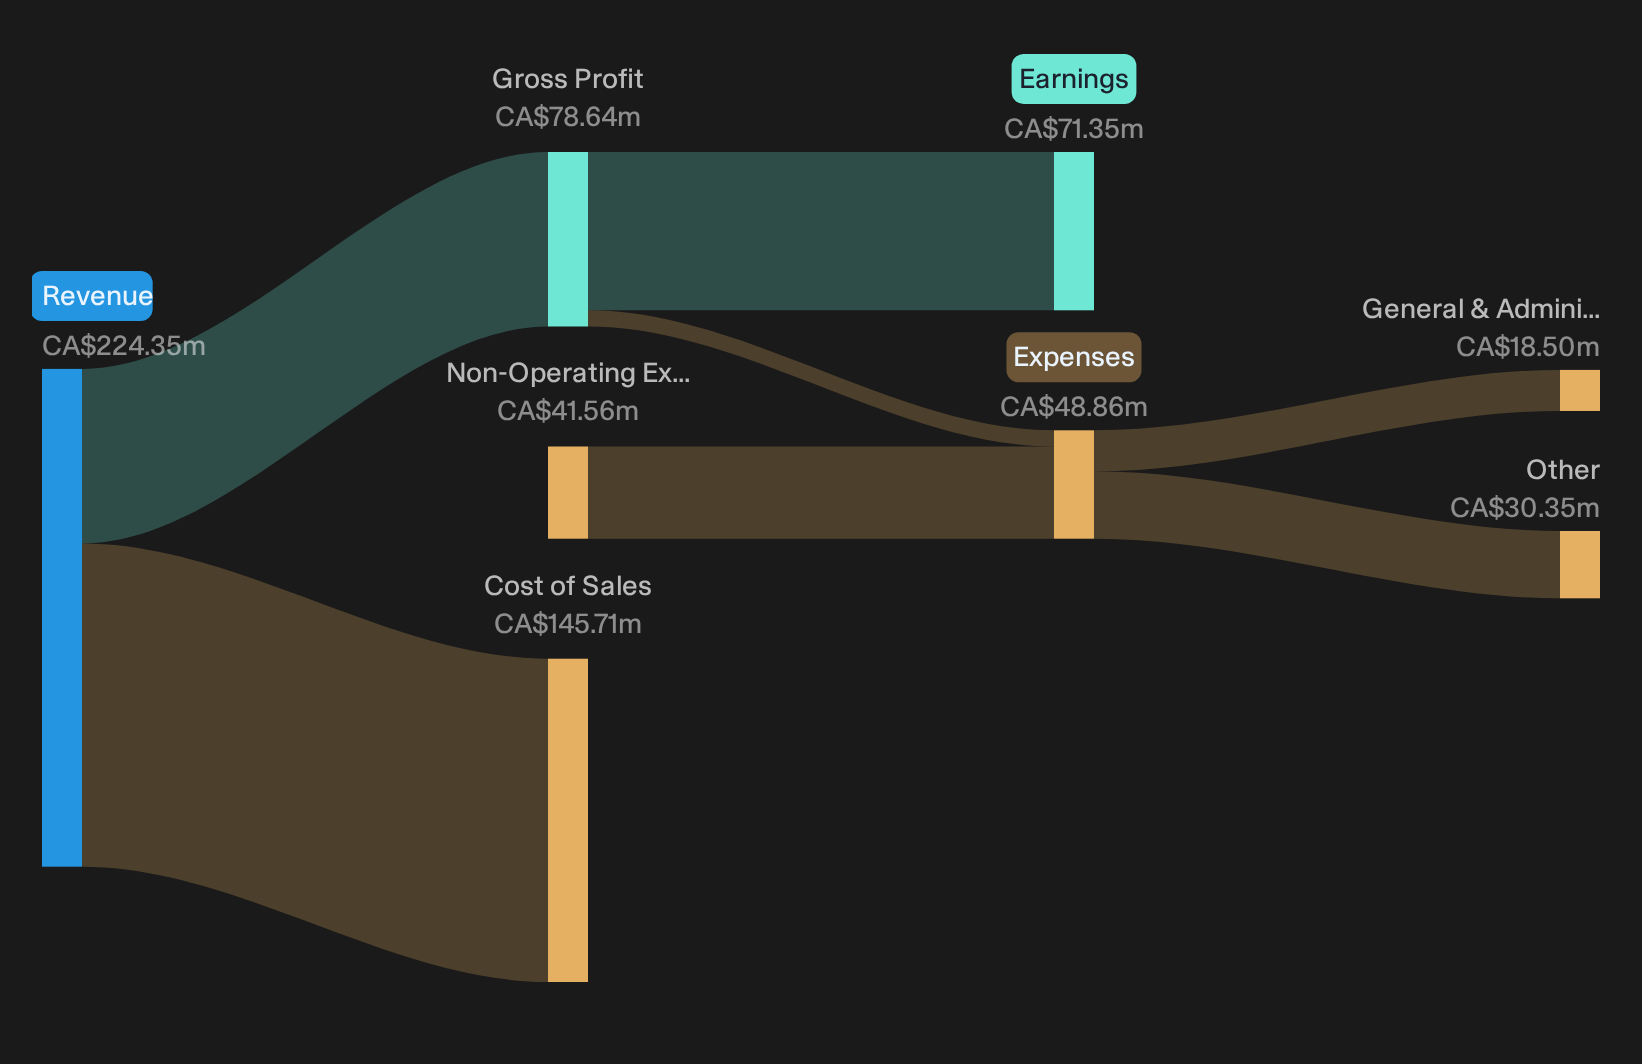
TWC Enterprises walked into its Q3 2026 earnings with a golf and leisure reputation and a stock that had eased over the past month, finishing at CA$26 on the day of the release. The fresh numbers told a sharper story. Quarterly revenue reached CA$79.5 million and basic earnings per share came in at CA$1.15, feeding into a trailing P/E of 8.8x that sits well below both industry and peer averages. The market reaction was muted, yet the earnings print pointed investors back to profitability and valuation rather than momentum.
Love the low 8.8x P/E on TWC Enterprises but want more options with similar value traits and robust fundamentals? Line this quarter up against our 4 high quality undervalued stocks to see how it compares.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): CA$79.5 million vs. CA$78.2 million (steady year-on-year top-line performance).
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): CA$27.7 million vs. CA$16.9 million (up about 63.8%).
- Basic EPS (Q3 2026 vs Q3 2025): CA$1.15 vs. CA$0.70 (up about 64.4%).
- Trailing Twelve Month Net Profit Margin (FY 2026 vs prior year): 31.8% vs. 15.2% (material margin expansion over the last 12 months).
Ask Charlie what TWC’s earnings surge says about its future.
TWC Enterprises: Earnings Support Asset-Backed Upside Story
TWC Enterprises looks closer to the steady, asset-backed leisure operator that bullish investors hope for. Revenue held around CA$79.5 million while net income, excluding extra items, moved to CA$27.7 million and basic EPS to CA$1.15. Profit margin on a trailing basis reached 31.8%. That mix suggests the golf portfolio and membership model are converting a relatively flat top line into stronger profitability. For anyone focused on real assets plus recurring fees rather than rapid expansion, this earnings print broadly fits the constructive narrative.
Muted Price, Soft Returns Keep Bear Concerns Alive
Market behaviour still gives room for a cautious view on TWC Enterprises. The share price is CA$26.0 as at 30 October 2026, with 7 day, 30 day and 90 day returns all declining by roughly 2% to 3%. Price action has not tracked the improvement in recent earnings, which can signal questions around durability of margins or growth in golf demand. For investors worried about a mature leisure business with limited expansion avenues, the market’s lukewarm response keeps that concern in play.
Muted trading and soft recent returns also raise a different question for TWC Enterprises. Are flat demand for golf, higher fixed operating costs and a five year earnings decline quietly building risk that is not obvious in one strong quarter? Review the full risk analysis for TWC Enterprises which shows 1 important warning sign
Hunt For Quiet Value Gaps
TWC Enterprises shows how earnings and recent trading can tell different stories about the same business. The real opportunity is spotting stocks that could be undervalued before fresh information closes the gap.
- Company 1 - 21% below our estimate - turn a growing backlog of aerospace and defense electronics into higher margin work on long running programs.
- Company 2 - 35% below our estimate - expand fee based infrastructure and water projects as acquired design firms plug into shared digital tools and delivery hubs.
- Company 3 - 45% below our estimate - add higher traffic mall sites and a faster ecommerce funnel to capture full price fashion demand with tighter inventory turns.
That is three of the list. See the full list of 4 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com