


Hawthorn Bancshares (HWBK) Stock Falls After Strong Q3 Earnings
Hawthorn Bancshares came into this Q3 2026 earnings print with a value label on it, trading on a P/E of 10.2x and carrying an implied price below one independent fair value estimate. The stock still slipped about 1.9% on the first full trading day after the release.
The headline result was solid for a regional lender. Basic earnings per share landed at US$1.01 on total revenue of US$22.8 million, and trailing net profit margin for the last year sat at 30.5%. The gap between that profitability profile and the market reaction is the tension investors now need to weigh.
Like the earnings power at Hawthorn Bancshares but uneasy about paying up for a regional lender that the market still treats as a value story? Check out the 30 high quality undervalued stocks as a benchmark list of peers that pair solid profitability with what our models flag as discounted valuations.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$22.79 million vs. US$18.76 million (higher year over year)
- Net Income (Q3 2026 vs. Q3 2025): US$7.06 million vs. US$6.13 million (higher year over year)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.01 vs. US$0.89 (higher year over year)
- Net Profit Margin, Trailing 12 Months (2026 vs. prior year): 30.5% vs. 27.4% (margin improved)
Earnings are one thing, but investors who care about what they are paying for Hawthorn Bancshares tend to watch the cash coming through the business. Based on Hawthorn Bancshares' recent cash flows alone, the stock could be a notable 29% undervalued.
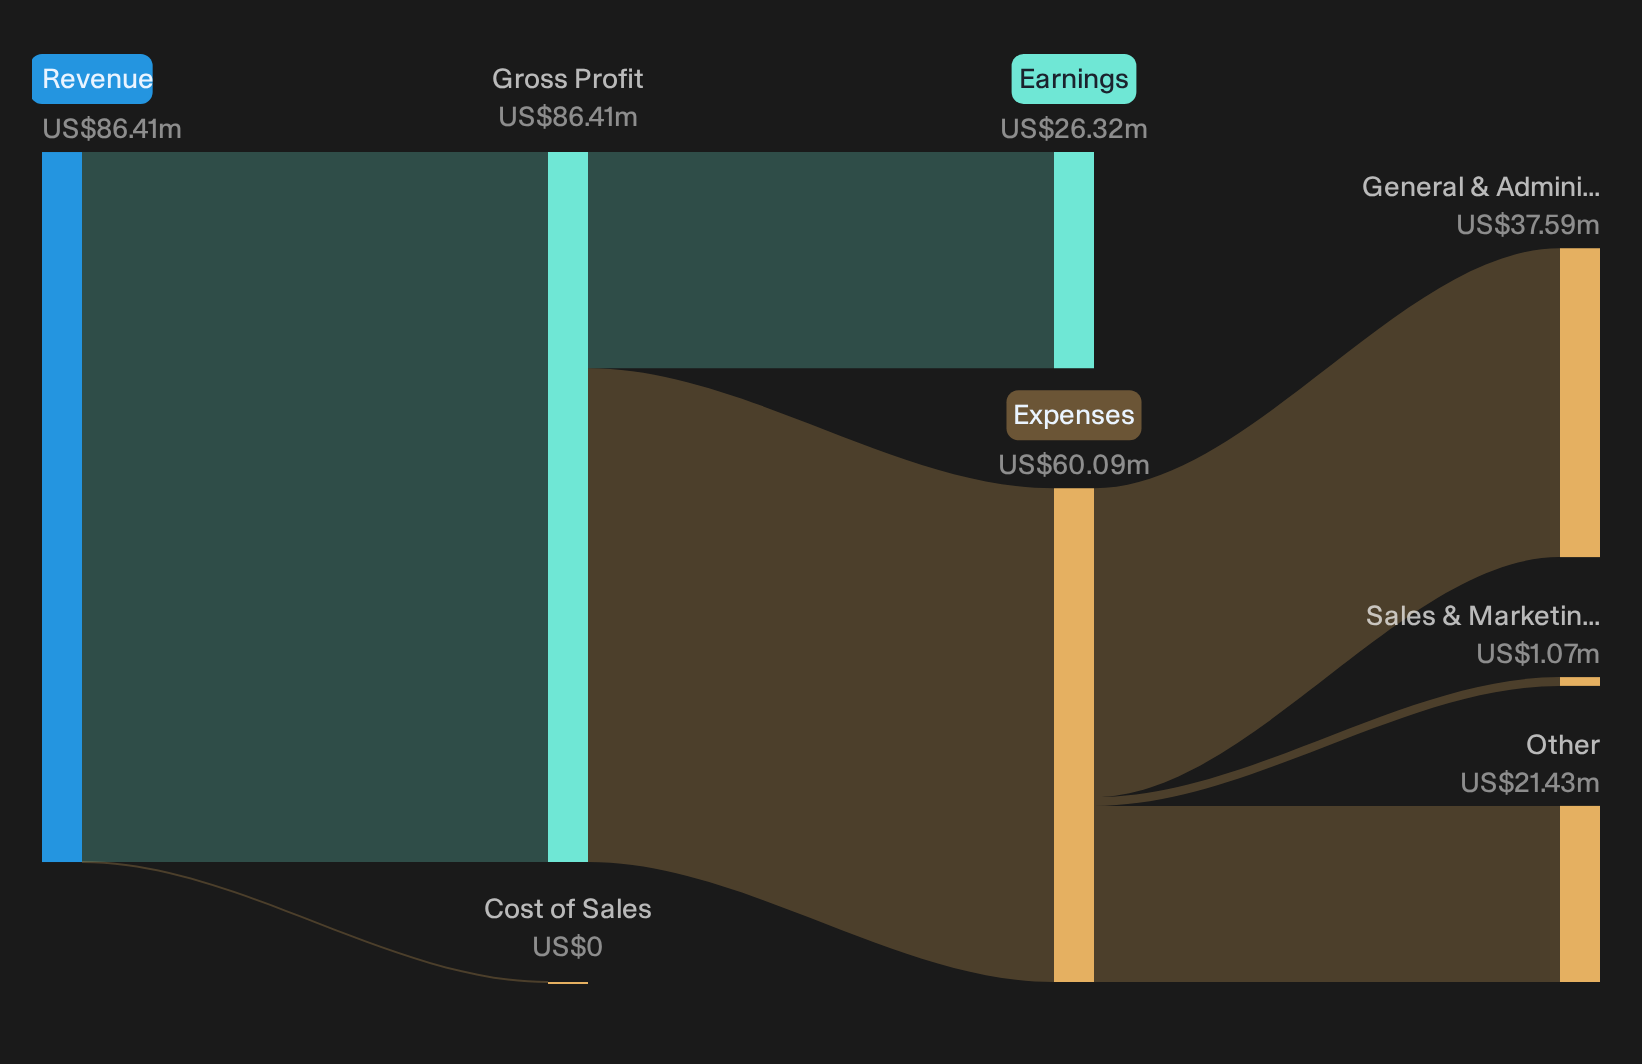
Hawthorn Bancshares results that support optimism
For a reader leaning optimistic on Hawthorn Bancshares, these figures help. Revenue and net income were both higher than a year ago, and basic EPS moved up to US$1.01. Profitability also looks firmer, with the trailing net margin at 30.5%. That kind of earnings profile fits a steady community banking story in which the core lending and fee businesses are pulling in more dollars without squeezing returns. Short term share performance has been mixed, yet the operating picture in this quarter appears more consistent with a slow grind forward rather than a franchise under strain.
Where the Hawthorn Bancshares bear case still bites
Even with healthier revenue and earnings, the share price reaction suggests some investors are not fully convinced. The stock slipped about 1.9% after the report and is slightly down over 90 days. That pattern can point to concerns that a community bank tied to one region may face limits on how far this earnings strength can run, or that credit and funding risks remain front of mind. The business appears profitable today, but the market response indicates investors still want more reassurance before rewarding that performance.
With earnings moving one way and the share price moving another, the real question for Hawthorn Bancshares is whether the balance sheet can comfortably support this profitability without hidden funding or credit pressure. Check the full debt, liquidity, and dividend sustainability breakdown in the financial health analysis of Hawthorn Bancshares stockHunt For Mispriced Earners
Hawthorn Bancshares highlights how earnings strength and share performance can diverge for extended periods. The real opportunity is identifying stocks that appear undervalued before market expectations adjust.
- Company 1 - 46% below our estimate - helps large online platforms collect and disburse funds as merchants adopt localized payment tools.
- Company 2 - 29% below our estimate - turns a large low-cost digital customer base into higher revenue per active user as markets mature.
- Company 3 - 38% below our estimate - builds a recommerce network where trade-in subsidies and refurbishment spending improve device quality and transaction volumes.
Those are three of them. See every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com