


Colgate Palmolive (CL) Q3 Earnings Put Margin Repair In Charge
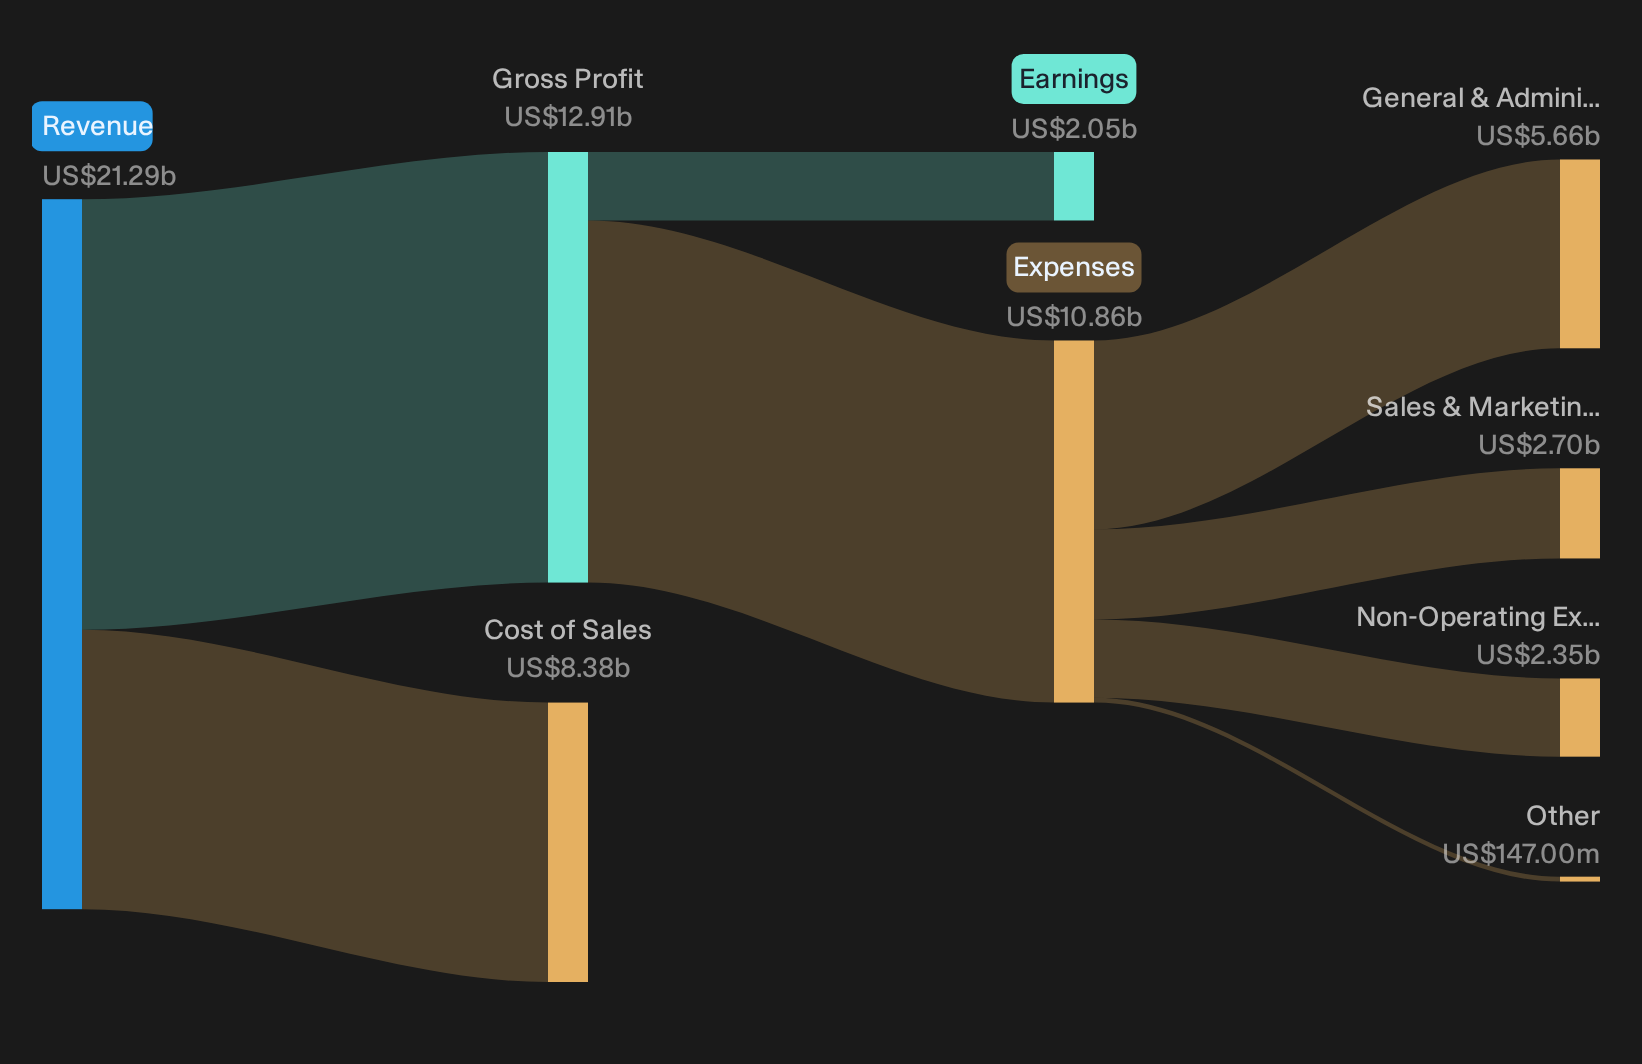
Colgate-Palmolive walked into its Q3 2026 report with the stock already on a strong run and then added another 2.3% in the first session after the release. Traders latched onto a cleaner profit story as quarterly basic earnings per share landed at about US$0.94 and net income reached roughly US$751 million.
The real action sat in margins. After a year where a large one off loss and thinner profitability have weighed on the story, investors treated this quarter’s gross margin expansion as confirmation that the repair job is taking hold. The question now is whether that one day relief rally truly captures what just changed in the Colgate-Palmolive earnings profile.
Love Colgate-Palmolive’s margin repair story but want consumer staples exposure with strong balance sheets already in place? Compare this quarter’s results with our list of solid balance sheet and fundamentals stocks (24 results) to see how it stacks up.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$5,369 million vs. US$5,131 million (change of about 4.6%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$751 million vs. US$735 million (change of about 2.2%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.94 vs. US$0.91 (change of about 3.6%)
- Trailing 12 Month Net Income Margin (up to Q3 2026 vs. prior year): 9.6% vs. 14.5%. The lower margin reflects the impact of a US$1.3 billion one-off loss.
Management says AI is now central to Colgate-Palmolive’s growth story. Ask Charlie what Colgate-Palmolive’s AI push really changed this quarter.
Premium Thesis: Colgate-Palmolive’s Margin Engine Under Review
The bullish story claims that premium products, technology and productivity will work together to keep Colgate-Palmolive’s profitability resilient even if categories stay flat.
"The main thing that has to go right is that premiumization, AI driven execution and SGPP funded reinvestment continue to translate into resilient margins even as category growth in key markets remains muted or flat."
Q3 shows some of that engine working. Gross margin expanded and management raised full year gross margin guidance after seeing roughly 200 bps of pricing support and SGPP savings offset raw material pressure. Hill’s and premium oral care helped mix, which lines up with the margin ambition, although the trailing 12 month net income margin still reflects the earlier US$1.3b loss.
Bear Case: North America Weakness And Legal Overhang
Bears worry that category softness and litigation will chip away at Colgate-Palmolive’s earnings power faster than premiumization can help.
"The underperformance in the U.S. and wider North America business, including shipment declines and heavier competitive activity, may not be fully offset by the current reset toward premium offerings and higher brand support, which could limit the benefit from premiumization and weigh on revenue growth and profitability."
North America still looks fragile. Management labels U.S. Oral Care a multi year turnaround and describes only early market share improvement. Category demand is soft, competitive intensity is high and there is an ongoing class action that could add cost later. For now, stronger emerging markets and Hill’s are offsetting these pressures more than fully resolving them.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Find Stocks Quietly Repricing Risk
Colgate-Palmolive just showed how quickly the mood around a margin story can change once a single quarter lands clean. The real opportunity sits in stocks that could be mispriced before that kind of shift is widely accepted.
- Company 1 - 20% below our estimate - expands an account and card ecosystem that directs payment activity into a rapidly scaling banking platform partnership network.
- Company 2 - 30% below our estimate - turns entrenched office, cloud and developer tools into an integrated AI layer embedded in routine enterprise workflows.
- Company 3 - 44% below our estimate - rolls out cash recycling machines and automated branches that help financial institutions reduce footprint while maintaining robust transaction capacity.
Those are three of them. See all 30 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com