


AutoNation (AN) Stock Climbs After Q3 Earnings Despite Debt Questions
AutoNation stock jumped 6.1% to US$179.64 after the Q3 2026 release, a strong move for a mature auto retailer that has already seen a mixed 90 day run. Traders reacted to another solid earnings print, with adjusted earnings per share at US$5.11 and record After Sales gross profit helping to steady the story.
In the short term, the market liked what it saw. Over a longer horizon, the key issue is how that profit picture aligns with a low single digit P/E multiple and a balance sheet where debt coverage by operating cash flow requires ongoing attention.
Love AutoNation’s strong earnings print but concerned that a low single digit P/E and debt coverage sensitivities could signal a balance sheet trap? Check your instincts against our list of solid balance sheet and fundamentals stocks (25 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$7,010.3m vs. US$7,037.4m (slight decline in quarterly sales)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$162.3m vs. US$215.1m (profit fell 24.5%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$4.92 vs. US$5.72 (earnings per share declined 14.0%)
- Same Store Sales Growth (Q3 2026 vs. Q2 2026): declined 2.4% vs. declined 1.5% (store-level trend weakened further)
Earnings tell you how AutoNation has performed this quarter, but cash flows are what many valuation focused investors watch when they try to anchor a price range. Looking at AutoNation’s cash generation alone, the stock could be a hefty 46% undervalued.
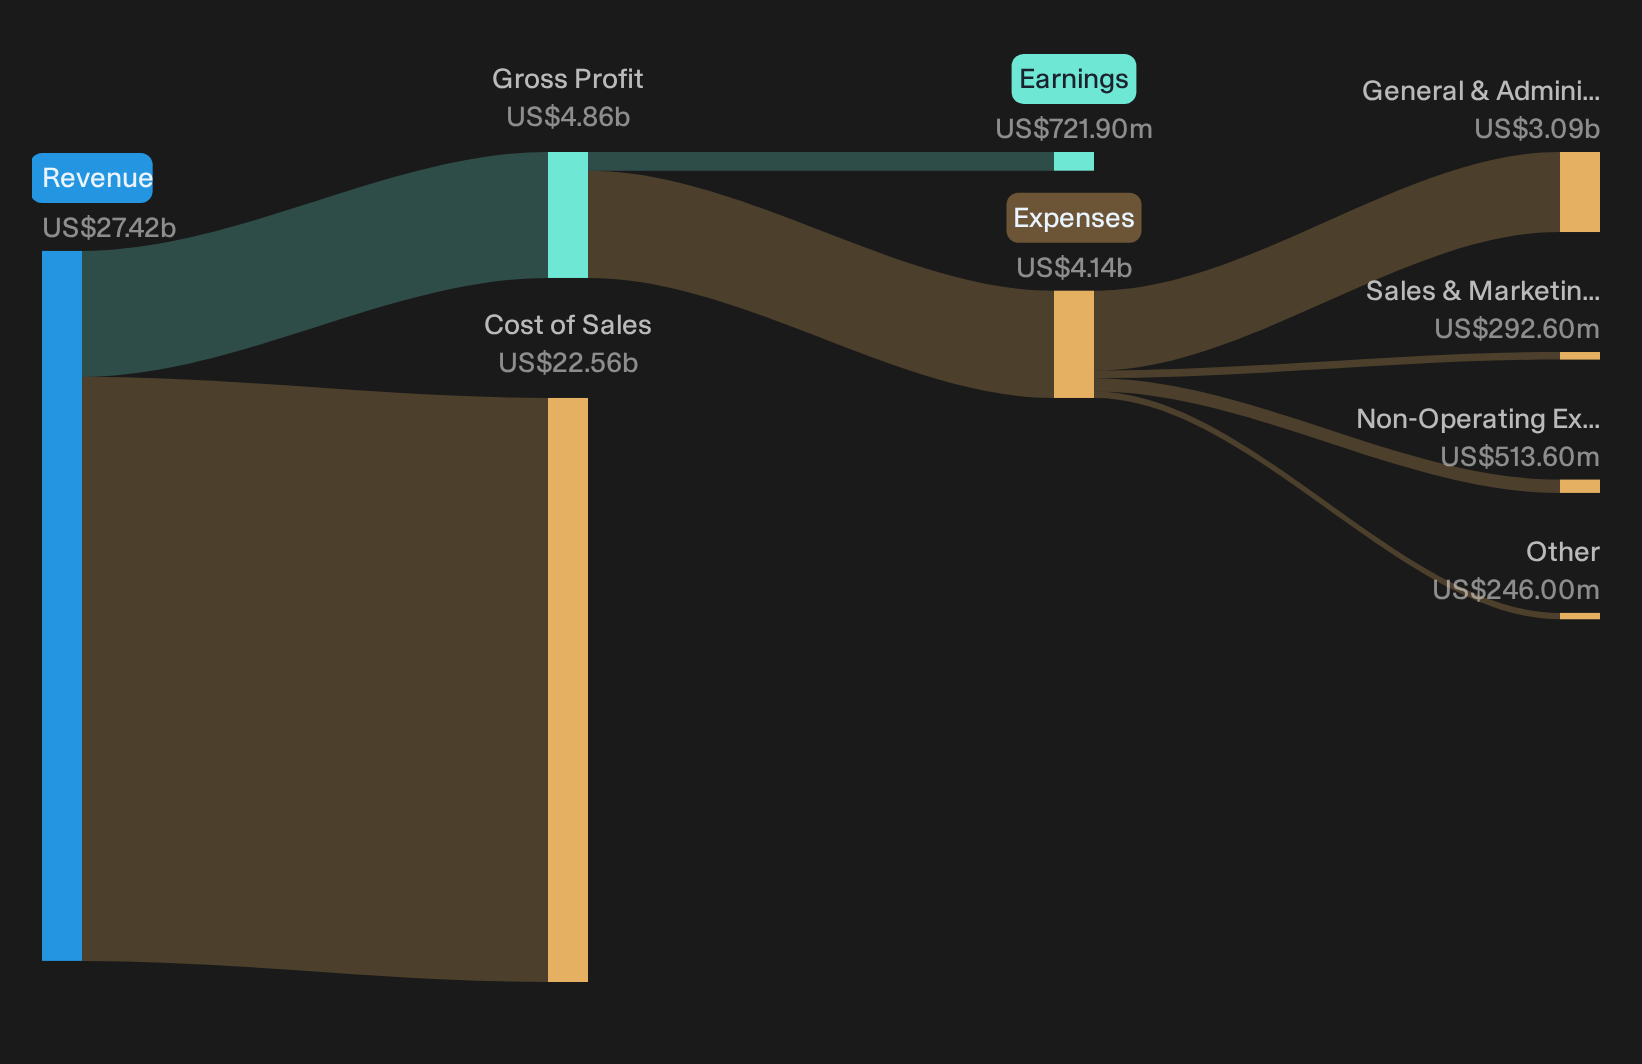
Evaluating Whether AutoNation’s Profit Mix Is Really Shifting
Supporters argue AutoNation is already pivoting its profit engine toward richer aftersales and in house finance streams.
"Aftersales customer pay and wholesale parts, which recently produced record gross profit at roughly 48% margin, give AutoNation room to deepen higher margin service penetration per vehicle and lift overall gross margin mix as this revenue stream scales."
Q3 offers clear milestones. After Sales delivered record US$617m gross profit and roughly half of group gross profit, with customer pay traffic up 5% and warranty visits up 13%. Margin dipped slightly to 47.8%, yet wholesale parts grew faster, which fits the thesis of a larger, parts heavy profit pool even as near term mix trims percentage margins.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Aftersales Fears Meet A Mixed AutoNation Reality
Bearish investors worry that AutoNation’s high margin service engine is already losing steam as customer behavior and technology change.
"Although AutoNation is leaning on high margin aftersales, where customer pay and wholesale parts have recently supported record gross profit, management now flags that elective maintenance deferrals and a shift of heavy mechanical work to lower margin over the air fixes are moderating that growth."
The latest print cuts both ways. After Sales produced record US$617m gross profit and around half of group gross profit, with customer pay traffic and warranty visits both higher. Yet margin slipped from 48.7% to 47.8% as wholesale parts grew faster, so the mix pressure flagged by bears is visible even while absolute profit milestones are still being hit.
Hunt Quiet Dislocations Before They Close
AutoNation just reminded you how a single quarter can reframe an established business. The real opportunity is finding stocks that could be undervalued before the market reassesses their earnings power and operating discipline.
- Company 1 - 38% below our estimate - leans into heavier unsided freight while using AI tools to tighten carrier vetting and reduce fraud risk.
- Company 2 - 20% below our estimate - extends a teahouse network as overseas outlets ramp GMV and test membership programs and supply chain services.
- Company 3 - 46% below our estimate - builds larger LED display systems while pushing more software, services and retooled manufacturing into transportation projects and youth sports venues.
Those are three of them. See every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com