


Earnings Jump Could Be A Game Changer For JLL Stock
- Jones Lang LaSalle reported third quarter 2026 sales of US$7,281.2 million and net income of US$319.8 million, with higher basic and diluted earnings per share from continuing operations compared with the same period in 2025.
- Stronger year to date earnings, together with JLL's advisory role on a US$386 million construction loan, highlight how fee based transaction activity and broader commercial real estate services are feeding into financial performance.
- Attention now turns to how this step up in Jones Lang LaSalle's earnings power may influence the longer term investment narrative.
Scan what is working in commercial real estate today by comparing Jones Lang LaSalle's earnings story with our curated list of solid balance sheet and fundamentals (25 results).
Jones Lang LaSalle Investment Narrative Recap
For Jones Lang LaSalle, the core belief is that a more recurring, services heavy model can offset the ups and downs of capital markets and leasing. The latest quarterly report, with higher sales, net income and earnings per share than a year ago, supports that earnings power is holding up. The near term swing factor still looks like transaction volumes, especially in capital markets, while a sharp slowdown there would likely pressure margins.
The biggest operational risk remains exposure to weaker office demand and any drag from property management contract churn. In the short term, the jump in nine month earnings to US$694.4 million, from US$390.4 million a year ago, gives management more breathing room to keep investing in AI tools and global platforms without stretching the balance sheet.
The most relevant update alongside these results is the advisory role on the US$386 million senior construction loan for the InterContinental Orlando project. That deal reinforces how Jones Lang LaSalle leans on fee based advisory in complex financing rather than tying up its own capital, which keeps risk more on the client and lender side of the table.
For you, transactions like InterContinental Orlando matter because they show the firm winning large, high profile mandates in hospitality while still being exposed to cyclical deal activity. Execution risk stays focused on keeping this pipeline full if capital markets slow again, and on translating that activity into consistent, recurring mandates in project and workplace management.
Jones Lang LaSalle's current analyst narrative points to forecast revenue of US$34.4b and earnings of US$1.4b by 2029, implying revenue growth of 7.8% per year and an increase in earnings of about US$400.9m from the US$999.1m reported today.
Uncover why Jones Lang LaSalle's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
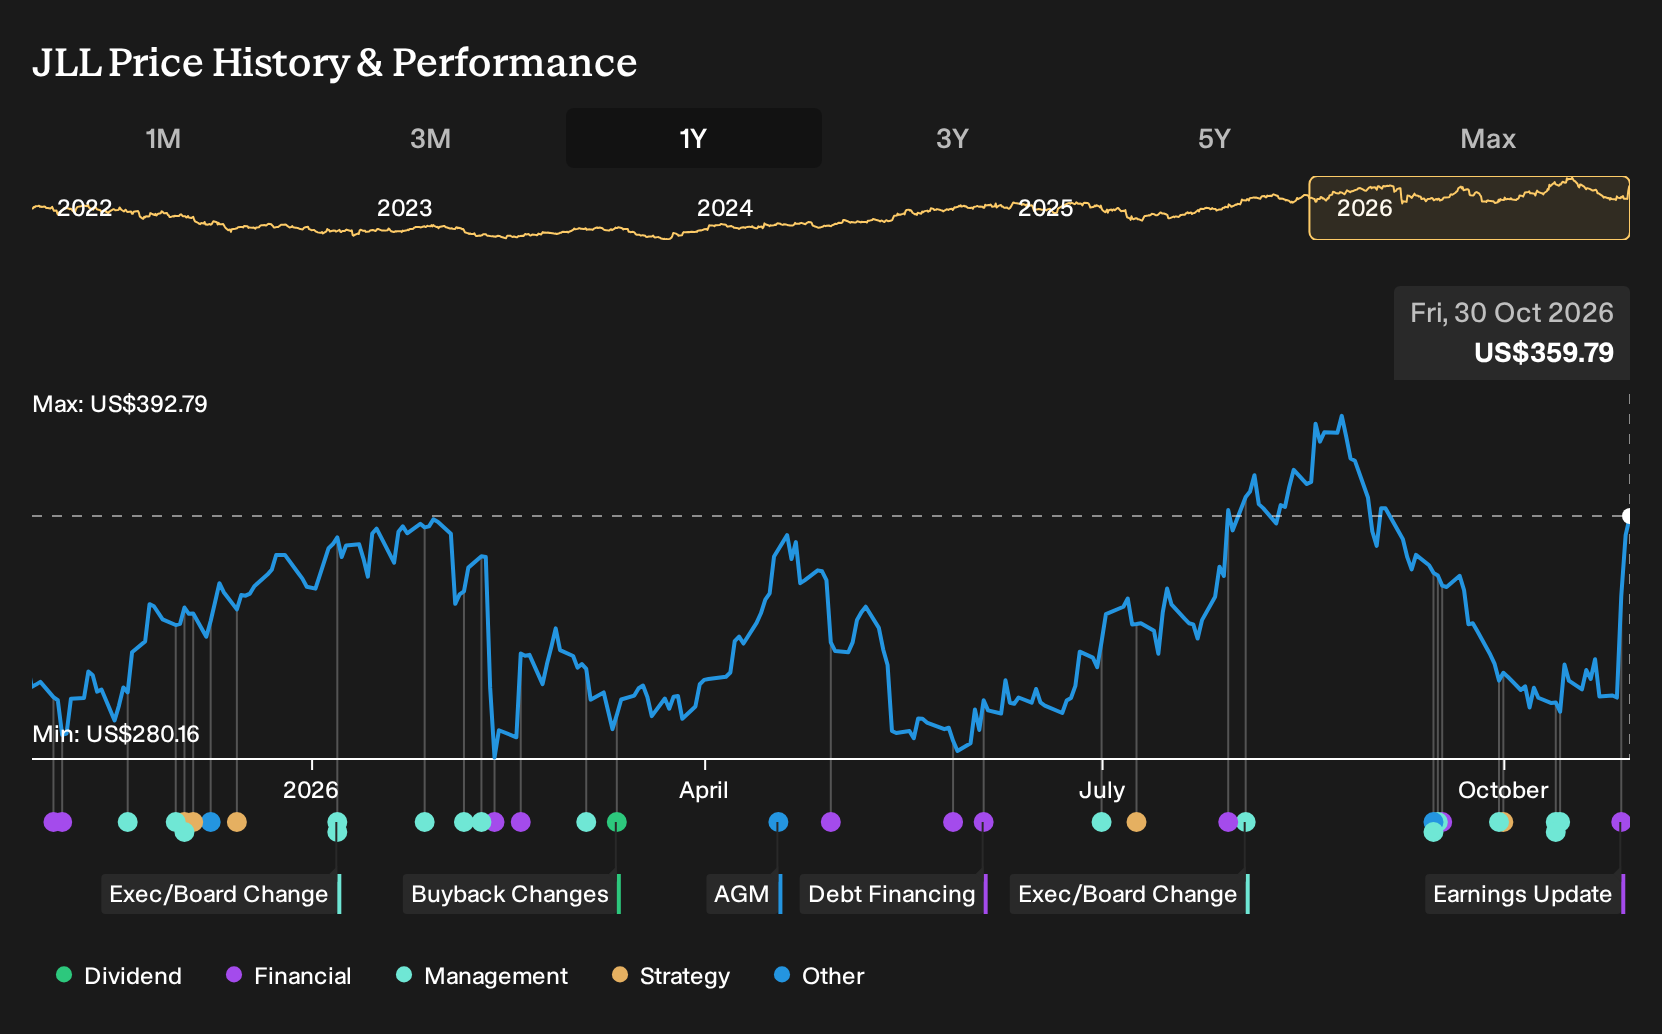
Exploring Other Perspectives
Some of the most optimistic analysts frame Jones Lang LaSalle’s AI execution as the real swing factor for you, not just capital markets volumes. Before this earnings release, the bullish cohort was pencilling in revenue of about US$36.1b and earnings of roughly US$1.5b by 2029. That is a step above the broader consensus and shows how sharply opinions can differ. These AI heavy forecasts and the latest Orlando financing news now sit side by side, giving you a reason to compare several viewpoints and watch how both narratives adjust as fresh data lands.
Explore 2 other Jones Lang LaSalle fair value estimates, including one that suggests as much as 72% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jones Lang LaSalle research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Jones Lang LaSalle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jones Lang LaSalle's overall financial health at a glance.
Looking for more investment ideas beyond Jones Lang LaSalle?
If Jones Lang LaSalle has helped sharpen your view on commercial real estate, you can use that momentum and compare it with other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who care most about balance sheet strength and resilient fundamentals, start with a list of solid balance sheet and fundamentals (25 results) to help keep financial fragility off your shortlist.
- If value is your priority and you want candidates where quality and pricing intersect, scan our 29 high quality undervalued stocks to see which businesses align with that tilt.
- For readers building an income focused portfolio, use the 5 dividend fortresses as a quick way to spot higher yield opportunities that still clear basic quality checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com