


Is Lowered Full Year Guidance Altering The Investment Case For PROG Holdings (PRG)?
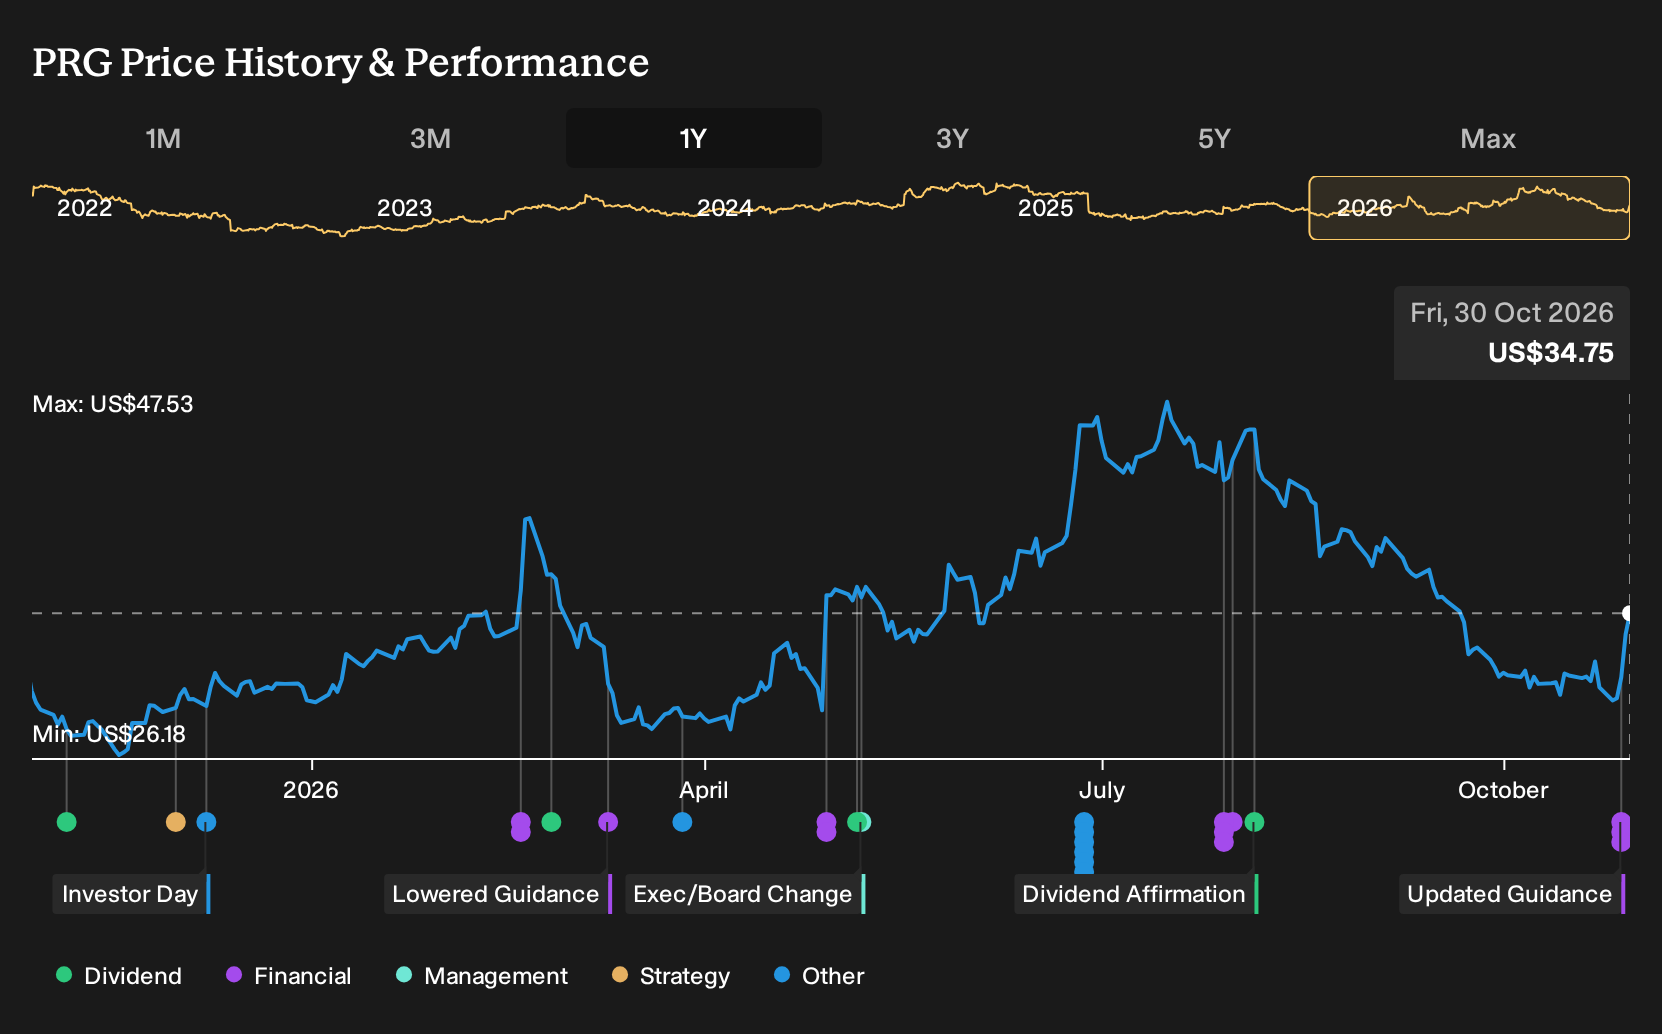
- PROG Holdings reported third quarter 2026 results with US$552.27 million in sales and higher net income and EPS, while at the same time trimming full year revenue, earnings and diluted EPS guidance for 2026 and issuing new fourth quarter targets.
- The company paired this more cautious full year outlook, which reflects tighter leasing standards and macro pressure, with a refreshed US$500 million buyback authorization and a new US$100 million accelerated share repurchase. This indicates a strong focus on returning capital to shareholders.
- We will now look at how PROG Holdings' reduced 2026 earnings guidance could influence the longer term investment narrative around its ecosystem.
PROG Holdings Investment Narrative Recap
Owning PROG Holdings means believing its lease to own and BNPL ecosystem can turn consistent credit performance and data driven underwriting into steadier earnings. The lower 2026 guidance points to pressure from tighter leasing standards and macro headwinds, so the near term swing factor is how well credit and loss trends hold through the key fourth quarter.
The biggest risk right now is that weaker consumer demand or softer GMV at Progressive Leasing and Four keeps revenue growth modest while net margins stay under strain. If that happens, the reset guidance may not change the long term story much, but it can keep sentiment fragile around execution.
The most relevant piece of fresh information is the new fourth quarter 2026 outlook. Management now guides to US$827 million to US$862 million of revenue, US$40 million to US$45.5 million of net earnings from continuing operations and US$1.04 to US$1.16 of diluted EPS from continuing operations.
For you, this quarterly range becomes a short term scorecard. Delivery near the upper end would support the idea that PROG Holdings can manage tighter credit standards while keeping profitability intact. In contrast, results closer to the low end would keep attention on the existing risks around loan performance, margin pressure and slower top line progress.
What The Long Term PROG Holdings Consensus Is Pricing In
PROG Holdings' longer term analyst narrative assumes its revenue can compound at about 10.3% per year, with profit margins rising from 4.8% today to 6.3% by 2029. On that view, earnings would move from US$125.8 million currently to US$222.5 million by 2029, with analysts tying that to earnings per share of US$6.10 and a P/E of 11.7x on those future profits compared with 10.6x today.
On the same consensus framework, the current US$33.48 share price is being compared with an average target of US$49, bracketed by a bullish case at US$64 and a more cautious US$40. To line up with those targets, you would need to assume PROG Holdings reaches about US$3.5b of revenue and US$222.5 million of earnings in 2029, and that the stock trades at that higher 11.7x P/E multiple instead of closer to the US consumer finance peer group sitting around 8.5x.
These expectations build in modest annual share count growth of 0.72% and use a discount rate in the 9.3% to 9.33% range to translate the 2029 profile back to today. What matters for you is less the exact discount rate and more whether the ingredients behind that 2029 picture, such as higher BNPL contribution, steadier credit outcomes and wider ecosystem earnings, still feel realistic after the latest guidance reset.
PROG Holdings' current earnings are US$125.8 million and analysts forecast consensus earnings of US$222.5 million by 2029. This implies an earnings increase of about US$96.7 million on revenue that analysts expect to reach roughly US$3.5b, supported by an assumed 10.3% annual revenue growth rate.
Uncover why PROG Holdings' fair value indicates a 41% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle to watch is credit quality. The most cautious analysts were already assuming lease write offs stay near the high end of targets and still pencilled in about US$3.6b of 2029 revenue and US$224.6 million of earnings. That is more pessimistic on valuation, not on growth, so today’s guidance reset could push those views further apart. Use this earnings update as a prompt to compare how your own expectations differ from both the bullish and bearish camps.
Explore another PROG Holdings fair value estimate, including one that suggests it could be worth just $49.00!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your PROG Holdings research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for PROG Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PROG Holdings' overall financial health at a glance.
Looking for more PROG Holdings sized investment ideas?
If this PROG Holdings update has sharpened your view on risk, reward and balance sheet strength, you can use that same checklist to scan a wider field of opportunities with the Simply Wall St Screener.
- If you want potential value plus resilience, you can start with companies that pair strong fundamentals with attractive pricing through the 29 high quality undervalued stocks.
- For steadier income streams, you can focus on businesses that combine higher yields with balance sheets that can support payouts in the 5 dividend fortresses.
- If capital protection matters most, you can look across stocks filtered for sturdier financial positions and lower overall risk in the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com