


Does Raised 2026 Guidance Change The Bull Case For Public Storage (PSA)?
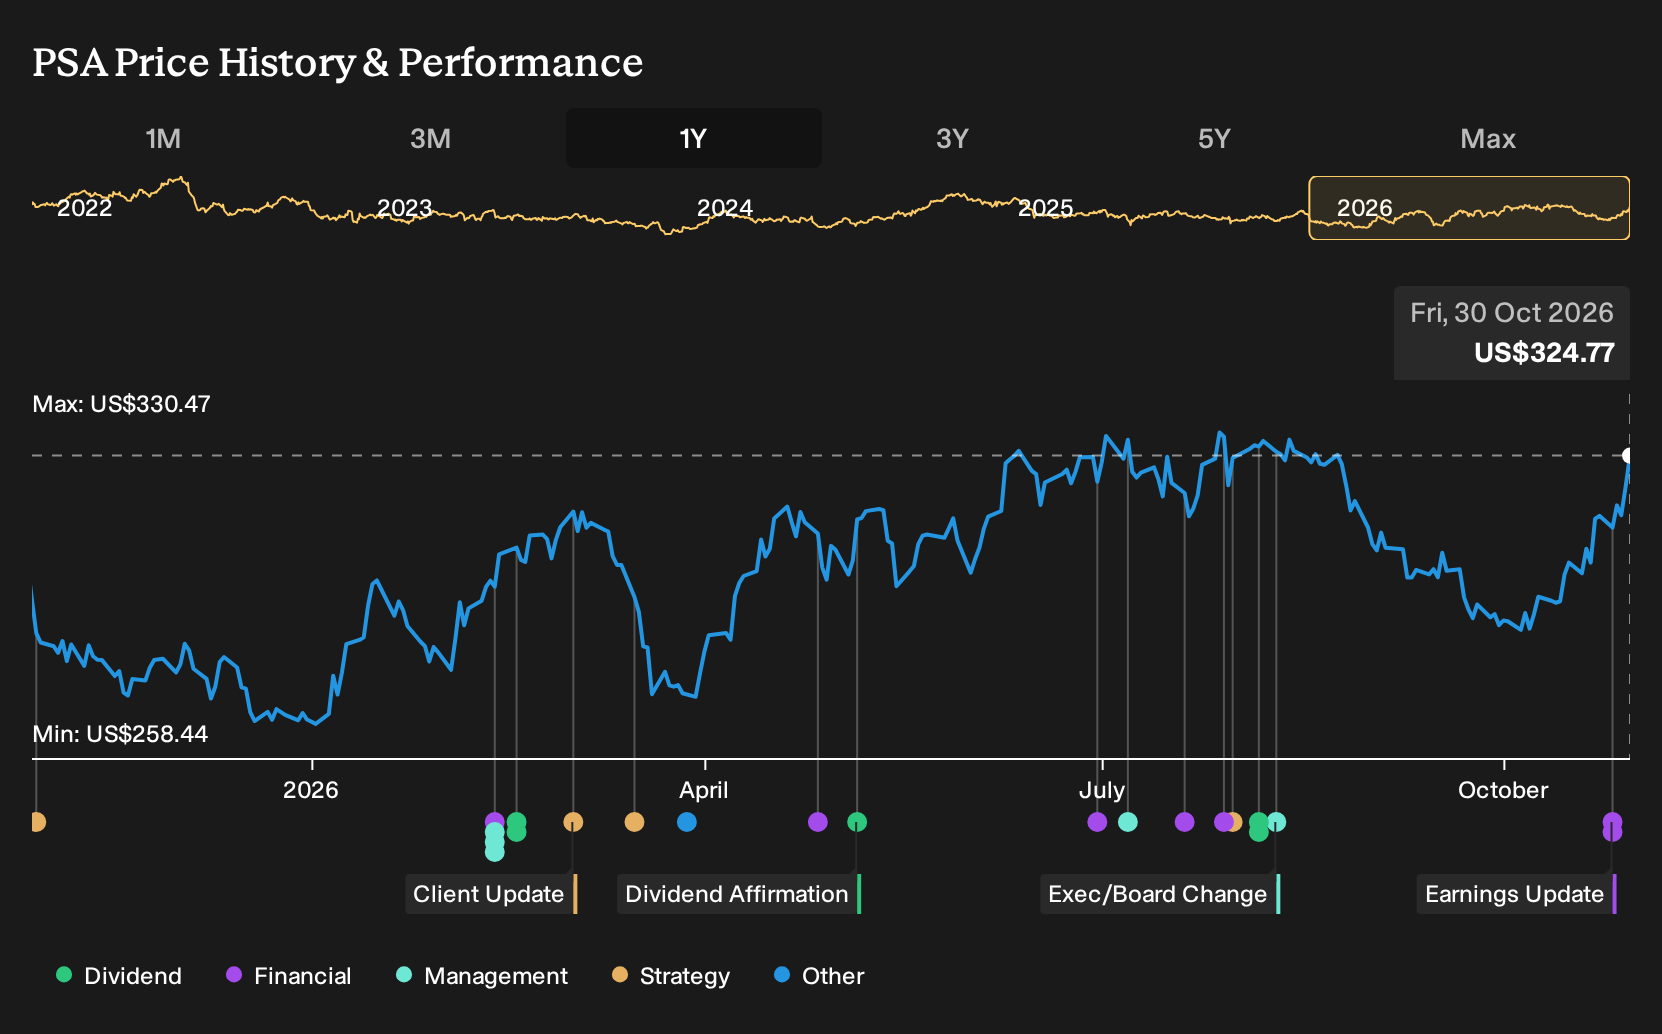
- Public Storage reported third quarter 2026 revenue of US$1,366.19 million and net income of US$366.93 million, then raised full year guidance for net operating income and revenue growth to slightly positive ranges.
- The guidance shift from expected contraction to a flat to modestly positive outlook signals tighter control of operating performance across the storage portfolio.
- We will now look at how Public Storage's raised full year guidance could shape the investment narrative around cash flow resilience.
Scan how Public Storage's guidance reset compares with peers by reviewing the 30 resilient stocks with low risk scores, which combine resilient balance sheets with measured growth profiles.
Public Storage Investment Narrative Recap
To own Public Storage, you need to believe its large storage footprint, recent acquisitions, and PS Next efficiency push can keep cash flow relatively steady even when individual markets soften. The raised full year outlook for net operating income and revenue suggests near term pressure is less severe than feared, but not entirely gone.
The clearest short term swing factor remains how quickly weaker Sunbelt markets stabilize and how well new facilities are absorbed. The main risk is that soft pricing and integration hurdles on the National Storage Affiliates and Public Storage Canada deals persist longer than expected, which could keep NOI margins and earnings under strain.
The most relevant update for that thesis is the third quarter 2026 earnings release. Public Storage reported quarterly revenue of US$1,366.19 million and net income of US$366.93 million, with earnings per share lower than the prior year even as the nine month figures were higher on both revenue and profit.
For investors, this mix of higher top line and softer quarterly earnings keeps the focus firmly on execution. It puts more weight on management delivering the targeted synergies from the recent acquisitions, holding operating costs in check through PS Next, and sustaining occupancy so that even modest revenue growth can still feed into reliable cash generation over time.
Public Storage's current analyst narrative points to revenues of US$6.0b and earnings of US$2.1b by 2029, built on forecast revenue growth of 6.7% per year and an earnings increase of about US$300m from US$1.8b today.
Uncover why Public Storage's fair value indicates that it is in line with its current price.
Exploring Other Perspectives
Across three fair value estimates from the Simply Wall St Community, Public Storage ranges from about US$260.51 to roughly US$405.05, which is a wide spread for a single ticker. Those private investors are looking past raised 2026 guidance toward risks like Sunbelt softness and acquisition integration, and you should weigh those views against your own expectations for cash flow resilience.
Explore 2 other Public Storage fair value estimates, including one that suggests there could be as much as 25% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Public Storage research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Public Storage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Public Storage's overall financial health at a glance.
Looking for more investment ideas beyond Public Storage?
Once you have a view on Public Storage, it can help to widen the lens and compare it with other opportunities that match your risk tolerance and portfolio goals.
- If you want potential mispriced opportunities with quality fundamentals, scan through the 29 high quality undervalued stocks and see which ones deserve a closer look.
- For investors who care most about steady balance sheets and financial resilience, start with the list of solid balance sheet and fundamentals (25 results) and compare how they stack up against Public Storage on core metrics.
- If you prefer ideas that fly under the radar but still have robust fundamentals, sift through the 18 high quality undiscovered gems and build your own watchlist from there.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com