


Harley Davidson (HOG) Stock May Trade At A Premium After Raised Guidance
Harley-Davidson shares have climbed strongly in 2026, and the latest headlines around earnings, retail demand, and its electric spin-off are now pushing investors to ask whether the current price lines up with the motorcycles and financing revenue the company is actually generating. With a long-established brand and a stock that has already moved a lot this year, the key issue is how much of its sales story is already baked into the valuation.
- The stock is up 51.3% year to date, which puts real pressure on the question of whether its sales base can carry the higher market value that move implies.
- Recent results showed retail motorcycle volumes growing while LiveWire faces funding restraint and restructuring, a mix that can influence how investors think about future revenue growth and the timing of cash flows from Harley-Davidson's core and electric operations.
- The analysts covering Harley-Davidson have run their own numbers. See what analysts think Harley-Davidson's shares could be worth.
For investors, the debate is whether Harley-Davidson's current share price is adequately supported by the sales it is generating today and the revenue profile the market now appears to be pricing in.
To see how Harley-Davidson's 51.3% year-to-date run compares with other companies where valuation hinges on sales, compare it with 29 high quality undervalued stocks.
Does Harley-Davidson Look Pricey on Sales?
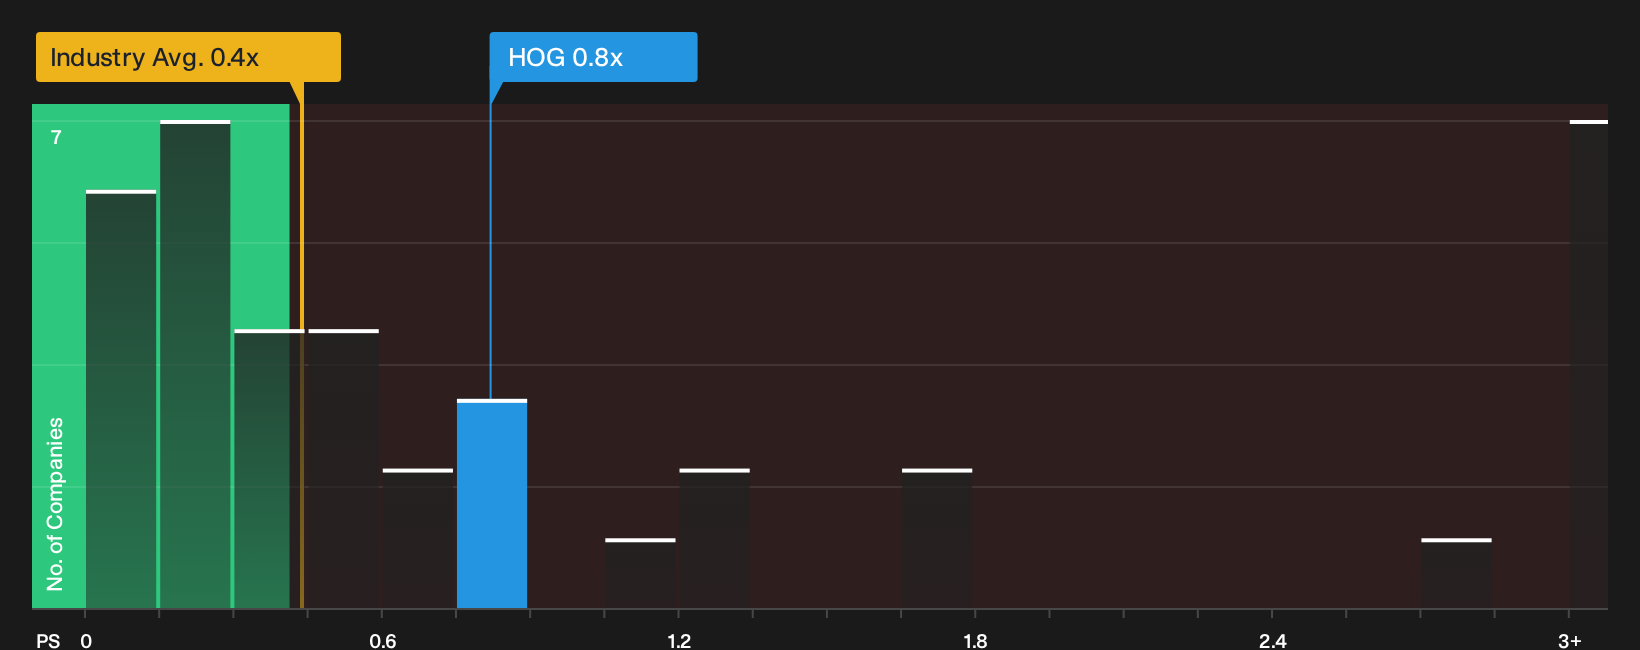
The P/S ratio fits Harley-Davidson because investors are paying mainly for its ability to turn motorcycle demand into revenue, while earnings move around more with financing and restructuring noise. On this metric, the stock trades on a P/S of 0.8x, compared with a peer average of about 1.2x and an auto industry average near 0.4x, so the shares screen below close peers but above the wider sector.
The fair-value model that blends Harley-Davidson’s margins, growth assumptions, size and risk profile points to a lower P/S than where the stock trades today, which indicates the shares screen overvalued against that tailored benchmark. Because management just raised full-year guidance for the core motorcycle and financial services operations, the current P/S multiple also asks you to judge how durable that sales trajectory and LiveWire restructuring plan really look. To see how much upside or downside that model implies relative to today’s market pricing, compare Harley-Davidson’s current multiple with. Explore the numbers behind Harley-Davidson's P/S valuation.
The Harley-Davidson Narrative: What Would Justify Today's Price?
Harley-Davidson's valuation puzzle naturally leads to Simply Wall St Narratives. These set out the specific paths for growth, margins and earnings that would need to play out for the stock to look meaningfully cheaper or more expensive than it does today on the Community page. Each narrative links its number to a clear view on how Harley-Davidson's expansion, profitability and risk profile could evolve, giving you something concrete to revisit as fresh information comes through.
Community views on Harley-Davidson are split between those who see more reset potential ahead and those who think much of that story is already reflected in the price.
Bull case: 5% undervalued
"The current setup implies a share price that does not fully reflect the targeted minimum $150 million of fixed cost savings, the $350 million+ HDMC EBITDA objective for 2027 and the balance sheet shift that has reduced total debt plus deposits to $2.8 billion..."
Discover why this Narrative puts Harley-Davidson at 5% undervalued.
Bear case: roughly fairly valued
"Even with raised guidance and recent beats versus expectations, Harley-Davidson still reported a 26% year on year decline in consolidated profit to about US$80 million in Q2 2026 on a 6% drop in revenue and an operating margin of roughly 6.2%..."
Explore why this Narrative puts Harley-Davidson at roughly fairly valued.
Harley-Davidson’s price is only one question, who is steering the ship is another
Before you lean too hard on the current valuation, it is worth asking who is actually setting Harley-Davidson’s priorities, how their pay is structured, and what that really encourages them to do. See who runs Harley-Davidson and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com