


Why Is Prudential Financial (PRU) Drawing Fresh Attention Now?
Prudential Financial (PRU) is heading into its next earnings report with analysts projecting quarterly earnings of $3.32 per share and revenue of $13.96b, both expected to decline from the prior year.
Recent moves in Prudential Financial's share price tell a mixed story. The stock has edged higher with a 1-month share price return of 2.53% but has given back some ground over the past quarter with a share price decline of 4.61%. At the same time, the 1-year total shareholder return of 17.9% and 3-year total shareholder return of 43.2% point to investors having been rewarded over a longer stretch as they reassess earnings risks and the impact of partnerships such as the SoFi term life tie-up.
See how Prudential Financial compares with other insurers by reviewing a curated list of peers that currently screen as 29 high quality undervalued stocks based on fundamental strength.
Prudential Financial has already delivered strong multi year gains, yet the latest pullback and softer earnings outlook leave a live question: Is most of the easy upside gone, or does today’s valuation still leave room ahead?
Most Popular Narrative: 33.9% Overvalued
On the widely followed narrative, Prudential Financial screens as expensive, with a fair value of $87 against a last close of $116.45, which puts more weight on execution risk than on recent share price gains.
The ambition to lift PGIM from about 12% to roughly 25% of adjusted operating income relies heavily on expanding in private credit, infrastructure and other higher fee areas at a time when competition for these assets is intense. As a result, fee pressure and higher cost of talent could limit margin expansion and keep net margins closer to current levels.
See why 0 investors see Prudential Financial as 34% overvalued.
Result: Fair Value of $87 (OVERVALUED)
Still, if Prudential Financial executes on its US$750 million cost program and successfully rotates over US$3b into higher return areas, this bearish script could shift quickly.
Find out about the key risks to this Prudential Financial narrative.
Another View: Prudential Financial On Earnings Multiples
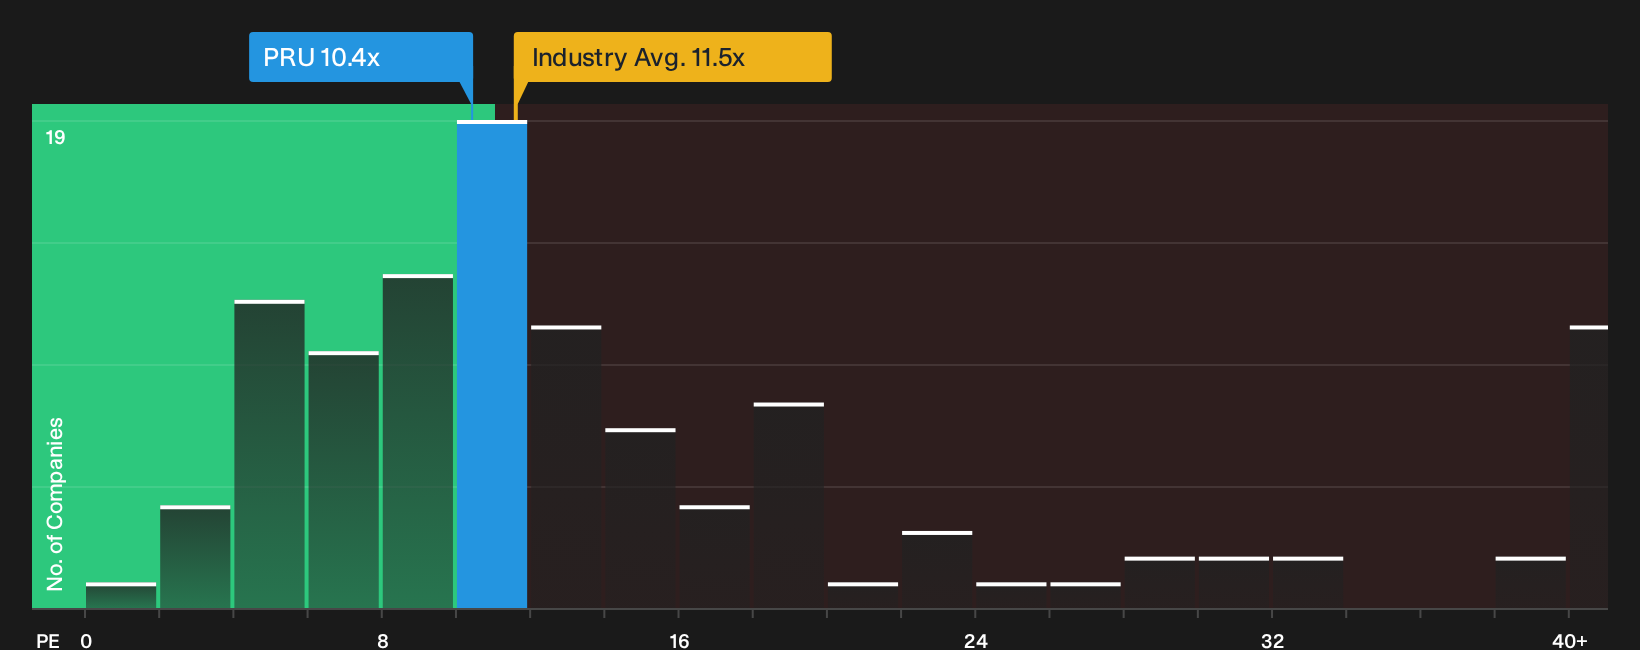
The bearish fair value of $87 leans hard on cautious assumptions. On simple earnings maths, Prudential Financial looks different. The current P/E of 10.4x sits below the US Insurance industry at 11.5x and well under a 15.9x peer average, while the fair ratio is 12.4x. That gap points to valuation risk if earnings stumble, but also room for repricing if the business keeps delivering.
To see how this earnings based view stacks up against other valuation angles, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Prudential Financial can create both hesitation and opportunity, so review the data yourself and be prepared to adjust quickly if it changes your stance with 5 key rewards and 1 important warning sign
Looking for more investment ideas beyond Prudential Financial?
If Prudential Financial has you thinking harder about valuation and risk, do not stop there. Put a wider watchlist to work with fresh ideas.
- Target dependable income streams by reviewing a curated set of higher yielding payers through 5 dividend fortresses that already clear strict financial checks.
- Spot potential value gaps by scanning a focused 18 high quality undiscovered gems that combines solid fundamentals with under-the-radar market attention.
- Prioritise resilience first and filter for 30 resilient stocks with low risk scores built around stronger balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com